

Founder @ Vision Capital Fund. Investor, author, angel. Invest in companies that reflect our best vision for our future. Musings on investing, business & life.
Singapore 🇸🇬 | Global 🌏
Joined October 2017
- Tweets26.1K
- Following1.8K
- Followers28.8K
- Likes43K



Pinned Tweet
I am thrilled to announce the launch of Vision Capital Fund, which has been in the making for over seven years.
We are focused on growing wealth for generations by delivering outstanding long-term investment returns from investing in exceptional companies that best reflect our vision for our future.
Website: visioncapitalfund.co/
Press Release: tinyurl.com/VCFpressrelease
Day One Investor Letter: tinyurl.com/VCFDayOne


Sea Limited $SE 3Q26 Earnings
- Rev $8.6b +43% ↗️🟢
- GP $3.9b +51% ↗️🟢 margin 45.9% +243 bps ✅
- Adj EBITDA $931m +29% ↗️🟢 margin 10.9% -122 bps ↘️🔴
- EBIT $664m +40% ↗️🟢 margin 7.7% -21 bps
- Net Inc $502m +34% ↗️🟢 margin 5.9% -41 bps ↘️🔴
Shopee
- Orders 4.5b +26% ↗️🟢
- GMV $39.7b +24% ↗️🟢
- Take-Rate 15.3% +195 bps ↗️🟢
- Rev $6.1b +41% ↗️🟢
- Core Marketplace Rev $4.6b +51% ↗️🟢
- VAS Rev $724m +0% ➡️🟠
- Goods Rev $749m +45% ↗️🟢
- GP $1.9b +49% ↗️🟢 margin 31.2% +163 bps ✅
- Adj EBITDA $267m +44% ↗️🟢 margin 4.4% +7 bps ✅
- EBIT $155m +41% ↗️🟢 margin 2.6% 0 bps ↘️🔴
Monee
- Consumer & SME Loans $12.6b +60% ↗️🟢
- Active credit users 44m +28% ↗️🟢
- Avg loan o/s +23% ↗️🟢
- NPL >90days 1.3% +20bps ↗️🟡
- Rev $1.6b +64% ↗️🟢
- GP $1.4b +66% ↗️🟢 margin 88.9% +155 bps ✅
- Adj EBITDA $289m +12% ↗️🟡 margin 17.8% -826 bps ↘️🔴
- EBIT $288m +16% ↗️🟢 margin 17.8% -729 bps ↘️🔴
Garena
- Bookings $890m +6% ↗️🟡
- QAU 671.7m +0% ➡️🟡
- QPU 68.6m +4% ↗️🟡
- QPU/QAU 10.2% +40bps ↗️🟡
- ABPU $1.33 +6% ↗️🟡
- Rev $840m +29% ↗️🟢
- GP $600m +40.0% ↗️🟢 margin 71.4% +577 bps ↘️🔴
- Adj EBITDA $458m +46% ↗️🟢 margin 54.5% +645 bps ✅
- EBIT $453m +46% ↗️🟢 margin 53.9% +650 bps ✅
Service
- Rev $7.8b +43% ↗️🟢
- GP $3.9b +51% ↗️🟢 margin 49.7% +269 bps ✅
Goods
- Rev $749m +45% ↗️🟢
- GP $38m +48% ↗️🟢 margin 5.1% +13 bps ✅
1 | Shopee delivered another quarter of strong growth, continue to see long growth runway and expect unit economics to keep improving. Expect FY26 GMV growth of 25% and Adj EBITDA of $1bn.
Shopee delivered another quarter of strong growth while generating the highest quarterly profit we have ever achieved. Our strategies have proven effective at strengthening our fundamentals, giving us a growing buyer base, stronger monetization and improving unit economics. We still see a long runway of opportunity ahead, and we will keep executing with the discipline to capture it. We remain on track to deliver GMV growth of around 25% and an adjusted EBITDA of $1 billion for the full year of 2026.
2 | Shopee saw strong acceleration in new user growth, driving strong growth in active buyers.
The acceleration in new user growth we saw in the second quarter has continued into the third. We engaged and reengaged a broad range of user through both online and offline campaigns, brought our content to more social and video platforms and widened our service options, especially in delivery to serve different user needs. With these efforts, new average monthly active buyers grew more than 50% and the total average monthly active buyers increased by 20% YoY.
3 | Ecommerce monetization also doing well, driven by ads, where ad-paying sellers grew 35%, ad revenue grew 55% and ad-take rates rose 80bps.
Monetization has also continued to do well, driven by ads. Sellers are responding well to the greater value they see in our AI-driven ad solutions. Ad paying sellers rose more than 35% while average asset per seller increased around 13% YoY, and revenue grew more than 55% and our ad take-rate improved by over 80bps YoY.
4 | Expect Shopee monetization to improve, primarily coming from higher-margin advertising and to flow to growing EBITDA.
We expect going forward, our monetization will also be better, primarily from the ad side, less from the xed commission side. And part of that will ow to the bottom line EBITDA improvement over time. And part of that might go to the investment to grow our market further as well.
5 | Continued logistics improvements is allowing Shopee to serve a wider range of buyer needs from instant, same day to low cost services.
Our operational priorities to enhance service quality, price competitiveness and the discovery remain consistent and continue to be driven by our efforts in Logistics, ShopeeVIP and our content ecosystem. Each made good progress this quarter. First, Logistics. We expected our delivery options to serve a wider range of buyer needs from instant and same-day delivery to low-cost services. Our instant delivery service can now deliver as quickly as 1 hour. This has expanded our addressable market by unlocking new spending scenarios where speed matters most. These tend to be high-frequency categories such as the growth rate and the pharmaceutical items, boosting our overall purchase frequency.
6 | Strong traction in Indonesia and Thailand, orders in Indonesia 2X, same day delivery now 15% of orders in Bangkok.
In Indonesia, orders using the services more than doubled YoY, with cost per order declining year-on-year. Retailer share have increased the service. We now have more than 12,000 offline stores on our instant platform and growing.
Adoption is also growing in Thailand, where instant and same-day delivery rate now account for nearly 15% of orders in Greater Bangkok. We will continue to grow this service in areas where demand is high and the unit economics make sense.
7 | Buyer self-collection reached 30% in Singapore and 15% in Malaysia, which is a much cheap shipping option.
In the third quarter, buyer self-collection order penetration reached more than 30% in Singapore and more than 15% in Malaysia. In Indonesia, our economical shipping option has gained strong adoption and now accounts for more than half of total orders. This cost of order is more than 20% lower than the platform average in the market. These initiatives allowed us to offer free shipping at a lower minimum spend, giving our buyers the exibility to choose between cost and speed and letting us serve a broader range of buyers' needs.
8 | Shopee remains focused on scaling fulfilment quickly, orders grew 25% QoQ, unit economics improving, parcels delivered next day or sooner grew twice as fast as overall growth.
We have also continued to scale fulfillment quickly. Sellers have responded well to our fulfillment offerings as we help them take on the complexity of storing, packing and shipping. This represents significant efficiency gains for them, especially during peak campaign period where orders may be several times higher than normal. With our services, sellers can build their businesses more easily without having to increase their own warehouse space or staff size. In the third quarter, fulflled order volumes accelerated to around 25% QoQ. Unit economics for our fulfilled by Shopee service improved sequentially in Asia, and we see further room to gain efficiency through higher warehouse utilization and automation. Fulfillment also drives synergies with delivery, enabling us to deliver more packages more quickly. The number of parcels delivered by the next day or sooner grew over 16% YoY, more than twice as fast as our overall order growth.
9 | ShopeeVIP continues to grow rapidly, hitting 21m +40% QoQ, and members now account for 25% of Shopee’s overall GMV, and have higher monthly retention of 80%, and spend more.
ShopeeVIP is growing fast. Membership across markets exceeded 21 million at the end of September, up more than 40% quarter-on-quarter and members contributed close to 25% of Shopee's overall GMV. The program is demonstrating stickiness with monthly retention around 80%. Members show a consistent double-digit percentage uplift in spend on average after subscribing. And with more sellers and partners investing alongside us in membership benefits, the program's unit economics improved sequentially.
10 | Orders from live streaming and short-form video grew 45% and now account for 25% of physical good orders in SEA.
Orders from live streaming and short-form video grew more than 45% YoY and accounted for more than 25% of physical goods orders in Southeast Asia. Unit economics also improved sequentially. Beyond our app, our a liate program remains an effective and growing channel to bring new buyers to Shopee from other platforms.
11 | Content business is profit margin accretive rather than dilutive.
For content ecosystem, which includes video live stream, I think it's a bit hard to split a particular segment to the EBITDA level because there are many shared costs below that. I think for us, we look at sort of variable cost or contribution margins to our platform, the content platform that has a positive contribution margin. Essentially, what we're saying is if we grow content business more in our platforms, we'll have more profit rather than has less profit for our businesses.
12 | Social media orders from YouTube, Facebook, and Instagram grew rapidly from affiliate creators.
In the third quarter, orders driven by YouTube content more than doubled YoY and Shopee affiliate orders generated by Facebook linked creators grew more than 90% QoQ. On Instagram, more than 4 million reels have been tagged with Shopee products since we launched the partnership in April with the number growing more than 4x QoQ.
13 | Shopee is one of the few ecommerce platforms that is open to agents with Meta Muse, while still early, expect it to become a solid channel for buyer acquisition and GMV growth.
Shopee is also one of the early connector partners for Meta's Muse AI personal assistant that has just launched in Singapore. Users will be able to research and compare products on Shopee through Muse, helping them make purchase decisions tailored to their preferences. The partnership is still at an early stage, but we see potential for it to become a solid additional channel for buyer acquisition and incremental GMV growth over time.
14 | Open to working with agents, because checkout, seller and buyer relationships still remain with Shopee.
Coming to the second question on the agentic AI, we actually partnered with a range of partners starting from ChatGPT and now as you mentioned, the Muse. At this point in time, all the checkout and seller relationships and buyer relationships happen within the Shopee platform. And we didn't see a meaningful impact to our economics for the near future.
15 | Brazil remains the fastest-growing for Shopee, and grew faster than the broader market, gaining share, and continue to improve buyer waiting time by 12%.
Brazil remains our fastest-growing market, and we again grew faster than the broader market in the third quarter. Logistics improvements underpinned this growth. We continue to widen the range of faster delivery options we offer across the country with average buyer waiting time improving 12% YoY. We have branched into air delivery, cutting delivery times to the North and the Northeast regions significantly.
16 | In São Paulo, ~40% of parcels now arrive next days do 60% within 2 days, stronger delivery capabilities is adding more sellers to Shopee in Brazil
In Greater Sao Paulo, around 40% of parcels now arrive at the next day and nearly 60% within 2 days. Our new instant delivery service there, Shopee Turbo already delivers in under 4 hours from more than 7,000 partner stores. Stronger delivery capabilities have enabled us to onboard more sellers to fulfillment.
17 | This is allowing Shopee to expand beyond smaller-item ecommerce to more expensive and larger items into more upmarket buyer segments and higher value categories, and with Shopee Mall, which is where MELI dominates.
For example, we rolled out an in-house delivery service for bulky items such as the large appliances and furniture, combined with our strong service reputation and reliable cross nation coverage. This has made more large item sellers willing to ful ll with us.
Across the country, fulfillment order volume more than doubled YoY. These service quality improvements have helped drive stronger growth in higher-value categories. More upmarket buyers are joining Shopee and existing buyers are shopping across more categories with us. Automotive and home improvement categories grew more than 80% yearon-year and more brand sellers have come on board.
Shopee Mall orders carried an average basket size, almost 3x the platform average. Looking ahead, we see a lot of headroom to grow in this exciting market.
18 | Don’t see a meaningful growth deceleration for Shopee GMV yet, but noticed more value-seeking ecommerce buying behaviour.
On the Shopee growth, first of all, we don't see a big Shopee GMV growth rate slowdown yet. As we shared earlier, in Q3, we do see a meaningful growth, similar growth rate compared to last quarter from a year-to-year perspective, if we take away the ForEx impact. You are right that there are many macro factors like fuel price, et cetera, impacting the consumption.
Overall, we see that although we have noticed some more value-seeking behaviors in our market due to all this macro environment, but the general overall demand is relatively resistant.
19 | Shopee is well positioned as they are focused on long-tail products with competitive pricing that positions them better with people who need to buy rather than impulse buying. Still see long growth runway in e-commerce.
But again, I would like to reiterate that our competitive advantage will continue to differentiate us from the peers even in the macro situation that we are in right now, given that we are -- we built our platform around long-tail products and also the pricing in our platform is a lot more competitive compared to other platforms online or compared to the alternative offline as well. On top of that, many of our -- large part of our platform's GMV are driven by the people who have the need to purchase rather than people who have impulse buying. All those make us -- put us in a more resistance position on the growth for our e-commerce in our market. I think we will continue to monitor our market very closely for any changes. But again, given all the things we mentioned above, and also the e-commerce penetration are still relatively low compared to many other markets, we still believe that there is a big runway for us to grow our e-commerce in the regions.
20 | Monee has grown beyond its original origins of payments into mobile wallet, credit, and digitial banking, and is growing fast and very profitable.
Monee has grown well beyond its origins as a payment infrastructure serving our internal business needs. Today, it has evolved into a financial services business across mobile wallet, credit, digital banking and more. Monee has shown consistent strong growth and has been profitable for the last 3 fiscal years.
21 | Monee has reached the scale and maturity to benefit from becoming independent, and a standalone public listing in the coming 1-3 years will make sense.
We believe Monee has reached the scale and maturity to extend itself and would benefit from becoming more independent…Our ambition is to keep growing Monee into a full financial ecosystem with inclusion at its heart, serving users across their life cycle needs from unsecured loans to secured lending, insurance, wealth management and more. We believe a stand-alone listing would give Monee the dedicated capital base it needs to build this ecosystem and let it invest for growth while managing risk with discipline.
We hope to list the Monee at the right time in the next 1 to 3 years, taking into consideration factors such as market conditions, macro environment and regulatory requirements.
22 | Monee and Shopee will continue to work together, and remain a key payment and credit partner for Shopee, and insights from Shopee used to drive Monee.
I want to be clear about what does not change. Monee and Shopee will continue to work closely together as they do today. Monee will remain a key payment and credit partner for Shopee and Shopee will remain a key platform for Monee to reach users. Insights from our businesses will continue to empower Monee's growth.
23 | BNPL is growing rapidly, driving faster growth in Shopee’s SPayLater portfolio >2X, and is now 25% overall and nearly 40% in Malaysia.
As pay later is becoming an everyday way to pay both online and offine in many of our markets, our off-Shopee SPayLater portfolio more than doubled year-on-year to nearly 25% of our entire SPayLater portfolio at the end of September. In Malaysia, its share is nearly 40%. In Thailand, the ShopeePay unlimited cards allows SPayLater users to accept their approved SPayLater credit limit wherever Mastercard is accepted.
24 | Risk management remains top priority for Monee, 90 day NPL ratio inched up small to 1.3%. Continue to proactively adjust underwriting criteria depending on macro.
Risk management remains our top priority as we continue to grow our loan book. Our 90-day NPL ratio was 1.3% at the end of September. The modest uptick primarily reects an evolving credit environment, especially in Thailand and Brazil as well as market and product mix, including faster growth in Brazil in o-Shopee SPayLater. Our underwriting is highly responsive to market conditions. We proactively adjusted our underwriting criteria and credit limit management for selected customer segments at early signs of softness to maintain disciplined growth and optimize risk-adjusted returns. We are staying close to the data and we'll keep adjusting as needed. So our loan book growth stays healthy and sustainable.
25 | Garena grew bookings LSD despite strong comps with improving profitability.
Garena delivered a solid third quarter with bookings continuing to grow from the high base set last year. Profitability also improved. Free Fire anchored this performance with a strong bookings growth and Arena of Valor continued its strong momentum from its 10th year anniversary celebrations.
26 | Setting up Sea Cloud as a frugal start-up, not seeking to own large amounts of physical capacity, only for customers with dedicated computing capacity, and pursue with clear customer commitments and attractive returns.
We are setting up Sea Cloud as a frugal start-up so that it can stay nimble and respond quickly to market demand. Our focus is the software and customer relationships, not owning large amounts of physical capacity, where customers need dedicated computing capacity, we will only pursue opportunities with clear customer commitments and attractive returns. We will mainly look to partners and customer prepayments to fund the physical infrastructure.
27 | Still early, do not expect Sea Cloud to have a significant impact on financials, they still figuring out. Probably work better for their SMB merchants than the AI labs or the enterprises which is what the hyperscalers focus on.
As a result, we do not expect Sea Cloud to have a significant impact on our financials for now. It is still early, and we will update investors on any meaningful developments.
So that is kind of the big picture we are looking at, and we think the demand will be huge, and this is just at a very, very early stage. So we want to get into this business early. There's a lot of things we don't know yet. And again, this is very early. This is kind of a start-up. So there's a lot of things we need to gure out, for example, what exactly the segment we should focus on, what exactly type of customers we should focus on and what is the best business model we should use. We think we'll get a better picture when we really get into the -- get our own feet into the game and we start to get the rst-hand experience.
28 | Sea Cloud has not secured any enterprise contracts yet, will primarily buy GPUs (as don’t have own chips). Expect the business to be more deal driven than its current businesses.
Sea Cloud, for your question, as you know, this is just at the very, very beginning of the business. At this moment, we don't have any -- we haven't secured any enterprise contracts. And for the investment in the data center and the GPUs, we -- let me put it in this way, we denitely probably will invest in the GPUs primarily for our own use. So regardless if there is a Sea Cloud business or not, like how the business progress down the road, we are going to invest into GPUs and primarily for all the internal use cases.
But the business nature is a bit di erent from the Sea Cloud. I think it will be very much deal by deal driven, at least at the beginning stage and with very, very speci c target in terms of the custom
29 | Another strong quarter across all three businesses with solid growth momentum, operational efficiency, and improving profitability.
In conclusion, we have delivered another strong quarter. Our 3 businesses have all expanded their addressable opportunity and strengthened their competitive position. Unit economics continue to improve across many of our initiatives, a testament to our financial discipline and operational efficiency. Our positive momentum across the rst 3 quarters give us greater condence for the rest of the year.
➡️ Key takeaways on Sea Limited: SEA’s most dominant ecommerce platform with Shopee and increasingly its logistics fulfilment platform SPX and its credit lending business Monee riding on Shopee. Garena continues to recover and provides the reinvestment ability to double down. Continue to see a long runway of growth opportunity, and not concerned over the near-term higher investments weighing on near-term profitability, which are beneficial for longer term growth and profitability. Valuations remain undemanding and attractive.


Chinese drone deliveries are really epic and next level.
This was at Huangshan (黄山). One can see and hear drone deliveries here to hotels all day long every few minutes.
1
8
2,066
A black swan and her two cygnets at Hangzhou's Qingshan Lake Water Forest 杭州青山湖水上森林, also known as Matcha Lake.
"Black swan" is used to describe a rare, unexpected event with big consequences. The term goes back to when Europeans believed all swans were white. In 1697, Dutch explorers found black swans native to Australia and that belief fell apart.
Watching this family swim by earlier today, I was reminded that rare depends on who is looking. To Europe, black swans were unthinkable. To Australia, they were just swans.
Perspective matters. Rarity says more about the observer than the swan itself.
10
1,695


Cloudflare’s Matthew Prince brilliant thoughts on neoclouds in their most recent 3Q26 earnings call:
”We are an engineering company. We are not a financial engineering company...
We are focused on how we can actually deliver real operational excellence…
You can’t sell $1 for $0.50 and be in business over the long term.”

There are good days and bad days. Remember what you do on your bad days is often more important that what you do on your good days.
14
1,969
Cloudflare $NET 3Q26 Earnings
- Rev $783m +39% ↗️🟢
- GP $557m +34% ↗️🟢 margin 71.2% -276 bps ↘️🔴
- NG EBIT $137m +60% ↗️🟢 margin 17.5% +223 bps ✅
- NG Net Inc $144m +40% ↗️🟢 margin 18.4% +10 bps ✅
- Net Inc -$34m ↘️🔴 margin -4.4% -412 bps ↘️🔴
- OCF $215m +29% ↗️🟢 margin 27.5% -221 bps ↘️🔴
- FCF $82m +9% ↗️🟡 margin 10.5% -285 bps ↘️🔴
Biz Metrics
- Cust >$100k ARR 5,006 +25% ↗️🟢 (75% of revenues)
- Net Retention 122% ↗️🟢(from 120% in 2Q26)
- RPO $2.9b +34% ↗️🟢
- Channel Partners Rev $247m +65% ↗️🟢
- Direct Customers Rev $535m +30% ↗️🟢
Revenue by Geography
- US $408m +44% ↗️🟢
- EMEA $202m +32% ↗️🟢
- APAC $112m +32% ↗️🟢
- Other $61m +46% ↗️🟢
Mgmt Guide
- 4Q26 Rev $846m +38% ↗️🟢
- 4Q26 NG EBIT $157m
- FY26 Rev $2.964b +37% ↗️🟢 (raise from $2.87b ✅)
- FY26 NG EBIT $463m (raise from $445m ✅)
- FY26 NG Net Income $508m (raise from $471m ✅)
- FY26 Network Capex 14-15% (same)
- LT EBIT margin 30%+ ↗️🟢 (raise from 20%+ ✅)
- LT FCF margin 30-35%+ ↗️🟢 (raise from 25%+ ✅)
1 | Super strong quarter and growth continued to accelerate, crossing $3bn annualized revenue.
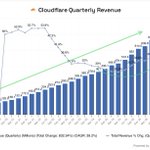
There's no other way to say this. By nearly every metric, we had our best quarter ever. We again accelerated growth and became more profitable at the same time, delivering our fastest revenue growth in nearly 4 years and achieving our highest operating margin in the history of the company. We crossed $3 billion in annualized revenue, generating $782 million in the third quarter. That's up 39% YoY.
2 | Rapid revenue growth and higher net retention was driven by even faster revenue growth of the larger customers, now accounting for 75% of revenues, and continue to grow.
The higher you go among these cohorts based on the amount of spending committed to Cloudflare, the faster revenue is growing year-over-year. In other words, the bigger the size of the customers' annual spend with us, the faster they are growing with Cloudare. Of particular note, we added almost as many $5 million-plus customers in the first 3 quarters of 2026 as we had $5 million-plus customers in total at the end of just last year. Revenue contribution from large customers was 75% of revenue during the quarter, up from 73% in the third quarter last year. The significant expansion with our large customers drove an acceleration in our dollar-based net retention rate to 122% in the third quarter, up from 120% last quarter and up from 119% in the same quarter last year.
3 | Growth was driven by highly diversified momentum, not just AI, but across different verticals, without any concentration, driving the strong beat and raise.
I would say that we're seeing real strength across just about every different vertical that's out there. And so yes, we're seeing AI growth, but by no means would I say that this is really concentrated around AI in particular.
the demand is driven by a highly diversified momentum. The developer count, the traffic on the network, 160,000 net new customers, the largest add in every cohort we count from a revenue perspective. No concentration, customers in financial verticals, government and across the globe. So we see a broad base for this momentum, and we are guiding to what we see, and this is reected, I think, in the strong beat and raise you see for the fourth -- from the third quarter into the fourth quarter.
4 | Strong upside was driven by more customers joining pool of funds or burning their pool of fund commitments faster and have to renew to even larger pool of funds.
We saw continued strength in our variable revenue. It was the primary contributor to the upside. And the surprising or positive part of that was it was driven across a lot of customers either joining pool of funds or, as you said, burning to their pool of funds commitments faster and therefore, have to renew earlier and as part of the renewal process, sign up to even bigger pool of funds concepts. because it has been driven by a long tail of customers, this, of course, inuences how we build guidance for the fourth quarter that it was not a concentrated event, but a long tail of events across many customers and is part of the reason why we guided to what we guided.
5 | Expect further upside to net retention driven by pool of funds, and largest customers growing the fastest.
We have higher ambitions when it comes to DNR than what we're currently achieving. And I think the combination of pool of funds, the largest customers growing the fastest and the friction that these concepts -- the pool of funds contracts take out of the expansion process are driving that.
6 | Monster quarter supported by record sales productivity and highest ACV growth and highest quote attainment.
But that's just the start of what was a monster quarter. The strong momentum we've been seeing in our business continued to accelerate in the third quarter. It's like the engine was firing on all cylinders, and we found another gear. Some highlights. Sales productivity reached a new record in the third quarter and increased year-over-year for the 11th consecutive quarter. In Q3, we delivered our highest ACV growth ever and highest quota attainment in more than 5 years.
7 | Added more than 158K paying customers this quarter.
We added more than 158,000 paying customers this quarter. That's a 110% growth in paying customers YoY and nearly double the previous record of more than 80,000 we added in Q2. We also achieved record year-over-year net additions across all our large customer annualized revenue cohorts from $100,000 to $500,000 to $1 million to $5 million. Across every one of those, we grew at a new record pace.
8 | Much of that execution improvement came from the GTM transformation led by Mark Anderson over the past 3 years previously to match the strong product and engineering teams. He will staying on as adviser for a year.
Much of that execution improvement has come from the transformation of our go-to-market engine to match our already worldclass product and engineering teams. Mark Anderson deserves a huge amount of credit for shepherding us through that transition. With his well-earned retirement coming at the end of this year, we wanted to nd a successor with a proven track record of scaling global sales organizations to turbocharge our already robust go-to-market momentum.
And to ensure the smoothest transition, Mark Anderson has agreed to stay on as an adviser for at least the next year. I know he'll always bleed orange and be there to help close a customer if we need him.
9 | Christian Smith will replace Mark Anderson as the new President of Revenue. His immediate priorities to double down on GTM execution, accelerate enterprise momentum, and customers get more value rapidly.
I'm incredibly excited to welcome Christian Smith to Cloudare as our new President of Revenue. No one will ever replace Mark, but Christian's skill set and experience building and enabling world-class go-to-market organizations match perfectly with the current stage of Cloudare to further accelerate our next wave of growth at scale.
I've spent my entire career scaling enterprise go-to-market engines with operational rigor, building world-class partner ecosystems and driving intense customer focus. Mark Anderson has built an incredible foundation over the past 3 years at Cloudare. And my immediate priorities are to double down on go-to-market execution, further accelerate our enterprise momentum and ensure our customers get even more rapid compounding time to value from our platform.
10 | Will be experimenting with different GTM, across forward deployed engineers, solution engineers, and account executives.
But going forward, I think we're going to be experimenting with what's the shift, like how much are we doing what we're already doing, but at greater scale? How many forward deployed engineers do we have that are out there, which we already have at our largest customers, helping them get the most out of Cloudflare. That certainly is going to increase. What's the ratio of solutions engineers to AEs? What exactly are the specific technical overlays and how specific do we want the individual salespeople to have knowledge in all of the different products that we have.
11 | When Cloudflare laid off people, it was to shift headcount towards more builders, rather than cutting headcount.
when we made the decision to lay people off, it was an incredibly hard decision. We let go of a number of people who were extremely talented, people who I consider friends. And I'm proud of the fact that we had an incredibly generous severance package. We continue to vest people's shares, which was something that most companies haven't done.
how there were 3 types of functions within any company. There are people who build things. There are people who sell things and there are people who measure things. And what we found with AI is that the builders are getting more efificient than ever. And so we're trying to hire as many great builders as we can. And again, as you said, we're not trying to cut headcount. We actually are just shifting headcount to more builders.
12 | Won numerous customer deals.
A rapidly growing AI company expanded their relationship with Cloudare, signing a 1-year $11 million pool of funds contract for our Workers Developer platform.
A Fortune 100 cloud infrastructure provider expanded their relationship with us, signing a 13-month $15.5 million contract for Magic Transit.
A cabinet level U.S. federal department signed a 5-year $10.3 million contract for our SASE portfolio.
A rapidly growing multinational neobank and ntech company expanded their relationship with Cloudare, signing a 3-year pool of funds agreement with an average ACV of more than $3 million.
A fast-growing technology company expanded their relationship with Cloudare, signing a 39-month $9.5 million pool of funds contract for application services and our workers developer platform.
A leading global consulting rm expanded their relationship with Cloudare, signing a 3-year pool of funds contract for more than $7 million for Zero Trust application services and our Workers developer platform.
13 | In Q3, Cloudflare added 5% of the entire web. Result of the convergence of Cloudflare’s platform and customers wanting Cloudflare to protect them.
To give you a sense, based on third-party data, between July 1 and today, we added approximately 5% of the entire web to Cloudflare. That's wild. It's more than the total market of all our reverse proxy competitors combined added to our network in a bit over a quarter. We've been growing throughout our entire history, but recently something changed. The rate of growth inected in October of 2025 then accelerated again in July of 2026 and then again at the beginning of this October.
So what's going on? I think it's the convergence of 2 things. First, we have built the development platform for the future of the AI-powered Internet. And second, the security landscape is getting so scary that the best viable strategy regardless of who you are is to ensure you have Cloudare protecting you. To the first, hyperscalers and even neo clouds were built around container technology.
In other words, Cloudare isn't a neo cloud. We're also not, as some of you have called us, the fourth public cloud. We're something di erent. We're the first agentic cloud and developers are flocking to us to build the agentic AI future.
14 | New security vulnerabilities only keep growing, but Cloudflare through its network will hear of these first.
It may seem like the sky is falling with a number of new security vulnerabilities that have been reported over the last few weeks. I wish I could tell you we were through the worst, but we're not. Because of the vast percentage of the Internet that already sits behind Cloudflare, we are among the first to receive quiet disclosure of new vulnerabilities. We've partnered with nearly every major frontier AI lab and security company searching for aws in existing software. When they find something, they notify us through a trusted reporter process, and we quietly put protection in place for all our customers, whether they pay us or not.
15 | Cloudflare has the Internet stack and is able to protect its customers before the bugs are publicly disclosed.
We believe protecting everyone is important to fulfilling our mission of helping build a better Internet and living up to that mission has ensured that we are trusted and nearly always get early warning of the worst problems researchers discover. The bugs you read about over the last few weeks and the ones I suspect you will read about over the next few years were less impactful because Cloudflare has the Internet stack. That, of course, creates a virtuous cycle. We know what bugs are coming. We protect our customers before the bugs are publicly disclosed. Companies increasingly know that if they are behind us, they are more likely to be protected whatever the future brings.
16 | AI is becoming a secular tailwind for Cybersecurity companies which can benefit from growing network effects.
I think one of the biggest drivers is the fact that it's sort of a secondary effect of AI, which is AI is nding more and more security aws that are out there. Just last week and the week before, we had 6 of the worst Internet security bugs of all time announced over the course of fewer than 14 days. And we're not done. We have already gotten disclosures of many, many, many more extremely scary bugs, which researchers have found, have quietly disclosed to us, and we have protected our customers from.
17 | Cloudflare recorded revenue from Act 4 products for the first time, and is in a perfect position to bring both agent and the places that the agent is looking for. Expect this to become the largest part of Cloudflare’s business.
I'm proud to announce that we recorded in Q3 our first revenue for what we've called Act 4 products, those where we're helping invent the new business model of the Internet, and I expect we'll talk a lot more about that in the quarters to come.
Cloudflare is in a perfect position to help bring both of those things together, both the agent and the places that might have whatever the agent is looking for. And so like that is coming. I don't know exactly how long it will be before it turns into major sources of revenue. But if you look out in the more distant horizon, if you look 10 years out, I would imagine that this becomes the largest part of Cloudflare's business.
18 | Cloudflare expects to achieve GAAP profitability in 4Q26, much earlier than its 2028 timeline.
We also expect to achieve GAAP profitability in the fourth quarter, significantly earlier as compared to our outlook from this year's Investor Day to reach this milestone at the latest by 2028.
19 | Meta is a customer of Cloudflare.
And in the case of Muse, I mean, Meta is a customer, and it's been incredibly fun to watch them and help them scale that product and just see the explosive growth that we're seeing. So we're bene ting as that product grows directly. I think the
20 | Google is not doing what has been aligned with the content creators, publishers, application developers, over what they want to do.
We've had examples over the last several months in the case of Meta, in the case of Google, where at times, there's been places where what they have been doing hasn't aligned exactly with what the content creators, publishers, application developers, financial services organizations, e-commerce companies, what they want to do. And Cloudare is finding ourselves over and over and over again in the center of those questions and acting almost as a mediator between the 2 sides.
21 | Cloudflare was never focused on being a CDN, they only did caching because they didn’t want security to slow things down.
And I think one of the things that's different from us than -- I mean, we've never been a CDN, like that's -- the fact that we do caching is only because we were afraid that our security services would slow things down and caching is an obvious computer science way of dealing with that. But we've really never been focused on charging for CDN traffic in any meaningful way.
22 | Cloudflare will not get into the business of neoclouds, recognise it as financial engineering, and prefer to deliver real operation product engineering.
we've gotten approached over and over again to say, would we do something like what the neoclouds are doing. And I think that what our answer has always been is we're an engineering company. We're not a financial engineering company. And so we're focused on how we can actually deliver real operational excellence and get real advantages for every CapEx dollar that we spend in order to deliver more benefit. And so we've watched a bunch of really dumb deals get done. And obviously, the market is digesting those right now. Those just aren't the sorts of deals that we would ever do. And I think as the market gets more rational and as we actually gure out, okay, you can't sell $1 for $0.50 and be in business over the long term.
23 | Developers grew from 7mil to 10mil and that is driving the flywheel of growing paying customers, adding 158K paying customers, hitting critical mass.
Again, the rate at which developers are growing is just extraordinary. We went from 7 million to 10 million in just a quarter. And I'm just incredibly proud that when developers are looking for what the platform in the future is, they're choosing Cloudflare. The first way it's translating into it is in paying customer count. You can see that we had a record addition of new paying customers this quarter of 158,000 paying customers, almost double our previous record from last quarter. And a lot of that is because that's -- those are developer customers that are there.
So we're really proud of the fact that the developer platform business is growing as well as it is, that we've, I think, hit what is critical mass and will continue to grow from here in terms of developer count.
24 | More and more are building full applications entirely on Cloudflare Workers. Workers is becoming a big component of every pool of funds deal, with growing adoption across the board, and developers are insisting on it.
And I think more and more, you're seeing that people are building full applications entirely on Cloudflare Workers, and there are whole classes of start-ups. It was really fun at our customer conference -- we actually did a little sort of mini kind of start-up competition pitch.
But almost every pool of funds deal that we sell, Workers is a big component of it. And it's in the toolkit that's there. And what we find is even if somebody bought -- they bought the Cloudflare platform, they sign up for a pool of funds deal, they may not have even initially thought that they were signing up for Workers. The minute the developer team hears that now they have access to Workers, all of a sudden, they're turning to it because it's such a powerful tool in their toolbox in order to get their job done. And so across the board, we're seeing much more adoption of Workers. We're seeing it not just from small customers, but from very large customers as well. It's not just from AI companies, it's from across the board, almost every industry that's out there. And more and more people are seeing that they need to have Workers as a tool in the toolkit of their developers. Their developers are insisting on that. And that's driving not just the sale of Workers, but then also the sale of our SASE product, the sale of our other products. Cloudflare is a platform. And increasingly, our customers are recognizing us as that key strategic vendor that is providing one of their key platforms.
25 | Think customers are not just buying Zero Trust, but the overall Cloudflare platform, as customers are increasingly seeing Cloudflare as their strategic partner.
And so what we're seeing more than anything is people aren't buying just Zero Trust. They're not just buying WAF, they're not just buying DDoS. They're not just buying the developer platform. They're buying the overall platform of Cloudare. And they're seeing that if you incorporate and use all of what we do that you get a much more holistic solution. And as a result, like the Zero Trust vendors essentially just become features within what is a much larger platform play. And so I think that -- the biggest recognition is that the smartest companies in the world are increasingly seeing Cloudare as a true strategic partner to provide one of their core platforms. And that's what's driving not only our wins in Zero Trust, but our wins across the entire platform and the increased adoption that we're seeing and the faster consumption that we're seeing out of the pool fund deals that we sell.
➡️ Final Thoughts on Cloudflare’s $NET:
Cloudflare is the increasingly dominant connectivity cloud an all-in-one enterprise networking and security platform that customers increasingly want to consolidate behind a single, global provider. Supported by its innovative approach of partnering with ISPs reducing bandwidth and co-location costs has allowed Cloudflare to build out an increasingly formidable cloud infrastructure that with single programmable software stack allowing it to distribute workloads globally and dynamically to offer products at lower costs. Because it sits in front of its customers traffic, it has tremendous optionality to keep expanding its now vast 60+ product offering, creating a virtuous cycle where each additional service can be added without significant marginal costs. Good to see strong sales/GTM accelerating revenue and RPO growth as it shifts from being product led to more enterprise-driven. Not concerned with the near-term gross margin weakness, confident that they can drive free to paid, utilization higher over time, and expand usage of developer products. In addition, the layoffs should make it more efficient and improve its long-term profitability, and would like that to keep improving over time.


Go big or go home. The truth is those who go too big, too often, almost always end up going home.
2
20
2,470
Mercado Libre $MELI 3Q26 Earnings
- Rev $10.8b +45% ↗️🟢
- GP $4.4b +37% ↗️🟢 margin 40.8% -253 bps ↘️🔴
- Contribution $1.5b +6% ↗️🟡 margin 13.8% -503 bps ↘️🔴
- Adj EBITDA $982m +5% ↗️🟡 margin 9.1% -346 bps ↘️🔴
- EBIT $676m -7% ↘️🔴 margin 6.3% -348 bps ↘️🔴
- Net Inc $448m +6% ↗️🟡 margin 4.2% -151 bps ↘️🔴
- FCF $285m +38% ↗️🟢 margin 2.7% -13 bps ↘️🔴
Revenue by Segment and Type
- Commerce Rev $6.1b +47% ↗️🟢
- Commerce Pdt Rev $1.5b +67% ↗️🟢
- Commerce Svc Rev $4.6b +42% ↗️🟢
- Fintech Rev $4.6b +42% ↗️🟢
- Fintech Svc Rev $2.2b +29% ↗️🟢
- Fintech Credit Rev $2.4b +58% ↗️🟢
- Ad Rev +51% ↗️🟢
Brazil
- GMV +44% ↗️🟢
- Items sold +45% ↗️🟢
- Acquiring TPV +31% ↗️🟢
- Rev $6.0b +50% ↗️🟢
- Commerce Rev $3.7b +52% ↗️🟢
- Fintech Rev $2.3b +47% ↗️🟢
- Contribution $479m +0.8% ➡️🟠 margin 8.0% -387 bps ↘️🔴
Mexico
- GMV +31% ↗️🟢
- Items sold +25% ↗️🟢
- Acquiring TPV +43% ↗️🟢
- Rev $2.4b +47% ↗️🟢
- Commerce Rev $1.5b +39% ↗️🟢
- Fintech Rev $976m +62% ↗️🟢
- Contribution $346m +13.4% ↗️🟡 margin 14.2% -423 bps ↘️🔴
Argentina
- GMV +24% ↗️🟢
- Items sold +19% ↗️🟢
- Acquiring TPV +55% ↗️🟢
- Rev $1.8b +26% ↗️🟢
- Commerce Rev $678m +37% ↗️🟢
- Fintech Rev $1.1b +20% ↗️🟢
- Contribution $613m +7.2% ↗️🟡 margin 33.7% -598 bps ↘️🔴
Other LATAM
- Acquiring TPV +18% ↗️🟢
- Rev $502m +63% ↗️🟢
- Commerce Rev $351m +64% ↗️🟢
- Fintech Rev $151m +62% ↗️🟢
- Contribution $45m +5% ↗️🟡 margin 9% -500 bps ↘️🔴
Biz Metrics
- Fintech MAU 92.9m +29% ↗️🟢
- Unique active buyers 93.9m +22% ↗️🟢
- GMV $22.8b +38% ↗️🟢
- Live listings 1.3b +102% ↗️🟢
- Items sold 867m +37% ↗️🟢
- Items sold per Unique Active Buyer 9.2 +12% ↗️🟡
- Same & Next Day Shipments 258m +49% ↗️🟢
- Managed network penetration 97.6% +280bps ↗️🟢
- TPV $108.8b +53% ↗️🟢
- Fintech TPV $40.5b +69% ↗️🟢
- Acquiring TPV $68.3b +43% ↗️🟢
- Acquiring ON TPV $23.8b +38% ↗️🟢
- Acquiring OFF TPV $44.5b +46% ↗️🟢
- Total Pymt Txn 5.7b +41% ↗️🟢
- AUM $25.1b +67% ↗️🟢
- NIMAL 20.1% -90bps ➡️🟡
- Past Due 15-90 days 7.0% ➡️🟡
- Past Due >90 days 19.3% ↗️🟠
- Provision >15 days 103% ➡️🟢
- Provision >90 days 140% ➡️🟢
Credit Portfolio by Type
- Credit Portfolio $17.9b +62% ↗️🟢
- Consumer $6.1b +49% ↗️🟢
- Credit Card $8.4b +73% ⤴️🟢
- Merchant $2.9b +53% ↗️🟢
- Asset-Backed $0.4b +62% ↗️🟢
1 | Strong quarter with 41% growth in revenue, Growth was broad-based, and Brazil was a standout with commerce, driven by the lowered free shipping threshold.
MercadoLibre delivered another quarter of strong growth with net revenue and financial income, up 41% YoY on an FX-neutral basis. Growth was broad-based across businesses and countries, with Brazil standing out with the fastest growth rate. We're particularly pleased with commerce in Brazil, where GMV growth remained strong at 36% year-on-year. Users are shopping more frequently with us which is exactly the habit our investments are designed to build. Before we lower the free shipping threshold last year, items per buyer were growing at a single-digit pace.
2 | FinTech delivered another solid quarter with strong profitability and strong growth, while MPS remained stable despite a weaker credit environment in Brazil and Argentina.
FinTech delivered another solid quarter with strong profitability. Monthly active users grew 29%, assets under management, 67% and and the credit portfolio, 62%, while NPLs remained stable despite a weaker credit environment in Brazil and Argentina.
3 | Focus on growing credit in Brazil while reducing risk at the margin.
We have seen very good results on the credit front across countries. I think you specifically asked about Brazil, I imagine. I would say that given the information we have and our discipline on risk management management, we have been able to continue to grow, but also reducing risk at the margin basically. So we have been able to continue to grow across most segments. On the most like segments, we have been a little bit more cautious. And what we are seeing is stability across products are 50 to 90 NPLs was 7%, stable both versus last quarter and a year ago, and we continued growing at 62%.
4 | Profitability declined by 30 basis points sequentially, primarily due to higher net shipping costs from the lowered free shipping threshold and higher sales and marketing spending to develop their affiliate commerce program.
Turning to profitability. Income from operations was $676 million, with a margin of 6.3%, down 40bps from last quarter. Two factors drove this, higher net shipping costs and higher sales and marketing spending as we continue to develop our affiliate program. These are deliberate investments. They reflect the trade-off we described in the shareholder letter. We are investing part of today's margin to accelerate the shift of commerce and financial services online in Latin America and to build lasting habits across our ecosystem.
5 | The effects from the lowered free shipping threshold are still working through. Buyers are purchasing more often but in smaller baskets, which means less revenue per shipment. Seeing higher costs initially before volume catches up eventually later.
The first is last year's decision to lower the free shipping threshold still working through. Buyers responded by purchasing more often and in smaller baskets. And that means less revenue per shipment. We expected that and the engagement numbers say it is doing what we wanted. The second is capacity. We added almost 20% to our fulfillment square meters quarter-on-quarter ahead of peak. That cost lands before the volume does. A pattern we have seen many times since we started operating fulfillment almost 10 years ago. This decision reflects our strong momentum and our confidence in future growth across the region.
6 | The other two reasons are higher energy prices driving higher transportation costs and higher temporary recruitment costs due to the expansion of their shipping network.
The third is higher energy prices, which raised transportation costs. The fourth is temporary recruitment costs related to the expansion of our shipping network, which are booked in G&A. The first 2 are strategic choices investment in a stronger value proposition that builds online buying habits and investment in capacity to support the growth we see ahead. The third is outside our control, and we manage around it through pricing and efficiency. The fourth is temporary. While shipping compressed our margins in Q3, we're pleased that our network continues to become more efficient due to scale.
7 | Brazil's cost per shipment continues to decline 14% in aggregate since they started lowering the free shipping threshold.
Specifically in Brazil, despite the headwinds from new capacity and higher energy prices, cost per shipment on an FX-neutral basis declined 5% year-on-year and 14% since before we lowered the free shipping threshold. And in September, free shipments in the BRL 19 to BRL 79 range were variable contribution positive for the first time.
8 | Announced in September to expand the free shipping program to Argentina as well, and that has increased the number of loyalty members.
We announced recently this quarter in September, expansion of our free shipping program in Argentina, mostly to our minimized users. So that could be an area of investment, but similar to what we have done in Brazil. So I would say that there will not be a significant deviation to what you have seen.
We recently announced an improvement in Argentina, where we expanded the free shipping offering for our loyalty programs, loyalty members, and that also resulted in increased number of members.
9 | MercadoLibre's loyalty program helps to provide benefits on both sides of the ecosystem with MercadoLibre and Mercado Pago. And when users operate on both sides, they tend to buy more and transact more, and are more profitable.
And I think if you step back and you look at our loyalty program, the big difference that we have is the ability -- because we operate in an ecosystem, the ability to provide benefits on both sides of the ecosystem. So you get -- if you remember, of the loyalty program, you get faster and free shipping, but also you get better remuneration on your deposits, better interest rates on some of your loans and better offers in your marketplace and so on. So that's the critical competitive advantage that we have. And as we mentioned in the letter, when we look at users that operate on both sides of the ecosystem, what we call them ecosystem users, those are a lot more engaged with our platform. They tend to buy more on MercadoLibre to bring more money to the Mercado Pago platform, and they are a lot more profitable to us.
10 | The faster the speed, the higher the conversion rates. Want to use fast delivery to address the quick delivery segment, and want to do so without adding incremental infrastructure.
I think we have proven over and over that the better the speed, the better the conversion rates in our apps. Particularly when thinking about e-commerce speed at most matters more for some purchases than others when someone needs something now such as medicine and essential gift people have historically gone to a local store in order to get those items. Fast delivery is the lever that we think can help us tackling that market segment, and we see proximity as a layer within our marketplace for items where buyers expect that speed. And we are building that offering initially based on our existing capabilities, Flex, our marketplace, payments, minimize and the network of merchants and that's basically what we are testing with aura, shipments from the seller doorstep into the buyer using our cloud of drivers without committing to any incremental infrastructure.
11 | S&M rose 40bps QoQ due to higher investment in the Brazil affiliate program via social media. Orders grew 240% and reached 12m affiliates. Affiliate spending will be down, up, or down accordingly.
The second source of margin compression was sales and marketing, which rose 40bps sequentially to 11.6% of net revenue, still within our range of recent years. We calibrate the spend quarter-by-quarter and in Q3, we decided to invest more in our affiliate program in Brazil to strengthen our presence on social media. Orders through the channel grew 240% YoY. consumers increasingly discover and buy products through creators and social media. In Brazil, more than 40% of social media users say finding products to buy is 1 of their main reasons for using these platforms. and we expect social commerce to keep gaining relevance across Latin America. Since we started investing in affiliates last year, our network has grown to more than 12 million affiliates across the region. As more sellers and brands co-fund campaigns, we see a path to better economics for the program over time. Based on performance, we calibrate affiliate spending, dialing it up or down as opportunities evolve across markets.
12 | MELI sees competition coming from other social players that are focused on low-ticket items for certain categories. Building up their own social capabilities that extend beyond affiliates, live clips, and videos would help to enable them to continue competing and gaining market share in LATAM.
Clearly, we see other social players growing in the region, they are mostly focused on low ticket items for certain categories. Our value proposition is a bit broader across categories, across price ranges. But on top of that, we have been building our own social capabilities for the last 2 years, and that's not only affiliates, it's also live also clips and videos within our Infinite role and so on. And we are sure that us combining those social capabilities with the assets that I was referring to before in terms of brand in terms of selection, pricing, financing and shipping, put us in a unique position in order to capture the opportunity in commerce in LatAm, which combined with our ability to deploy our ecosystem in financial services. Really gives us an edge to continue competing and continue gaining market share across the region.
13 | MELI saw good returns on AI. Included an LLM on the search algo and drove higher conversion and click-through rates, where the incremental revenues sufficiently offset the cost of the models.
There are certain other initiatives that we mentioned on the latter. We can see the exact return on investment. For instance, we included an LLM on the search algorithm we can see through the incremental conversion and the click-through rate that we're seeing in those such results, we can see that the costs of the models are more than compensated by the incremental revenues that we're generating.
14 | MELI adopting a similar stance on agentic commerce as Amazon, Not providing inventory to any external platform and to build the best agentic experience inside MELI instead. Results are early but promising.
We clearly see agentic shopping as an opportunity to accelerate the structural shift from off-line retail into online retail. But specifically, the way we're thinking about this is not necessarily by integrating ourselves to third parties, right? So we continue to look at what's globally happening, trying to learn, and we're always ready to get new things and adapt. But for now, we have decided not to provide our inventory to any external platform. Our priority is still to build the best agentic experience inside Mercadolibre, taking advantage of the 27 years of first-party data that we have our unique combination of selection, pricing, logistics, financing, loyalty and so on.
So e-commerce is much more than just search and find trust is built further down the funnel through all the key variables that I was just mentioning, and that's exactly what we excel at, right? So we think that we can combine our strength with an agenetic experience within MercadoLibre. And with that, we believe that we will be able to sustain the high levels of direct traffic to our app or our properties through that assets that we are building. Today, our own agent is already available to a small portion of our user base in our 3 largest markets. Results are early, but promising -- it's too early to share. I'm sure we will do so in the future. But our Agentic experience is now a reality, and it's not just an idea.
15 | The utilization of build-up fulfillment capacity will occur in a step-wise function over time, and with high utilization, unit economics will improve.
In terms of the speed at which that capacity fills up, it depends. Obviously, there will be a step-up function in Q4. But then over time, we will continue to fill up and that obviously helps in terms of unit economics. But as you know, we'll continue to invest in new facilities throughout the year, maybe not at the pace that we're growing in Q3 because of peak season. But every quarter, we do increase capacity to keep up with the growth of the market. remember, we're growing in Brazil, north of 40% items shipped for the past 5 quarters. So if you can imagine that, that requires a lot of capacity to be put into place. But over time, each new capacity as it fills up, obviously improves unit economics, but then you have new ones coming into place in the following quarters.
16 | MELI has accepted a lower margin profile in the near term to invest ahead of the large opportunity. Users are buying more often, transacting, and saving more. They are gaining market share in every major market in both commerce and fintech. Believe that this will maximize long-term cash flow and shareholder value.
high-level strategic view on margin trajectory. I think for the last 18 months, we've said the same thing in every 1 of these calls. We're investing because the opportunity in front of us is large. And because deeper engagement is what builds a durable leadership position in this market. We have accepted a lower margin to do that. And I think we've been open on that regard. And our investments are working, which is a very important thing. Users are buying more often transacting and saving more with MercadoPago, and we are gaining market share in every major market in both commerce and fintech. We are being disciplined about it. We are investing only where we see the economics work and adjusting where they don't work. We're also very mindful of risk, which you can see in the evolution of our NPLs, which are close to record lows in every single country and product and the most engaged user base at scale and a deeper ecosystem penetration is what builds earning power over time, and this is the approach we believe will maximize long-term cash flow and shareholder value.
17 | MercadoLibre continues to gain market share in both commerce and in fintech, and they are convinced that their strategy is the best way to generate shareholder returns in the long run.
We continue to gain market share. We continue to bring in more customers and frequency and engagement with our platforms are reaching new levels Mercado Libre is extending its leadership as the go-to destination for shopping in Latin America. MarcadoPago is getting closer to its objective of becoming the regional largest digital financial services provider in the region and the opportunity ahead of us is huge in commerce and in fintech, and we are convinced that our strategy is the best way to generate shareholder returns in the long run. We continue to be disciplined. We continue to be mindful of risk, and we continue to be bold as well.
➡️ Key takeaways for MercadoLibre
MELI continues to grow as LATAM’s dominant e-commerce and fintech platform with a long growth runway with still low penetration. Unsurprisingly, the market in the near term often does not like companies who reinvest heavily and profitability falls. The difference is that the reinvestment is already showing up in strong growth and the underlying profitable unit economics are there, all MELI needs is time to grow and scale each opportunity. Confident in management taking the long-term to grow the business rather than to manage short-term profitability which is what we are not interested in.


Datadog $DDOG 3Q26 Earnings
- Rev $1.2b +35% ↗️🟢
- GP $960m +35% ↗️🟢 margin 80.2% +11 bps ✅
- NG EBIT $334m +61% ↗️🟢 margin 27.9% +451 bps ✅
- EBIT $75m ⤴️🟢 margin 6.2% +690 bps ✅
- NG Net Inc $304m +54% ↗️🟢 margin 25.4% +313 bps ✅
- Net Inc $118m +249% ⤴️🟢 margin 9.9% +606 bps ✅
- OCF $290m +15% ↗️🟢 margin 24.2% -417 bps ↘️🔴
- FCF $251m +17% ↗️🟢 margin 20.9% -322 bps ↘️🔴
Biz Metrics
- Cust >$100k ARR 4,860 (91% of total ARR) +20% ↗️🟢
- Total Cust 33,500 +5% ↗️🟡
- Product adoption: 2+ 86%, 4+ 61%. 6+ 41%, 8+ 26%, 10+ 16% ↗️🟢
- TTM gross retention 95-98%, net retention low 122%+
- Billings $1.2b +30% ↗️🟢
- RPO $3.9n +38% ↗️🟢
4Q26 Mgmt Guide
- Rev $1.2b +26% ↗️🟢
- NG EBIT $290m +8% ↗️🟡 margin 24.2% -398 bps ↘️🔴
- NG Net Inc $269m +24% ↗️🟢 margin 22.4% -39 bps ↘️🔴
FY26 Mgmt Guide
- Rev $4.525b +32% ↗️🟢 (raised from $4.47b)
- NG EBIT $1.105b ↗️🟢 (raised from $1.03b)
- NG Net Inc $1.031b ↗️🟢 (raised from $955m)
LT Mgmt Guide
- EBIT Margin 25%+
1 | Strong revenue growth was driven by AI customers. Revenue growth from non-AI customers accelerated for the fifth consecutive quarter and was in the high 20s%. Continue to see overall healthy demand.
I am pleased to say that we executed a strong Q3. We saw strength across our business, including across our product lines and across our diverse customer base. Revenue growth from our non-AI customers accelerated for the fifth straight quarter and was in the high 20s percent year-over-year, up about 1 percentage point from last quarter and up from about 20% in the year ago quarter. Additionally, our AI customer cohort remains a strong growth driver. This cohort continued to grow and diversify, both in the number of customers we serve and in the scale of those customers. Overall, we continue to see healthy demand as customers from the most techforward startups to the largest enterprises in the world are building with AI and with modern technologies, which we believe is fueling expanded adoption of the cloud and of the Datadog platform.
2 | The largest customer reduced their usage in Q3 while still remaining above their minimum commitment Q4 revenue growth is conservative and implies minimums. Excluding the largest customer, revenue growth accelerated again, and in Q4 would be in the low 30% range.
And excluding our largest customer, revenue growth accelerated again. As we communicated in August, our largest customer reduced their usage in the third quarter, while their usage remained above their minimum commitment.
Regarding our largest customer, our Q4 guidance contemplates their revenue at their minimum commitment…Excluding our largest customer, Q4 revenue growth implied in our guidance is in the low to mid-30s percent range.
3 | Assuming the minimum commitment spent by the largest customer in Q4, as they are unable to control that, because it is usage-based. But if the customer does spend more than that, then Datadog would have a beat in Q4.
So in terms of the largest customer, I think as we said, the customer renewed -- the customer -- we decided to put only the commitment, the minimum commitment. So the customer in Q3 spent substantially above the minimum commitment. So one thing that is very important in the sequentials is what happens there. We don't control that. The customer can't go below the minimum commitment, but can be various degrees above the minimum commitment. So that is one factor that we -- so essentially, one thing that will create less of a sequential guidance or actual would be that, that number stabilizes and isn't running above the minimum commitment.
And in Q4, we've been explicit and said minimum commitment. It is true that if they spend more than that, that would be implicit beat mathematically, yes, yes
4 | Customers are renewing earlier at larger discounts, same volume at lower prices, which is creating a bit of near-term "softness" in revenue growth. Long-term trajectory remains intact, Because these renewals are at higher levels than the previous commit, and despite volume discounts, these commits are overall higher.
There's something that is new that we have, some of these companies are scaling incredibly fast to a level that we've never seen in the industry or any industry really before, which creates new dynamics. This is why we can be a bit surprised when we see customers renew early just a few quarters into there -- starting to add up the product. In general, though, we're getting a larger number of these customers like the AI native cohort is broadening. We have many more customers, many more large customers into that cohort.
But I think it's important to clarify, these are renewals, but they are at higher levels than their previous commit, which is how they're getting the volume discounts. But we are renewing these customers at higher commits.
5 | Datadog is about doing right by and for their customers, consolidating what they are using, and having more of their product cover more and support more of their customers. Continue to feel good about the long-term growth.
We also do more things for our customers. We have consolidated a lot of what they were using. We have more products to cover more of the surface area.
Look, we are a usage-based model and when we deal with fast growth customers, these customers themselves don't know exactly how they're going to grow over the next few months and what part of their business and how their consumption is going to change. So we happily work with them and make sure that we support their growth and we do everything that's right. The only time we think about it in difficult terms is when we prepare for these calls, we have to figure out, okay, so what part can we communicate, what part do we know, what part do we not know. But overall, these are all great news, great customers, great growth, a great adoption, amazing trends that are underpinning the industry as a whole. So we feel very good about it….. In terms of what becomes the dominant monetization, it's hard to tell, and we don't really care. Again, we're fully usage-based. So as long as we get more usage, deliver more value, we'll be fine.
6 | Datadog continues to lend larger and grow faster with new logos, and that is contributing to strong revenue growth.
And we continue to land larger and grow faster with new logos, contributing more to revenue growth. The portion of our year-over-year revenue growth that relates to new customers was about 30% in Q3, up from 25% in the year ago quarter.
7 | Retention remains strong and stable: gross retention in the mid to high 90% and net retention in the low 120%.
And now regarding our retention metrics. Our trailing 12-month net revenue retention percentage was in the low 120s percent similar to last quarter, and churn remains low, with gross retention stable -- gross revenue retention stable in the mid- to high 90s. We believe this metric highlights the mission-critical nature of our platform for our customers.
8 | Infrastructure monitoring exceeded $2bn in ARR, growing at 35%.
One milestone we are very proud of, our Infrastructure Monitoring suite of products now exceeds $2bn in ARR, growing in the mid-30s percent YoY. Infrastructure Monitoring was the first product we brought to market more than 10 years ago. Today, our customers rely on Datadog for visibility across their environments, including cloud infrastructure, on-prem servers, containers, serverless applications and GPU fleets.
9 | Datadog is seeing growing demand for agent observability, off a small base.
So we see growing demand for Agent Observability. And what -- so there was always interesting demand from the AI natives et cetera. But what's most interesting here is the non-AI natives are consuming more and more. And -- because they're getting deeper into AI, we see real demand, real volumes and really exciting -- really exciting pipeline for products actually. So we think that this is not crossing the chasm, so to speak, and that's exciting for this product, even though we didn't mention any hard numbers today on that.
10 | Datadog is just getting started. While they are the market share leader in global observability, their market share still remains in the teens. Long growth runway.
And while we're thrilled to reach this milestone, we still feel that we're just getting started. According to industry analysts, we are the market share leader in global observability, but with a percentage market share still in the teens.
11 | Flagship agent Bits AI is the fastest-adopted Datadog product in history. Bits testing became GA in October.
First off, our flagship agent, Bits AI, is off to a very strong start. Since we launched Bits, it has become the fastest adopted product in our history. And in October, Bits Testing became generally available. With a single click, it discovers the critical user flow in an application and generates tests to cover them. Meanwhile, our AI research team is hard at work pushing the boundaries of what Bits and our platform can do.
12 | Introduced Scout, their own reasoning model specifically optimized for SRE tasks. Performs on par or even better than frontier models at a fraction of the inference cost
Last month, we introduced Scout, our own reasoning model specifically optimized for SRE tasks. Scout was built using our in-house distributed reinforcement learning infrastructure and now powers our Bits Investigations. This is exciting for 2 reasons. First, it performs on par or even better than frontier models on alert investigations at a fraction of the inference cost.
13 | AI training was initially done exclusively by the Frontier Labs, but now there is an increasingly whole category of companies below that (including Datadog) that are starting to do their own training.
If you look a year or 2 years ago, basically nobody was doing training. It was only a few frontier labs who were doing their own training and nobody else was. Now we see an order of magnitude more large-ish labs or new labs that are doing training at a large scale. And then there's another whole category of companies below that, that are starting to do their own, including us. We started doing training at a pretty decent scale, and we showed some of the results, we showed some of the results on the call as well.
14 | GPU monitoring is up 8x, and agent observability is up 9x.
On performance, we covered the whole AI stack from compute all the way to agents. GPU monitoring now goes beyond hardware reliability with new capabilities that help customers maximize fleet utilization, increase training throughput and serve inference at a lower cost per request. The number of GPU devices we monitor is up by a factor of 8 so far this year, and some of our frontier lab customers are working with us as design partners on these capabilities. Going up the stack, Agent Observability helps teams monitor and evaluate their agents in production, including the quality of their responses, latency and token usage. The number of spans sent to Agent Observability is now up by a factor of 9 this year.
15 | Observability is now available in Anthropic's and OpenAI's marketplace.
We've also made Agent Observability available in the Anthropic marketplace, and we are a launch partner to OpenAI's new enterprise marketplace as well. So now customers can buy our products directly through the frontier labs they already work with.
16 | Datadog Clock Cost Management, or CCM, is rapidly being adopted by customers to track AI cost. Customers up 11x.
Beyond the 3 major clouds, AI providers are now the largest category of spend our customers monitor in Datadog Cloud Cost Management, or CCM. Now with AI cost in CCM, customers can see which teams, models and agents drive their AI spend, can govern that spend with budgets, forecasts and anomaly alerts. More than 1/3 of our CCM customers now track AI costs. The number of customers doing so is up more than 11x. Moving up the stack again. Our agent console adds to our CCM data and shows exactly which agents are actually used by whom, for what tasks, at what cost and most importantly, with what outcomes.
17 | Databricks remains the leader in observability and AI ops.
As we continue to innovate across AI for Datadog and Datadog for AI, independent research is taking note. Forrester named Datadog a leader in its 2026 Forrester Wave for AIOps Platforms. And Gartner's August 2026 AI Vendor Race report called Datadog the company to beat for observability platform. We believe this validates our leadership in observability as well as our ability to help customers manage complexity in the edge of AI.
18 | Datadog had numerous customer wins during the quarter, Most notable is an eight-figure expansion deal with the AI division of one of the world's largest tech companies, 3X their annual commitment.
we signed a 7-figure annualized expansion with a leading software company, more than doubling their annual commitment
we landed a 5-year 7-figure annualized deal with the U.S. Federal Defense Agency.
we landed a 7-figure annualized deal with a leading home healthcare software company.
we signed a 7-figure annualized expansion with a leading online entertainment company.
we landed a 6-figure annualized deal with a top European AI lab
we signed a 7-figure annualized expansion for an 8 figure annualized deal with a leading AI coding company.
Finally, we signed an 8-figure annualized expansion with the AI division of one of the world's largest technology companies, which nearly tripled their annual commitment. Just 2 quarters after we landed them, they are scaling Datadog across a large number of AI training workloads.
19 | AI continues to be a secular tailwind and large growth driver for Datadog as AI workloads move into production to drive more cloud consumption and usage of Datadog.
There is no change to our overall view that digital transformation and cloud migration are longterm growth drivers for our business. And AI is another large growth driver for us today as AI workloads move into production to drive more cloud consumption and more usage of the Datadog platform, and we see that today across our business.
20 | All of the top 15 AI leaders are Datadog customers, serving 850 AI customers.
All 15 of the top 15 AI leaders are our customers. And more broadly, we now serve over 850 AI customers, up from about 750 last quarter. And across our broader customer base, we also see AI activity growing substantially. About 1/3 of our customers now use one or more of our AI products, including 3/4 of our $100,000-plus customers with many of these customers still just getting started with these products, leaving a large opportunity for future expansion. And we continue to see rapid growth in agentic activity with a number of MCP tool calls up by a factor of 50 so far this year.
➡️ Final Takeaways Datadog $DDOG:
We had initiated a starter position last quarter and would look to build it over time as the company's strength continues on occasional dips. Datadog remains the top dog in observability, and is benefiting from the secular tailwind to cloud and AI that is driving increasing complexity and costs that requires more and more of Datadog’s products to save money, Management chose to be more conservative around the softening of usage spending of their largest customer. More importantly, that 9-figure largest customer just renewed and is not going anywhere. Despite that, FY26 revenue guide is again raised. While the market might not like the near-term revenue growth “softness”, we are happy to take advantage of the opportunities that Mr. Market will give.


1
15
2,213
Cloud Spend as % of Global IT Spend is <15%, and there's still a long way to go to continue growing.

11
1,566

Shopify $SHOP 3Q26 Earnings
- Rev $3.7b +32% ↗️🟢
- GP $1.8b +28% ↗️🟢 margin 47.6% -132 bps ↘️🔴
- EBIT $584m +70% ⤴️🟢 margin 15.6% +355 bps ✅
- NG Net Inc $638m +45% ↗️🟢 margin 17.0% +154 bps ✅
- Net Inc $462m +75% ⤴️🟢 margin 12.3% +306 bps ✅
- OCF $818m +59% ↗️🟢 margin 21.9% +382 bps ✅
- FCF $816m +61% ↗️🟢 margin 21.8% +398 bps ✅
Biz Metrics
- GMV $119.1b +29% ↗️🟢
- GMV (NA) +28% ↗️🟢
- GMV (Europe) +33% ↗️🟢
- GMV (International) +32%
- GMV (B2B) +74% ↗️🚀
- GMV (Off-line) +30% ↗️🟢
- GMV (Shop Pay) +50% ↗️🟢
- GPV $81b +35% ↗️🟢
- GPV/GMV 68% +300bps ↗️🟢
- MRR $230m +19% ↗️🟢
Subscription solutions
- Rev $836m +20% ↗️🟢
- Rev - Apps, Themes, etc $167m +33% ↗️🟢
- Rev - Shopify Plus $234m +20% ↗️🟢
- Rev - Shopify Standard $435m +15% ↗️🟢
- GP $661m +15.8% ↗️🟢 margin 79.1% -262 bps ↘️🔴
Merchant solutions
- Rev $2.9b +35% ↗️🟢
- GP $1.1b +36.6% ↗️🟢 margin 38.5% +31 bps ✅
4Q26 Mgmt Guide
- Rev +32% (low 30s)
- Gross Profit +27% (high 20s)
- FCF margin 19% (similar to 4Q25)
1 | Q3 was strong. GMV was up 30%, and revenue was up 32%. Consistent, durable growth.
Q3 was another signature Shopify quarter. GMV was up 29.5% to $119 billion. Revenue was up 32% to $3.7 billion, and our free cash flow margin was 22%. And we saw more of the biggest names in retail from Balmain to MAC to Clinique to Lululemon all go live on Shopify. So we delivered exactly what we said we would, consistent, durable growth yet again.
2 | Growth was broad-based across merchant sizes and geographies and evenly split amongst new and same-store sales. Growth in the largest $2-25 million cohort contributed the most incremental GMV.
The trends across all vantage points are very consistent with recent quarters. Growth was broad-based across merchant sizes and geographies and remained evenly split among new and same-store sales, starting with merchant size. The $2 million to $25 million cohort contributed the most incremental GMV and is the largest slice. Growth in this band was mostly from existing shops growing into the size. The $25 million and greater band is the fastest growing, albeit off of a smaller base.
3 | Shopify's U.S. and Europe merchants are growing faster than the market, allowing Shopify to capture even more e-commerce market share in both geographies.
First, we continue to power a larger share of commerce overall. And second, we are expanding commerce itself by helping more merchants survive and thrive, helping them discover new buyers and lowering barriers to entrepreneurship. To my first point, the quality and capabilities of our solutions help our merchants drive a disproportionate share of global commerce growth. Over the last 3 years, our U.S. merchants online sales grew at a compound annual growth rate of 23% compared to 8% for U.S. e-commerce overall.
In Europe, we saw a similar pattern. Our merchants grew online GMV at a compound annual growth rate of 37% compared to a market growth of 8%, doubling their share of e-commerce in just 3 years. And these trends have accelerated. Three years ago, Shopify merchants drove nearly 1/5 of incremental e-commerce sales in the U.S. and nearly 1/4 in Europe. Since the start of 2025, they now capture nearly half in the U.S. and more than 40% in Europe.
4 | Subscription solution revenues grew 20%, led by standard plan subscriptions.
Subscription Solutions revenue grew 20% led by standard plan subscriptions. Equivalent size increases in Plus subscriptions and variable platform fees rounded out the growth in subscription solutions with the variable platform fees growth balance between more merchants exceeding their minimum volume thresholds and continued sales growth among merchants already above them. Q3 MRR grew 19% YoY. Plus MRR represented 34% of MRR, growing 18% YoY. As a reminder, MRR comparatively underrepresents the impact we're seeing from larger GMV merchants.
5 | This is truly the greatest time in history to be a founder, and there's opportunity everywhere. The more complex it is, the more value Shopify can provide and help with.
This is truly the greatest time in history to be a founder. There is opportunity everywhere. And the more opportunity there is, the more complexity there is. And the more complexity there is, the more our value goes up. The value of one unified commerce operating system connected to every surface area that customers want to shop on and every tool that teams want to build with. That is the real story behind this moment. For Shopify, that is what matters most
6 | Shopify is working on the agentic future as well as improving its capabilities today for its existing merchants.
Shopify is uncommonly good at operating in 2 realities at the same time. The agentic future we're building towards and that everyone on this call is excited about and the current reality for most of our merchants today. And here's what that looks like in practice. Since our last earnings call, personal agents hit the mainstream, Muse, Instinct, Claude Duet, Grok Bot, all partner with Shopify. So our merchants checkouts are supported and buyers can use Shop Pay as their wallet.
And we're powering product discovery across all major AI channels from ChatGPT to Microsoft to Muse. These are the things that could drive real merchant success in the future. At the same time, we also rolled out an incredible range of new products and features across Shopify, growing our presence internationally, strengthening our offline business and making our online store builder even more powerful. Those are the things that drive merchant success today. And importantly, we balance both of these realities while running an exceptionally strong business.
7 | Shopify saw explosive growth in agentic shopping, AI traffic up 2.6x and orders up 3.3x. Shopify is the e-commerce infrastructure behind personal agents, with Shopify Catalog is powering discovery, rather than web scraping.
I think what you're seeing is that every week or 2, you're seeing a new agent or a new personal agent show up. And hopefully, you're noticing that Shopify is the commerce infrastructure behind all of them, we're partnering with all of them.
Volume again is small, but traffic we saw in the last quarter was 2.6x year-on-year. Orders were up 3.3x and then Shopify Catalog is powering discovery in almost every single major AI channel. The other thing that's really cool is conversion from catalog is actually 2x the rate of general AI search sort of what people call scraping. Maybe the last point I'll sort of end on here is that we are seeing that these AI channels are really rewarding specificity, which is really, really important for the long tail of commerce, which is most of our merchant base.
8 | AI channels are now surfacing highly specific products that fit specific customers with a specific need. AI is no longer just a discovery channel. More nuanced and niche products are getting found on Shopify.
But what's even more interesting is what products are being surfaced and it's not the obvious categories. AI channels are surfacing highly specific products that fit specific customers with a specific need. Here is where Shopify Catalog comes in. Catalog powered searches are converting at 2x the rate of general AI search. That is because catalog is quite literally written for agents…So as we said, 74% of AI attributed purchases in Q3 were from outside our top 100 categories. So we're really seeing that these more nuanced niche products are getting found and that -- we have a ton of those on Shopify.
9 | Shopify can turn one billion product pages into a structured dataset that an agent can read and understand.
It turns over 1 billion product pages into structured data set translating details like size, color and material into numerical values that an agent can read and understand. And it is not just a linear product feed, it is live, cross-merchant map for what is available across all of Shopify, with current pricing and inventory that helps AI channels make more accurate recommendations and that makes it insanely powerful. And here's what is really exciting. AI is no longer just Discovery channel.
10 | Shopify's ShopPay is open agnostic and works with the different AI agents.
Shoppers can now use Shop Pay as their chosen wallet for any merchant, no extra setup required, it just works. For merchants, this means reach, a huge new pool of customers with 0 lift for them. For buyers, this means trust, a familiar way to buy in an unfamiliar channel. And for developers and AI companies, this means access to world-class infrastructure. Now all the tools they need to build a shopping experience, including catalog, checkout and the shop network are in 1 place. We call it shop.dev, one-stop all commerce complexity handled.
And that is what Shopify was built for. We have always been an open ecosystem, and that now extends to agentic tools. We have connectors with agents like Muse, ChatGPT, Claude, Google Gemini, giving merchants complete optionality over how and where they run their business.
11 | Shopify's Canvas allows merchants to build a fully bespoke online store simply by describing what they want to Sidekick. No coding, no design expertise required. Merchants are launching stores that are more personalized and doing it faster.
But as more people use more tools to turn ideas into businesses, Shopify is part of that journey right from the start. Now talking about turning ideas into businesses. This quarter, we launched the biggest update to our online store builder in our 20-year history. It's called Canvas. Canvas lets merchants build a fully bespoke online store simply by describing what they want to Sidekick, no coding or design expertise required.
Now the store you can picture is the store you can build. It's only been live for about a month, but here is what we are seeing. Merchants are launching stores that are more personalized and they're doing it 20% faster.
12 | Sidekick is the most widely used tool for Shopify's merchants. Usage continues to grow rapidly, with daily active merchants up 3.7x and daily sessions up 4.2x. More importantly, Sidekick created two-thirds of all Shopify flows.
Now I want to talk a bit more about Sidekick, which is still overwhelmingly the most widely used tool for our merchants to run their business. And usage continues to grow at an even faster clip in Q3. Daily active merchants are up 3.7x year-over-year and daily sessions are up 4.2x, but there's an even more important story here than adoption. And it is just how capable Sidekick is becoming. In Q3, Sidekick created around 2/3 of all Shopify flows.
13 | Sidekick pressured margins with higher hosting costs and AI compute, but the benefits created and efficiency gains have offset higher costs.
On a year-over-year basis, Subscription Solutions gross margins compressed primarily from incremental AI spend on Sidekick, partially offset by efficiencies and support. On a sequential basis, our margin declined mainly due to higher hosting costs as we added capacity ahead of BFCM and some enhancements to our storefront resiliency and global search capabilities. Although Sidekick drove year-over-year pressure on margins, on a sequential basis, we've been able to offset that pressure with efficiencies we've built into how we deliver Sidekick. We've made improvements in model selection, distillation and caching to support more usage at a lower cost. From Q2 to Q3, merchant conversations increased 14% while cost per conversation declined 28%, and total Sidekick cost fell 18%.
14 | Sidekick is significantly helping merchants to achieve more and to do better.
The cost is only one part of the Sidekick story. The more important measure is what merchants accomplish with it. That is our focus. But that, of course, also translates into our financials. Sidekick attracts more merchants to Shopify, which manifests in the financials and subscription solutions, and it propels more merchant success, which materializes in merchant solutions.
Last quarter, we shared that using Sidekick's onboarding guide results in an 8% lift in merchants reaching 5 sales within 15 days. This quarter, we can demonstrate benefits beyond that. After their first sales, Sidekick offers merchants a dynamic conversion guide to prompt additional conversion tactics in those critical early months as a business is launching. Examples include help with answering customers' questions reaching out to customers with abandoned carts and more. This resulted in a 3% lift in merchants reaching their next 5 orders in 60 days after using the guide, incrementally small, but off large cohorts. That benefit makes a difference and shows the value Sidekick can bring in targeted, proactive merchant communication
15 | Lululemon selected ShopPay for their North American online store.
And it is also why we continue to see incredible brands bringing Shop Pay into their ecosystem, including one of my favorite brands, as I mentioned earlier, Lululemon, who just selected Shop Pay for their North American online store. And as history has proven, once we have a toe in the door, the upside is clear.
16 | Shop app GMV more than doubled in Q3. Continue to invest to make it even better. Shop app has become the number one shopping app in the Japan App Store just after 1 week.
Now speaking of Shop, GMV in Q3 more than doubled year-on-year. This is shops network effect at play, more shop buyers, more seamless shopping experiences, more benefits for merchants. And we continue to invest to make the experience even better.
We also launched a localized version of the Shop app in Japan, which became the #1 shopping app in the Japan app store, the week after full rollout, which I think is really cool.
17 | Shopify Campaigns continue to be open and agnostic and only pay when a sale happens. YTD orders having more than 2X.
The last point I'll make on growth is about discovery. As I talked about at the top of the call, shopping is spreading across more channels, more opportunity, more complexity, more ways for Shopify to help our merchants. Shopify Campaigns offers a risk-free way to reach customers across 10 channels from shop to Instagram to ChatGPT. That means full optionality for merchants. We're not biased towards any 1 particular channel and they only pay when a sale happens. And the momentum there is really building. Year-to-date orders through Shop Campaigns more than doubled year-over-year, accelerating in the third quarter.
18 | Offline GMV grew 30%. Large, complex, multi-location merchants continue to be the fastest-growing segment.
Finally, looking by channel, beyond just online. Off-line GMV grew 30% YoY, consistent with last quarter's constant currency growth. Large, complex multi-location merchants continue to be our fastest-growing segment with our total locations on Shopify up 52% YoY. Importantly, we are having greater success expanding our point-of-sale merchant base beyond just those merchants that started with us online and then adopted our off-line solutions. In Q3, 55% of merchants that added our point-of-sale were new to Shopify. And of those already selling, half are selling only in-store.
19 | B2B was especially strong, growing 74%.
B2B GMV grew 74%. We consider B2B a significant opportunity to expand the verticals that Shopify addresses. Interestingly, B2B GMV is much more distributed by industry vertical than online, and the fastest-growing verticals include home improvement and hardware, electronics and business supplies for verticals such as retail stores, laboratories and medical, food service and agriculture.
20 | Merchant Solutions revenue grew 35%, driven by strong GMV growth and payments penetration.
Merchant Solutions revenue grew 35%, driven substantially by the strength in GMV and increased payments penetration….Payments penetration surpassed 68%, up 3 points year-over-year, and Shop Pay GMV grew 50% year-over-year. We also saw growth in the broader set of services merchants use on Shopify, most notably this quarter in advertising.
21 | Shopify's connected unifying OS is the mode. It allows merchants to do advertising, sell their products, and handle payments, all on one platform.
one thing becomes very clear. Our simple connected unifying operating system is the moat. No one merchant can manage the increasing volume of surface areas to build and sell across and nor should they. And that is true for merchants of all sizes, including larger merchants. These businesses want their online stores and their physical locations to work together. They want their team spending more time improving the customer experience and less time maintaining the technology behind it. And as AI creates new ways to shop, they want a platform that keeps them ready for what comes next.
22 | Shopify has a breadth of growth levers and not just on one particular segment. Shopify is ultimately a growth company that is able to benefit from the growth of multiple levers, which speaks to the strong durability of its business model.
One of the things that I think is most remarkable but the business model here is that our model has this breadth of growth levers it is not a single bet on one growth curve. We have sort of this portfolio of commerce and payments, international agentic enterprise. And in any given quarter, some will be stronger than the others. But the durability, I think, of the story is the compounding strength across that set. International GMV was up 32%.
B2B saw 74% growth, off-line GMV was up 30%, we crossed the $200 billion mark for off-line GMV. And then you have enterprise as well. So what we try to think about is sort of this portfolio of bets and making sure that whatever is to come, we're front and center, but also making sure that we're able to -- Shopify ultimately is a growth company, and we want to stay focused on driving merchants growth in turn that fuels our growth. But there's never necessarily 1 particular place we put our eggs in because we have this portfolio of opportunities. And I think that actually talks to the durability of this business model.
➡️ Final Takeaways Shopify $SHOP:
Shopify continues to do well in becoming the OS for commerce across all businesses and in the next phase of ecommerce, agentic commerce with UCP. Partnerships and large brands/enterprise, offline / POS, B2B, Cross-border, International, strategic advertising, Shop Pay, Shop App, branded checkout all doing well. That’s the beauty of Shopify, optionality. And when customers do well, Shopify does well too.


Palantir $PLTR 3Q26 Earnings
- Rev $2.3b +96% ⤴️🟢
- GP $1.9b +98% ⤴️🟢 margin 83.4% +98 bps ✅
- Adj EBITDA $1.4b +136% ⤴️🟢 margin 62.0% +1063 bps ✅
- NG EBIT $1.4b +138% ⤴️🟢 margin 61.7% +1083 bps ✅
- EBIT $1.1b +176% ⤴️🟢 margin 46.9% +1360 bps ✅
- NG Net Inc $1.1b +116% ⤴️🟢 margin 49.4% +461 bps ✅
- Net Inc $1.1b +138% ⤴️🟢 margin 49.0% +867 bps ✅
- OCF $1.2b +137% ⤴️🟢 margin 52.1% +909 bps ✅
- FCF $1.2b +139% ⤴️🟢 margin 51.7% +932 bps ✅
Revenue by Segment/Geography
- US Rev $1.9b +120% ⤴️🟢
- US Commercial Rev $1b +148% ⤴️🟢
- US Govt Rev $1b +96% ⤴️🟢
- Commercial Rev $1.2b +114% ⤴️🟢
- Govt Rev $1.2b +82% ⤴️🟢
- Int Rev $373m +25% ↗️🟢
- Int Commercial Rev $186m +23% ↗️🟢
- Int Govt Rev $197m +34% ↗️🟢
Biz Metrics
- Total Cust Count 1,090 +20% ↗️🟢
- Commercial Cust Count 904 +22% ↗️🟢
- Govt Cust Count 186 +10% ↗️🟡
- US Commercial Cust Count 686 +29% ↗️🟢
- Int Commercial Cust Count 218 +3% ➡️🟠
- TCV $2.9b +6% ↗️🟡
- US Commercial TCV $1.5b +11% ↗️🟡
- US Commercial RDV $6.5b +79% ↗️🟢
- Deals closed 212 >$1m, 107 >$5m, 64 >$10m ↗️🟢
- Average TTM Revenue of Top 20 Cust $146m +76% ↗️🟢
- Billings $2.5b +99% ⤴️🟢
- RPO $4.9b +88% ⤴️🟢
- ST RPO $2.1b +88% ⤴️🟢
- LT RPO $2.7b +88% ⤴️🟢
- Net Retention 165% ↗️🟢 (from up 157%)
- Rule of 40 @ 158 ↗️🟢 (up from 155%, 96% Rev Growth + 62% Adj EBIT Margin)
4Q26 Mgmt Guide
- Rev $2.7b +89% ⤴️🟢
- NG EBIT $1.6b +106% ⤴️🟢 margin 62.0% +524 bps ✅
FY26 Mgmt Guide (raised)
- Rev $8.5b +91% ⤴️🟢 (raised from $8.2b)
- US Commercial Rev $3.6b +143% ⤴️🟢 (raised from $3.4)
- NG EBIT $5.2b +133% ⤴️🟢 margin 61.5% +1114 bps ✅ (raised from $4.9b)
- FCF $5b +120% ⤴️🟢 margin 58.6% +786 bps ✅ (raised from $4.7b)
1 | Palantir had a blowout quarter and achieved revenue growth of +96% YoY and +20% QoQ, driven by the US commercial and government business. US commercial revenues have surpassed the US government.
We had an outstanding third quarter. We delivered our highest ever reported YoY revenue growth rate of 96% and our highest ever reported sequential revenue growth rate of 20%. Quarterly revenue crossed the $2 billion mark for the first time, and we surpassed additional $1 billion milestones in commercial revenue, government revenue and GAAP operating income. Revenue in our U.S. business accelerated yet again, growing 119% YoY and 23% QoQ. Our U.S. commercial business grew 148% YoY and accelerated to 29% growth QoQ, and our U.S. government business grew 96% YoY and 18% QoQ. Demand for our Sovereign AI offering is accelerating our U.S. commercial momentum, helping to make this our first ever quarter that U.S. commercial revenue eclipsed U.S. government revenue, a critical milestone in the history of our company.
2 | Palantir AI platform continues to dominate the U.S. markets as the only real choice for enterprises operationalizing LMS, giving them full control over their data, logic, actions, and security.
Our AI platform continues to dominate the U.S. markets as the only real choice for operationalizing LLMs while still giving customers full control over the data, logic, actions and security of their enterprise.
3 | Palantir allows companies to fine-tune open-source models with their own data, outperforming frontier models very quickly and cutting costs tremendously.
L3Harris noted that by fine-tuning open source models on its own data, a sovereign model outperformed the frontier model it had been using in less than 48 hours and cut costs by 95% in preliminary results. NVIDIA reported that by evaluating and post-training its open models, it was able to get its smallest, most efficient model to outperform its largest model by a large gap, and can now retrain that model on just a single GPU in a couple of hours, enabling them to retrain any time they have data to improve the decision intelligence. They stated, "We captured our alpha and we trained it into a model. We couldn't have started this process until we built the workflows in Palantir.
4 | Enterprise commercial customers are ramping up from single-digit deals to larger double-digit deals rapidly over a few quarters.
And our customers are choosing Palantir and our Sovereign AI to transform their organizations at a furious pace. An industrial materials company piloted a nearly $3 million engagement in Q2 2026 before converting to a $29 million ACV deal last quarter. A global athletic company converted a $1.6 million pilot that began in Q1 2026 into an approximately $21 million ACV deal last quarter. A global home appliance company converted a $1 million pilot that began in Q2 2026 into a $3 million ACV deal within the same quarter, then expanded nearly fivefold to a $15 million ACV deal in Q3 across commercial, finance and supply chain workflows. After an AgentCamp in Q2 2026, an apparel company signed a $2.5 million pilot, then last quarter, they converted to an $11.5 million ACV deal.
5 | Palantir is helping enterprises do the work that would have required hundreds of analysts and is becoming the main provider of Sovereign AI.
This is a modernization in operational form changing how safety work gets done." And noted that the work they can do now would require hundreds of analysts without Palantir. As I reflect on our results, I see the furious pace continuing unabated. I'm invigorated unlike ever before by the ambition I'm hearing from our customers and their demand for Sovereign AI, a revolution we should remember is barely 1 quarter old. As extraordinary as these results are, they are only the opening chapter of Sovereign AI.
6 | For enterprise AI, it's not about continuous model improvements, but rather having a harness for the enterprise, which is exactly what AIP does.
And this requires not a harness for the model, but something closer to a harness for the enterprise, which is exactly what AIP is. Most profoundly, the conceit that the labs have wrong is the belief that the atomic unit of the enterprise is the individual knowledge worker. It is not. The fundamental unit of the enterprise is the workflow. You can make any set of workers more productive and generate no actual ROI. For some things like coding, the knowledge worker is the workflow. So there's perfect product market fit. But for the vast majority of the enterprise, it is not. Given this, it is incredibly valuable that AIP implements enterprise workflows and is able to bring AI to it in a way that generates objective, quantifiable value.
7 | Post-training on customers' specific operational data in Ontology enables better-than-frontier performance, which they can control, protecting their alpha.
This is not about doing the same thing cheaper. It's about defining the productive work that goes beyond yesterday's frontier, and capturing and compounding the new economic value it creates, and doing so with Sovereign AI. The examples are everywhere now. It's clear that post-training on your specific operational data in Ontology enables better than frontier performance on weights you control, protecting your alpha.
Yes, it's cheaper, but the dominant variable is that more use cases can actually get to the threshold of viability for machine intelligence to generate economic value when elegantly integrated into your enterprise. And our product investments in AIP to create a closed-loop model factory are making this easy and fast.
8 | Palantir is not helping customers cut opex costs but much more on growing revenues. Palantir is the diffusion layer, not just of choice but of necessity.
That entire workflow and the elegant application of AI, software and humans runs in AIP and was implemented by Palantir and AIG. We are the diffusion layer, not just of choice, but of necessity. There's a clear pattern emerging amongst our customers who are most successful at getting value from AI. They have enormous ambition. Their goal is not something lame like OpEx reduction. It's market domination. And the opposite is true. Customers that struggle the most are narrowly focused on reducing cost. AI is a new type of intelligence. Simply trying to shoehorn it to replacing the human misses the moment completely.
9 | Palantir believes that Sovereign AI is the latest and largest tech revolution. They have signed multiple eight-figure deals in the quarter that were shorter in duration, but expect this duration and size to increase over time.
We believe Sovereign AI is the latest and largest tech revolution of our generation. We signed multiple 8-figure deals in the quarter that were shorter in duration than usual, as customers rapidly adopted initial Sovereign AI capabilities in their enterprise. It is important to remember that the Sovereign AI revolution is only 1 quarter old. As we continue to deliver value with Sovereign AI, over time, we expect both the duration and size of these contracts to increase.
10 | Revenue from strategics remains small at 400k for the quarter, less than 0.02% of overall revenue. Expect no further revenue from strategics beyond 4Q26.
Revenue from strategic commercial contracts was approximately $400,000 for the quarter, representing less than 0.02% of overall revenue. We continue to expect revenue from these contracts to be less than $500,000 in the fourth quarter, and we anticipate no further revenue from these contracts beyond the fourth quarter of this year.
11 | Palantir RPO figures are much “smaller”, as it is largely commercial, does not account for contracts less than 12 months and contractual obligations that have termination-for-convenience clauses which are frequent in government contracts.
As a reminder, RPO is primarily comprised of our commercial business as it does not take into account contracts with an initial term of less than 12 months and contractual obligations that fall beyond termination for convenience clauses, both of which are common in most of our government business.
12 | Palantir is seeing much quicker interaction, deployment, and shorter contract duration with enterprise customers. Customers can train Open Weight models in ontology. Their models become even more valuable to them, and they quickly realize the value of it, signing bigger and longer deals.
seeing on the front line in commercial is this much quicker interaction, much quicker to deployment, shorter duration of the contract, but then an ability to expand that contract dramatically. Because as soon as you go in there and you show them that you can, for example, train open-weight models in our Ontology, those models are valuable and you have beyond frontier capacity without losing the alpha, you just are hooked. What we have to do internally is figure out how to re-resource our company to focus exclusively on those people because we don't have even the bandwidth to do that. So -- but that's because, like, every single time we go into the conference, like in the past, you would be -- we go into a conference and people are like warm leads turn into hot leads.
13 | The Sovereign AI bootcamps are exploding in momentum and customer traction.
the Sovereign AI revolution, we launched this last quarter and the felt version on the ground is -- and what we're seeing at Sovereign AI boot camps when we actually show and don't tell is the momentum and the urgency of customers that get it and see it, adopting quickly, moving quickly, moving with urgency because they realize how much it matters. And we're feeling that on the ground, and we're at the very beginning of this, and we only see that continuing and expanding from here.
14 | Customers are starting to realize that the atomic unit of the enterprise is not the knowledge worker, but rather the workflows.
I think one of the conceits that the labs don't have right and that perhaps the customers who don't quite yet realize that the return is not there, is that the atomic unit of the enterprise is not the knowledge worker. You can make people more productive and generate no actual return on investment. If you're measuring the inputs, it can feel really good to see that productivity of the person. You actually -- the atomic unit is the workflow.
15 | Palantir provides enterprises with the tools to integrate their people, AI, and software to drive objective, quantifiable value against workflows. That is the value that Sovereign boot camps customers are realizing.
And having a platform like AIP, where you're already managing your supply chain or your S&OP or your key enterprise processes, the exhaust of those processes then enable you to go through the post-training loop to have a model that's better than frontier at that. We give you the tools to elegantly integrate your people, your AI and the software to actually drive objective, quantifiable value against the workflow. This is the compounding loop that the customers who are coming to us in the Sovereign Bootcamps really understand.
➡️ Key Takeaways for Palantir $PLTR:
Top dog in valuable data integration and analytics with a strong moat of data relationship/context with ontology, providing immensely high customer LTV and being able to capture some of it in return. Extremely durable and secular growth with business critical workloads. Palantir is becoming the AI harness for enterprises allowing them to training their data, improving the performance beyond frontier models, at significantly cheaper costs and faster, allowing them to retain full control and sovereignty. Strong US commercial growth continues to reaccelerate and with US government growth driving rapidly inflecting profitability. Continued strong traction with Sovereign Bootcamps and FDEs bringing continued strong actionable customer use cases and value that is reflected in its rapid strong growth and improving profitability.


