




Pinned Tweet
💊 A Doctor on Pharma Stocks (1/12)
I'm a doctor with years of experience running clinical trials. I still rarely buy pharma stocks.
Why:
🧪 ~90% of drugs in the pipeline never reach patients.
💥 One failed Phase 3 can wipe out years of value overnight.
⏰ Every blockbuster has a patent cliff. The clock starts on day one.
💰 A drug can work beautifully and still be a bad business: pricing, reimbursement, competition.
🏛️ And politics can rewrite the price. In 2025, Novo and Lilly agreed to cut US prices on their obesity drugs under pressure from Washington.
Knowing the science helps. It doesn't make the pipeline predictable.
📝 Full analysis in my Article this Saturday.
$META found a way to raise capital for its AI ambitions without giving up Zuckerberg’s control. 🧠💰
For investors, the real question isn’t how many shares exist — it’s how much value each share represents after dilution.
More shares ≠ more value. 📊

$META is splitting its stock, but the new shares don’t get a vote.
Instead of a traditional split, Meta is giving every shareholder one nonvoting Class C share for each share they own, which effectively doubles the share count. Trading is expected to start in late January 2027.
The structure lets Meta raise money for its AI buildout while CEO Mark Zuckerberg keeps control of the company.
The announcement came with record third quarter revenue of $64 billion. Meta stock rose more than 3% after the bell.

$TXN delivered a strong Q3 2026!
📈 Revenue: +28% YoY to $6.06B
💰 Operating profit: +73% to $2.87B
🚀 EPS: +77% to $2.62
💵 Quarterly FCF: $2.96B
🔥 TTM FCF margin: 40.6%
Strong earnings and impressive cash generation. 🎯
Long $TXN. NFA.

$TXN before earnings (3/3)
What the dot-com crash taught TXN shareholders.
📉 2000: the stock peaked.
💥 2002: down ~85%.
⏳ It took more than 15 years to get back to the 2000 high.
But while the price went nowhere:
💵 The dividend went from $0.09 a year (2004) to $6.08 today. Raised 23 years in a row.
🔄 Shares outstanding fell 47%. Every owner got a bigger slice.
For 15 years, that was most of the return.
That's why I don't buy $TXN for one quarter.
Results tonight. I'll post the numbers that matter 👇
Long $TXN. NFA


$TSLA Q3 earnings are in, and the numbers validate the thesis. 📊
🔴 Tesla Q3 Free Cash Flow: -$4.51B (CapEx spiked to ~$7.8B for the quarter, targeting $25B+ for the full year)
📉 Tesla Operating Income: Down to ~$721M (Operating margin compressed to 2.5%)
🏦 Tesla secured $30B in credit facilities to fund this massive AI & Robotaxi infrastructure burn.
Meanwhile, $UBER continues to generate massive +$10B in trailing FCF by partnering with 20+ AV operators without taking on balance-sheet risk or massive CapEx.
Capital efficiency wins long term.
Long $UBER. 🚕 NFA.
$TSLA reports tonight. As an $UBER shareholder, I'm watching one thing: the cost of the robotaxi race.
🚗 Tesla free cash flow last quarter: -$1.1B
🏭 Tesla capex this year: $25B+
📉 Tesla operating income: $13.7B (2022) → $4.4B (2025)
🚕 Uber free cash flow, last 12 months: $10B+
Tesla is building the robotaxi network itself, and paying for it.
Uber lets 20+ partners build the cars, and takes a cut of every ride.
Both can win. But only one of them gets paid while it waits.
Long $UBER. NFA
🚨 $TSLA Q3 EARNINGS 🚨
Tesla reports mixed Q3 results with a strong EPS and Free Cash Flow beat:
💵 Revenue: $28.05B vs $28.13B expected
💲 EPS: $0.48 vs $0.44 expected
🚗 Automotive Revenue: $20.56B vs $19.83B expected
💰 Free Cash Flow: $1.53B vs -$4.99B expected
🚨 $TSLA Q3 earnings
💵 Revenue: $28.05B vs $28.13B expected
💲EPS: $0.48 vs $0.44 expected
🚗 Automotive revenue: $20.56B vs $19.83B expected
💰 Free cash flow: $1.53B vs -$4.99B expected

🚨 $META Q3 EARNINGS BEAT 🚨
Meta delivers stronger-than-expected Q3 financial results:
💵 Revenue: $64.6B vs $63.3B expected
💰 EPS: $3.83 vs $3.57 expected
➡️ Q4 Revenue Forecast: $73B to $76B vs $73.57B expected
Zuckerberg's heavy investments in AI and ad infrastructure continue to drive growth past Wall Street estimates. 📈
🚨 $META Q3 earnings
💵 Revenue: $64.6B vs $63.3B expected
💲 EPS: $3.83 vs $3.57 expected
➡️ Q4 revenue forecast: $73B to $76B vs $73.57B expected

$META reports tonight. Last quarter told the whole story:
📈 Revenue: +28%. The ad machine is fine.
🏗️ Capex: $31B in one quarter.
💸 Free cash flow: $0.8B, down from $8.6B a year ago.
🔄 Buybacks: zero.
AI is eating the cash flow. 2026 capex guide: $130–145B.
Wall Street punished this kind of spending in 2022 too. Then it paid off.
Tonight I'm watching free cash flow, not the headlines.
Long $META
💊 A Doctor on Pharma Stocks (9/12)
LSD as an anxiety drug? It just passed Phase 3.
🧪 MindMed, now Definium ($DFTX ), is developing DT120 (formerly MM120), a pharmaceutical form of LSD.
📊 Voyage Phase 3: a single dose. Anxiety score (HAM-A) down 11.6 points vs 6.2 on placebo at week 12.
⚡ Effect visible from week 1.
✅ 43% responders vs 16% on placebo.
🏥 Given in clinic. Most patients go home within 8 hours.
Next test: a second Phase 3. Then the FDA.
As a doctor, I find this fascinating. As an investor: one drug, one company, binary risk. I'm watching from the sidelines.
📝 More in my Article this Saturday.
💊 A Doctor on Pharma Stocks (1/12)
I'm a doctor with years of experience running clinical trials. I still rarely buy pharma stocks.
Why:
🧪 ~90% of drugs in the pipeline never reach patients.
💥 One failed Phase 3 can wipe out years of value overnight.
⏰ Every blockbuster has a patent cliff. The clock starts on day one.
💰 A drug can work beautifully and still be a bad business: pricing, reimbursement, competition.
🏛️ And politics can rewrite the price. In 2025, Novo and Lilly agreed to cut US prices on their obesity drugs under pressure from Washington.
Knowing the science helps. It doesn't make the pipeline predictable.
📝 Full analysis in my Article this Saturday.
$TSLA reports tonight. As an $UBER shareholder, I'm watching one thing: the cost of the robotaxi race.
🚗 Tesla free cash flow last quarter: -$1.1B
🏭 Tesla capex this year: $25B+
📉 Tesla operating income: $13.7B (2022) → $4.4B (2025)
🚕 Uber free cash flow, last 12 months: $10B+
Tesla is building the robotaxi network itself, and paying for it.
Uber lets 20+ partners build the cars, and takes a cut of every ride.
Both can win. But only one of them gets paid while it waits.
Long $UBER. NFA
$SCHD isn't just an ETF.
It’s a personality trait, a coping mechanism, and emotional stability in a 4-letter ticker. 💸🧘♂️
Namaste. 🙏
$TXN before earnings (3/3)
What the dot-com crash taught TXN shareholders.
📉 2000: the stock peaked.
💥 2002: down ~85%.
⏳ It took more than 15 years to get back to the 2000 high.
But while the price went nowhere:
💵 The dividend went from $0.09 a year (2004) to $6.08 today. Raised 23 years in a row.
🔄 Shares outstanding fell 47%. Every owner got a bigger slice.
For 15 years, that was most of the return.
That's why I don't buy $TXN for one quarter.
Results tonight. I'll post the numbers that matter 👇
Long $TXN. NFA
💊 A Doctor on Pharma Stocks (8/12)
A psoriasis drug designed on a computer just beat the first drug in its class head-to-head.
💻 Schrödinger's platform → Nimbus → Takeda ($4B upfront, 2022)
💊 Zasocitinib: an allosteric TYK2 inhibitor, optimized in silico before it was ever made
🥊 Phase 3 vs deucravacitinib, not just vs placebo
✅ PASI 100 at week 16: >35% of patients with completely clear skin. 2.5x+ the comparator.
FDA decision expected Q1 2027.
I talked about this at the MIND 2026 conference. This is what AI-designed drugs look like in practice.
$TAK $SDGR
📝 More in my Article this Saturday.
$NFLX will probably pay a dividend one day. I just don't think that's a reason to buy it now.
Quick math after Q3:
• 2026 FCF guide: ~$12B
• ~$2.8B of that was a one-time WBD fee
• Core FCF: ~$9.5–10B. 2025 was $9.46B
• So core FCF is roughly flat this year
At ~$65, that's about a 3.6% core FCF yield.
Buybacks are huge ($4.8B last quarter, a record). This year they're buying back more stock than they make in FCF.
When the dividend comes, I expect a small yield (0.5–1%). The real question is engagement: view hours grew just 2% in H1.
On my watchlist. Not a buy for me yet.
Netflix's biggest problem isn't subscribers. It's engagement.
📺 Viewing hours grew just 2% in the first half of 2026.
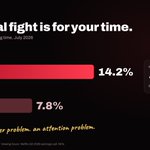
🍿 YouTube now gets almost 2x Netflix's share of US TV time (14.2% vs 7.8%).
It's not the live shows. Live is ~5% of the content budget and only ~1% of viewing. It's built to bring new members in.
Investors are used to double-digit growth. 2% doesn't cut it.
That's why $NFLX trades at ~19x forward earnings. Close to where it was in the 2022 crash.
Tonight after the close, I'm watching one thing: are people watching more?

💊 A Doctor on Pharma Stocks (7/12)
If I had to own one pharma stock, it would be $LLY .
📈 Revenue +46% last quarter. $23B.
💵 Free cash flow: $3.8B → $9.0B in one year.
🖥️ Building pharma's most powerful AI supercomputer with $NVDA.
But it's not capital light. Not even close.
🏭 $50B+ committed to new US factories since 2020.
🏛️ And it already had to cut US prices under political pressure.
At ~$1.2T, the market expects a lot.
Best in class. Just not cheap, and not light.
📝 More in my Article this Saturday.
Yesterday I said engagement was $NFLX biggest problem.
Then I read the full Q3 shareholder letter. Profit beat. The stock still fell.
Here's what the headlines missed 🧵
Netflix's biggest problem isn't subscribers. It's engagement.
📺 Viewing hours grew just 2% in the first half of 2026.
🍿 YouTube now gets almost 2x Netflix's share of US TV time (14.2% vs 7.8%).
It's not the live shows. Live is ~5% of the content budget and only ~1% of viewing. It's built to bring new members in.
Investors are used to double-digit growth. 2% doesn't cut it.
That's why $NFLX trades at ~19x forward earnings. Close to where it was in the 2022 crash.
Tonight after the close, I'm watching one thing: are people watching more?
What to watch:
✅ Churn improved and price increases didn't hurt
🇮🇳 India is the growth story: view hours +24%, record subscriber adds
❓ Can ads hit plan in 2027?
❓ Does view time grow, or just prices?
Netflix is becoming a mature, cash-returning business. Mature businesses get valued like one.
I don't own $NFLX. Just reading the letter so you don't have to.
Earnings growth is slowing almost everywhere.
That's when boring wins.
Companies with real pricing power and growing free cash flow keep raising their dividends, slowdown or not. That's the whole reason I own $SCHD


