

バンドルカードを運営しているカンムという会社の社長です。今はMUFGグループ。事業開発、PM、エンジニアなど絶賛採用中です!興味をお持ちいただけた方はぜひ以下の採用ページを見てみてください https://teapaw.org/t.co/a4BGhqv2UU
Tokyo, Japan
Joined April 2007
- Tweets20.2K
- Following560
- Followers15.1K
- Likes1.7K



米国で暗号資産を購入する際、詐欺率が高かった決済手段は?
ACH
デビットカード
Apple Pay / Google Pay
ワイヤ
多くの人がACHやデビットを予想したが、実際は3のウォレットが最低だった。セキュリティは最も高いのに、不正は最も多かった。
理由はトークナイゼーションにある。デバイス固有のD-PAN(カード番号)に置き換わるとBINが消え、加盟店による弱いイシュアブロックができなくなった。さらに同じカードを多数のデバイスに登録すると、毎回新しいD-PANが発行され、速度チェックも効かなくなった。
Agentic Commerceでも同じ構造が再現されつつある。エージェントにカードを預ける行為はウォレットと酷似しており、盗用カードを多数のエージェントに登録してトークンを量産する詐欺が想定される。
対策として推奨されるのは、D-PANではなくM-PAN(マーチャント紐づけトークン)を使うことだ。
teapaw.org/soupsranjan/status/211…

Security and fraud concerns are often aligned but sometimes they run counter. The 2017-2022 crypto onramp craze is a great example, and I think we’ll see the same phenomenon with Agentic commerce:
Yesterday I asked which of these 4 payment methods had the highest fraud rates to purchase crypto in the US
1. ACH
2. Debit cards
3. Apple/Google Pay
4. Wires
Most people guessed ACH or debit cards. But the answer is number 3, Apple & Google Pay wallets.
Wallets had the worst fraud despite the best security, for 2 reasons:
1. Wallet tokenization design was built with mostly security in mind and ignored fraud concerns
When you add a card to a wallet, its 16-digit card number (PAN) is replaced with a device-specific number (D-PAN). The D-PAN doesn’t keep the card’s first 6–8 digits, the BIN, which merchants use to identify the issuing bank.
Each bank’s tokens did get their own new BIN range, so the issuer was still technically identifiable. But merchants had no way to map those new ranges back to a bank name.
That broke a common fraud control. Merchants keep blocklists of issuers with weak fraud controls and decline their cards. Without knowing the issuer, those blocklists stopped working for wallet transactions.
2. Wallet tokenization made some fraud velocity checks meaningless
The other fundamental issue with D-PAN was that it was device bound. A fraudster could take the same card, add it to 1000s of devices and generate all new D-PANs.
Basically, they used the same card over and over but it looked different each time.
***
What did we build to counteract these issues?
(I promise we'll get to agentic commerce!)
It took us several years to get to the bottom of this and countless conversations with Apple, Google, Visa and Mastercard.
The solution that we & the industry now use:
1. New tokenization method called M-PAN which is a merchant bound token to prevent a fraudster from creating 1000s of D-PANs from the same card number.
2. Visa created a new API called Payment Account Reference, which lets you identify if two D-PANs are connected to the same PAN.
3. New mapping built from D-PAN BIN ranges to identify issuers, so “issuer name” based rules still work.
These solutions are available to our merchants who use us for fraud prevention on wallet transactions.
***
The question we’re now asking: what does this mean for Agentic commerce?
History is repeating itself. Agentic shopping is essentially introducing a new actor, an Agent, to whom you need to hand over your card. In many ways, an Agent appears like a wallet.
We’re very likely to see similar fraud vectors like adding a stolen card to 100s of Agents and generating a new D-PAN for each of them to shop.
As Agent builders figure out how to tokenize the consumer’s card, our suggestion would be to use M-PAN over D-PAN.
If you need help with all this, reach out. We’re building solutions to these problems at @sardine — more to come this week! — and are here to help and brainstorm.
1
5
1,310
8maki retweeted

「若き投資家への手紙」第23弾です!
毎週火曜日公開なのですが、明日が、祝日なので、1日早めての公開です。
今、思い出しても暗澹たる気持ちになる、私の大きな失敗の一つについて、正直に告白します。
【失敗の解剖 #5】数字は嘘をつかないが、人は嘘をつく——粉飾という悪夢|Tatsuo Tsutsumi 堤 達生 @tatsuken0205 note.com/tazy_capital0205/n/…

8maki retweeted

銀行業界でカスハラ対策が急がれている。観光業界では「人材確保・定着」が最重要だが、銀行業界は少し異なる。
1. 銀行は実は被害発生率が高い(小売に次ぐ水準)
帝国データバンクなどの調査では、金融業界のカスハラ被害経験率は約27〜30%で、小売に次いで高い水準。対人サービス業ですが、顧客の「お金」や「信用」に直結するため、感情がエスカレートしやすいのが特徴。
2. 銀行業務特有の要因
・本人確認・手続きの厳格化が、「犯人扱いされた」と怒る顧客を増殖させている。預金の払い戻し時に確認を求めただけで土下座を要求された事例も報告されているほど。
・利害対立が生じやすい場面:手数料、融資審査、口座凍結、手続きの遅延・煩雑さなど、顧客の不満が直接行員に向かいやすい。
・支店窓口では一人の担当者が対応することが多く、逃げ場がない。長時間の居座り、暴言、物の投げつけといった行為が起きている。
こうした背景から、「人材確保・定着」の問題は銀行でも深刻です。地方銀行を中心に支店の人手不足が課題となっており、カスハラによるメンタル不調や離職がさらに人材難を悪化させます。
3. 法的・コンプライアンス上の必要性
カスハラはすでに精神障害の労災認定基準にも追加されており、放置は企業リスクそのものです。
4. 業務品質・経営への影響
精神的に追い詰められた行員は判断ミスを起こしやすく、金融取引では誤送金や手続きミスが大きな損失につながる。また、ストレスの高い職場ではサービス品質が低下し、顧客満足度や銀行の信頼にも悪影響を及ぼす。
・日銀、物価2%到達を表明・金利は据え置き
・SMFG、SBIのステーブルコイン開発会社に5%出資
・滋賀銀と池田泉州HD、28年4月の経営統合で基本合意
・ゆうちょ銀、松井証券に2割出資へ
・バイナンス、約63億ドルのハッキング被害
・3メガ、ステーブルコイン共同発行を実証
note.com/8maki/n/nf19d382690…

1
1
1,135


8maki retweeted

Espressif sort un petit boîtier carré à 59 $ pensé pour que ce soit ton agent qui code le hardware 🤯
ESP-Mosaico, c'est un ESP32-S31 avec écran tactile 480×480, micro, haut-parleur, gyro, et des modules caméra ou LED qui se branchent dessus.
Le détail qui m'a fait tilt : leur repo de démarrage sur GitHub arrive avec un CLAUDE.md, un AGENTS.md, des skills et la config MCP pour Claude Code et Codex. Tu décris ton app, l'agent la code, la valide dans un simulateur, puis la flashe sur la carte.
Les constructeurs livrent maintenant leur matos prêt pour les agents… l'embarqué devient accessible à n'importe quel dev web, et ça c'est un sacré virage 👀

8maki retweeted
何を今さら・・・。
ポイント還元や日常使いでの利便性は、イオン銀行のような流通系がかなり前から先行していて、すでに顧客の生活動線に食い込んでいる。後発のJRE BANKみたいな新規勢の方が、鉄道や商業施設との接点でポイントの使い勝手を高く設計できている。
既存銀行がこれから本気で立ち向かおうとしても、顧客接点の厚みや「日常に埋め込む」スピードで、後れを取っている。
銀行のポイントは「取引のついでに付く」ものだったのが、流通やインフラ側は「日常のついでに銀行機能を載せる」真逆の構造になっている。この非対称は、金利が上がったからといって簡単に埋まらない気がする
ポイント制する銀行に客来る、「+α」で誘引 明暗わける日常使い - 日本経済新聞 nikkei.com/article/DGXZQOUB2…

8maki retweeted
今、ノンバンクが「銀行になりたい」という動機は、過去よりも現実味を帯びている。
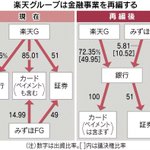
ただし、これは完全な銀行化ではない。預金の最終的な引き受けはスルガ銀行であり、クレディセゾンは媒介役に留まる。預貸率やガバナンスの問題、規制上の制約も残る。それでも、カード会員基盤を活かした預金獲得と、銀行機能を組み合わせた総合金融サービスの布石としては、かなり野心的な一手だ。
3年で1000億円という数字は、大手銀行から見れば小さい。しかし、特定の顧客層(セゾンカード会員やエンターテインメント関心層)を狙ったニッチ戦略としては現実的な目標だろう。成功すれば、他のノンバンクにとっても、銀行提携による預金アクセスのモデルケースになる。

クレディセゾンがスルガ銀行と組み、27年初頭に「セゾンバンク(仮称)」を始動する。3年で10万口座、預金残高1千億円を目指すが、狙いは単なる提携にとどまらず、総合金融グループへと踏み出す構想だ…。
林野宏CEOの「長年の夢」/「セゾン・スルガ銀行」誕生か
facta.co.jp/article/20261102…


都バスの「あと何分」を、スマホのホーム画面と腕時計からタップ1回で見られるようにした話です。
・公式サイトを開き直す手間が消えた
・Android Studioは一度も開いていない
・省電力の対策はスマホと時計で正反対
1人のためのアプリが、割に合うようになった。

1
4
4,769


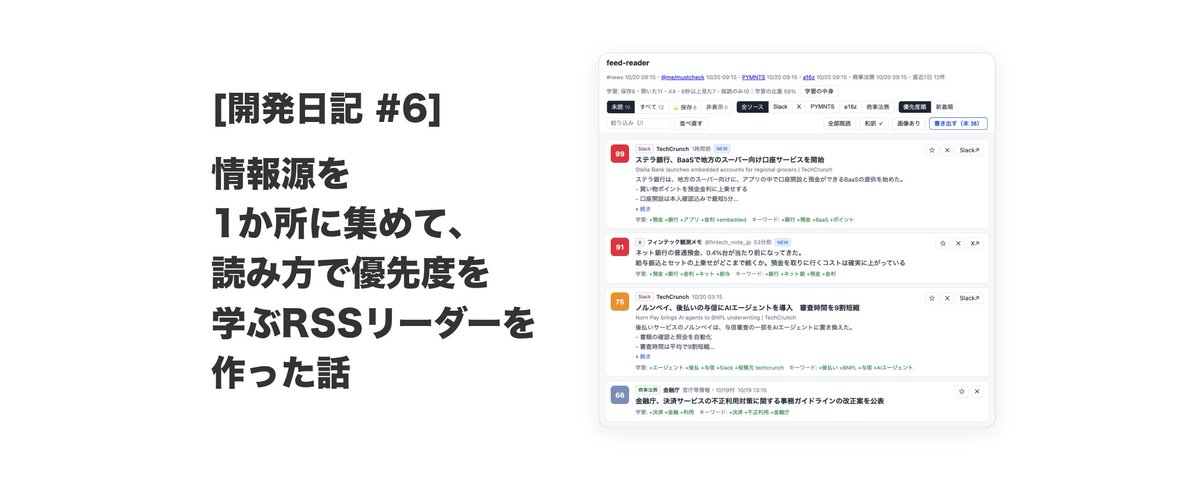
X・Slack・英語メディア・メルマガを1か所に集めて、読み方で優先度を学ぶRSSリーダーをClaude Codeで作った話です。
・見に行く面倒さが消えた
・保存/開く/何秒見たかを学習
・インプットが増えるとアウトプットも増える
開発日記#7。日記を0から書けないので、AIに質問してもらうことにした話
・昨日の予定と支出を下敷きに
・AIが手がかり付きで質問
・音声で答えるだけで日記に
書き溜めた日記が、AIの文脈になる。
note.com/8maki/n/n35da688fc3…

2
829
開発日記#6を書きました。
X・Slack・英語メディア・メルマガを1か所に集めて、読み方で優先度を学ぶRSSリーダーをClaude Codeで作った話です。
・見に行く面倒さが消えた
・保存/開く/何秒見たかを学習
・インプットが増えるとアウトプットも増える
note.com/8maki/n/n927135ed16…

6
1,208
www-pymnts-com.translate.goo…
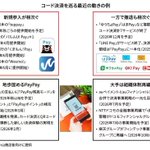
これって要は、銀行が企業向けにAI、細かくはMCPで全資産をいじれるようにするってことだよね?下記でもMax Levchinが、決済は自動化される(判断はユーザーだが、カード番号入力とかはなくなる)ことも踏まえると、AIが支払いも財務もこなす、法人Fintechのゴール感がある
Max LevchinのPodcast
a16z.com/podcast/the-100b-ni…

2
606
【Podcast】a16zの記事から読むAIエージェント決済。消費者の42%は購入をAIに任せない/仮想カード型かトークン型かのウォレット戦争で、マイルやポイントの行方が分かれる/誤発注の責任は未整備/広告690億ドルのAmazonはAIを締め出し、Shopifyは歓迎。
open.spotify.com/episode/46Y…

8maki retweeted

ベンホロウィッツ「ドットコム期は設備を造りすぎて使う人が足りなかった。今のAIは使いたい人が多すぎて設備が足りないので、当時とは逆。今は全てのユーザーがネットに繋がっていて、新しいサービスが世界中の利用者に届くまでが圧倒的に速い」

Ben Horrowitz says AI is different from the dotcom bubble because this time there's a supply shortage, not a lack of demand
"This shortage is so bad, I was speaking with Andy Jassy who runs Amazon yesterday. And I said, 'yeah, we're out of everything until 2028'. He's like, 'Oh, it's beyond 2028. End of 2028, maybe. So everything else is sold out.'"
"So he has the advantage of that he's got supply in a great shortage, which is extremely different than the internet bubble. The internet bubble, we didn't have enough demand because we had to build the internet, people had to get broadband."
"You needed all this stuff, people had to get their browser app, etc. There weren't enough consumers on the internet to absorb all the bandwidth that had gotten built out."
"And they had a massive amount of debt, not unlike what we're building today, although not as big. But the lack of demand killed it. We don't really have a lack of demand in AI. So I think the dynamics will be different."
"I do think that for sure if you get into a pathological debt situation, that can wreck anybody. It's why, by the way, we're not invested in any of these neoclouds either, for that reason, because that whole thing scares me, having been through it."
難: AIで差がつくのは「見立てる力」。伝票処理や契約書の確認など、現場の地味な実務を大量にこなして身につく。最初からAI任せだと、その力が育つ道筋ごと失われ、出力を承認できても見分けられない人が増える。任せることと、苦労してでも自分で通るべきことを分けたい
kaz-ataka.hatenablog.com/ent…
