




Pinned Tweet
Welcome, quick introduction to myself and Arborator Capital.
We are a Czech-based investment fund and research team focused on global small and mid-cap equities, compounders, and asymmetric opportunities.
My investing journey started during COVID. Between 2022 and 2024, I managed a small friends-and-family portfolio and spent thousands of hours researching businesses across global markets. The results were decent, but nothing extraordinary. I performed roughly in line with broader markets.
During those years, I began building positions in several companies that would later become some of our biggest winners. At the time, many of these ideas were highly contrarian and deeply unpopular. I was researching companies such as Bloom Energy $BE , MP Materials $MP , and others long before they became widely discussed by investors. In many cases, the charts looked terrible and most investors wanted nothing to do with them.
In 2024, I tried to break into the professional investment industry. I pitched some of these ideas, including Bloom Energy, to several investment firms during interviews in Prague. Nobody was particularly interested. I didn’t receive a single offer, and looking back, that wasn’t surprising. I was young, had no institutional experience, and many of my investment theses looked completely different from market consensus.
There was even a period during 2024 when I seriously considered whether pursuing investing as a career made sense at all.
Then things started to change. The very companies that had been dismissed by most investors began proving the original thesis right. Bloom Energy became one of the most successful investments of my life, appreciating roughly 3,000% from the time I first started pitching the idea. The AI infrastructure story played out, power demand accelerated, and many of the catalysts I had expected started materializing. At the same time, investments such as MP Materials benefited from the geopolitical shifts and supply-chain risks that had originally attracted us to the opportunity.
As those ideas played out, I continued finding new opportunities across defense technology, drones, critical minerals, software, healthcare, energy, infrastructure and others.
One example was Elsight $ELS.AX , an Israeli drone connectivity company that I discovered while researching Australian market by A-Z method. I shared the idea with several friends months before it became more widely known, and it eventually became one of our most successful investments, generating returns measured in several hundred percent.
I also invested early in Lindbergh $LDB.MI and even travelled to Italy with my friend to meet management in person and better understand the business. It was one of our first in-person meetings with a management team. We hope to continue meeting management teams directly and occasionally share some of the insights and observations we gather from those meetings here on X.
We identified Nebius $NBIS with my friend as a unique AI infrastructure opportunity and invested before the story became broadly recognized by the market. We also benefited from the long-term growth of retail investing through investments such as XTB $XTB.WA , one of the leading brokerage platforms in Europe.
Last big winner was EQ Resources $EQR.AX . After recognizing the strategic implications of China’s restrictions on tungsten exports, I identified EQ Resources as one of the few meaningful western producers positioned to benefit from higher tungsten prices. That investment also generated returns of several hundred percent.
And those are only a few examples. Today, we measure our successful investments in dozens rather than a handful. In 2025, our portfolio generated returns well above 100%, and year-to-date performance in 2026 is approaching 70 % (BE excluded). While we are proud of these results, we remain fully aware that investing is a long-term game and that difficult periods inevitably come with success. 1/2
🚨Stock at 0.9× P/E? The Cheapest Company We’ve Ever Bought🛢️
We just bought what might be the most absurdly cheap stock we’ve ever found.
A tiny, almost completely uncovered Asian refinery that was priced for bankruptcy just a year ago is now potentially generating more net profit in a single year than its entire market capitalization.
Yes, you read that correctly.
The stock has already rallied several hundred percent from its lows. We wish we’d discovered it earlier.
But we believe the market still hasn’t fully understood what’s happening.
And here’s the interesting part: this might be one of the most attractive geopolitical hedges we’ve found in the current environment.
The very conditions putting pressure on broader equity markets are creating extraordinary profits for this company.
Why are we so bullish?
→ Less than 1× P/E: We estimate FY2026 net profit of ~RM2.8bn against a market capitalization of roughly RM2.4bn.
→ An extraordinary Q3: Our model projects ~RM965m of net profit in a single quarter, approximately 40% of the company’s market cap.
→ The perfect product mix: Nearly half of refinery output consists of diesel and jet fuel, precisely the products experiencing some of the most extreme global shortages.
→ A hidden competitive advantage: Unlike many Asian refiners, the company sources a substantial portion of its crude locally, avoiding much of the extraordinary tanker freight and insurance costs.
→ A complete balance-sheet transformation: We estimate that the current windfall could eliminate net debt and leave the company generating cash even after refining margins normalize.
→ Potential dividends and re-rating: If our estimates materialize and cash conversion improves, the company could have substantial capacity to return capital to shareholders.
The market appears to be pricing in a rapid return to almost zero profitability next year.
We think that scenario is excessively pessimistic.
The global economy isn’t necessarily running out of crude oil. It’s running short of the ability to refine crude into the fuels the world actually needs.
Russian refineries remain under attack, Middle Eastern refined-product exports are disrupted, Chinese exports are restricted, and global diesel inventories are exceptionally tight.
Meanwhile, the U.S. midterm elections are approaching, and we see considerable uncertainty around what happens next in the Middle East.
And while expensive growth stocks may struggle with renewed inflation, elevated rates and geopolitical uncertainty, this refinery could continue generating extraordinary cash flows.
That’s precisely the kind of differentiated exposure we want in our portfolio.
The valuation is what makes it so interesting
At approximately RM4.05/share, that represents around +40% upside in our base case and +127% in our bull case.
Of course, this is a cyclical, single-asset business, and our bear case is not a guaranteed downside floor.
But we believe the potential cash generation provides an unusually attractive margin of safety relative to the current valuation.
We spent a LOT of time researching this one.
We went through historical financial statements, reconstructed the refinery’s product mix, analyzed diesel and jet-fuel crack spreads, modeled crude sourcing and tanker costs, and rebuilt the company’s quarterly earnings almost barrel by barrel.
We also studied its hedging exposure, working-capital requirements, historical crises, customer contracts and potential dividend capacity.
This isn’t a simple screen showing a low P/E.
The company has almost no meaningful analyst coverage, and we believe very few international investors are paying attention.
We genuinely think this is one of the most unusual and asymmetric opportunities we’ve uncovered this year.
📖 Our full deep dive, valuation model, scenario analysis and investment thesis are now available on Substack:
arboratorcapitalresearch.sub…

🚨 INFLATION IS STARTING TO BITE. AND THE ENERGY CRISIS IS FAR FROM OVER. 🛢️🔥
Brent is approaching $110, WTI is nearing $100, and European natural gas is trading around €90/MWh.
Equity markets are already starting to react negatively. And unfortunately, we don’t see an obvious resolution to the energy crisis anytime soon.
The geopolitical situation is becoming increasingly concerning:
🇺🇦 Ukraine continues targeting Russian refineries and oil infrastructure, despite pressure from Washington to stop. This is putting further strain on an already extremely tight global refined-products market.
🇮🇷 Iran appears unwilling to back down. Attacks on vessels around the Strait of Hormuz have intensified, and transit remains substantially below pre-war levels. Even the oil that manages to get through faces extraordinary shipping and insurance costs.
🇸🇦 Saudi Arabia is increasingly exposed to the escalation. Reports of attacks targeting Saudi Aramco infrastructure and threats against the company underline how vulnerable the region’s energy supply remains.
Meanwhile, tanker rates and insurance premiums have become so expensive that some shipping routes are economically viable only at elevated oil prices.
The longer this continues, the greater the risk of another inflation shock — and the more pressure it could put on equity valuations.
How we’re positioning our portfolio
Fortunately, our exposure to expensive U.S. growth stocks is relatively limited.
Instead, two of our four largest positions are direct bets on elevated oil and European natural gas prices.
🛢️ Arrow Exploration ($AXL.L / $AXL.V) — Our unhedged Colombian oil producer, benefiting enormously from high Brent prices while continuing to increase production. We recently published an exclusive management interview and updated valuation model on Substack.
🔥 Po Valley Energy ($PVE.AX) — Our Italian natural gas producer, with direct exposure to European gas prices and substantial production expansion potential. We published a full deep dive explaining why we believe the risk/reward remains exceptionally attractive.
Both companies also have significant independent catalysts, meaning our investment theses do not rely exclusively on energy prices staying this high forever.
We believe our portfolio is positioned to potentially benefit from further geopolitical escalation, even if broader equity markets correct.
And we’re preparing what could be our most interesting energy idea yet.
⛽ The ultimate diesel shortage play?
Global diesel supplies are under enormous pressure, and refining crack spreads have reached extraordinary levels.
We’ve identified a refinery that we believe could be one of the most asymmetric opportunities we’ve encountered this year.
Despite the stock already appreciating by several tens of percent, our model suggests it still trades below 1x P/E under current exceptionally favorable refining conditions.
Even more interestingly, our conservative scenario suggests relatively limited downside compared with the potential upside if today’s diesel market persists.
We’re currently building the position and aim to publish the full investment thesis, financial model and valuation sensitivity analysis on our Substack within the next 14 days.
This could be one of our most interesting write-ups yet.
📖 Don’t follow our Substack yet? Make sure to subscribe so you don’t miss this one!
arboratorcapitalresearch.sub…
👀 Want an early look?
We’re curious what other investors are buying in this environment.
Send us a DM with your single best investment idea for the current energy and geopolitical cris, whether it’s oil, natural gas, refining or another overlooked opportunity.
In return, we’ll share our preliminary research and investment thesis with you privately, potentially almost immediately and well before the public release.
We don’t know how long this energy crisis will last. But we’re trying to make sure our portfolio is positioned to benefit from it.


🇰🇷 SEERS Technology ($458870.KQ)
Great update from a friend of ours, who did a great job summarizing the latest developments surrounding the company.
We still hold a relatively significant position in SEERS, and there have been some very interesting developments recently.
Definitely worth a read, if you hold the stock ! 👇

$458870.KQ
Seers managed to escape the sea of red across my Asia portfolio this morning, up +3% on an interesting announcement.
The company issued 110b KRW in convertible bonds ($82m USD against a market cap of around $700m USD) with a 5-year maturity (due Oct. 21, 2031).
At first glance, this might not sound like a reason to celebrate given the dilution (9.38% based on the agreed conversion price), but the terms are remarkably favorable for the company, and the use of proceeds is highly interesting:
➢ Coupon rate is 0.0%. Investor upside is entirely dependent on the conversion into equity.
➢ Conversion price: 30,586 KRW per share (+23.8% premium vs. today’s close).
➢ Starting Oct. 21, 2027, Seers holds a call option for 2 years to buy back up to 50% of the bonds at a very modest premium of 0.1% p.a.
➢ Buyers of the bonds are 38 very reputable South Korean institutions and funds, including KB, Shinhan, Kiwoom, Mirae, and Samsung.
➢ Use of proceeds:
◦ 10b KRW for automation and expanding production facilities,
◦ 30b KRW for upgrading existing products & services, R&D for new products, and working capital,
◦ 70b KRW for investments into the MENA and US subsidiaries of Seers.
➢ In a news article that I found, the Seers CEO gets more specific:
"This funding round is a strategic investment to expand our medically proven medical AI technology and business model into the global market. In the U.S., we will secure local diagnostic service infrastructure and AI solution networks, and in the UAE, we will expand business execution based on existing supply contracts to grow into a global medical AI platform company."
➢ In the US, Seers intends to acquire an equity stake in an IDTF (Independent Diagnostic Testing Facility) to accelerate the rollout of its outpatient monitoring platform mobiCARE. IDTFs are diagnostic facilities independent of physician offices or hospitals that conduct, for example, long-term ECG monitoring and bill directly to Medicare. As a reminder: at $250, reimbursement for mobiCARE is roughly 5x higher in the US than in South Korea.
➢ This allows Seers to bypass building out its own US sales network from scratch and avoids lengthy proof-of-concept studies, enabling an immediate market entry into the US.
➢ In MENA, they plan to establish a dedicated operating base for diagnostic services and to roll out specialized arrhythmia centers.
🔍 My take:
➢ A successful international expansion is a core pillar of my investment thesis, so I welcome any positive color on this front. Since Seers' CEO is the largest shareholder, owning around 26% of the comapny, he must have strong conviction that the bond proceeds will turn out to be value-accretive long term, far outweighing the dilutive impact. The 0% coupon alongside participation from such a broad base of high-profile institutional investors also is an encouraging signal in my view.
➢ Following the Q2 print, many Korean analysts cut their growth estimates, which I find hard to understand, as the revenue miss back then was largely a timing issue rather than soft demand (as discussed in my post linked below).
➢ Yet even on these very conservative numbers, the stock IMO is not expensive, trading at 15x EV/EBIT 2026e & 11x EV/EBIT 2027e. Based on my own projections, it's even cheaper than that.
➢ Should Q3 numbers come in strong alongside continued positive newsflow regarding international expansion, I can easily see analysts revising their estimates materially higher again.
BTW: Seers now provides English-language investor decks as well, which you can check out here:
◦ Part 1: file.irgo.co.kr/data/BOARD/A…
◦ Part 2:
file.irgo.co.kr/data/BOARD/A…
As always: This post is not financial advice.
🚨 EXCLUSIVE: A 10%+ Portfolio Position. Multiple Catalysts. Our Best Macro Idea for the Next 6 Months?
Only freely available management interview and deep dive into key findings $AXL.L / $AXL.V 🛢️
Our third-largest portfolio position and our biggest geopolitical/macro bet has already delivered exceptional returns. Our earliest purchases have nearly doubled, yet we remain extremely bullish.
What will you find in our latest deep dive?
🔹 Exclusive management insights: Previously unpublished details from our direct conversation with management, covering current production, year-end expectations and the company’s ambitions for 2027 and beyond.
🔹 The biggest catalyst: Where things currently stand with the extension of Arrow’s crucial Colombian production licence, why it matters so much and what could happen if it is approved.
🔹 Updated cash flow and valuation model: Why we believe Arrow remains extraordinarily cheap even after its recent rally, and why the market may still be underestimating its earnings potential.
🔹 The perfect geology for an oil price spike: We explain why Arrow’s specific Colombian well economics make a temporary surge in oil prices disproportionately valuable. In fact, we struggle to find another producer that benefits more from this particular macro environment.
🔹 Capital allocation and future growth: Management’s plans for reinvestment, production expansion, potential acquisitions and what they ultimately want to achieve over the coming years.
And perhaps most importantly, we explain why today’s extraordinary oil prices could effectively finance a substantial portion of Arrow’s future growth.
This is what makes the opportunity so interesting to us.
Why we’re still extremely bullish on oil 🛢️
The Strait of Hormuz remains heavily disrupted, Iranian attacks have intensified, and exports from the Persian Gulf continue to face enormous logistical and security challenges.
At current shipping and insurance costs, transporting oil through alternative routes can become economically unattractive if prices fall substantially. Without a meaningful de-escalation or agreement, we struggle to see a rapid normalization of the physical oil market.
There are also significant geopolitical uncertainties ahead, including the possibility of renewed U.S.–Iran escalation after the midterm elections. Meanwhile, rebuilding depleted strategic inventories could provide additional support for oil demand.
Even the forward curve suggests that oil prices could remain elevated well into 2027.
And Arrow is exceptionally well positioned for that environment.
During our conversation, management made a remark that perfectly summarizes the situation:
“High oil prices are extremely good for our company, but not so good for humanity.”
Company is one of our favorite geopolitical hedges
What we particularly like is the asymmetry.
If geopolitical tensions continue escalating, oil prices could remain extremely high while broader equity markets suffer. In that environment, Arrow’s unhedged production and strong operating leverage could translate into extraordinary cash generation.
But even if oil prices normalize, Arrow still has meaningful company-specific catalysts, including licence extensions, production growth and potential acquisitions.
We believe another 50%+ appreciation over the next six months is possible.
If you read the full management interview, our updated model and the explanation of Arrow’s unique well economics, I think you’ll understand why we remain so bullish even after the rally.
We’ve spent considerable time researching this company and speaking directly with management to bring you insights that are difficult to find elsewhere.
📖 Full exclusive management interview, investment thesis and updated valuation model on Arborator Capital Research:
arboratorcapitalresearch.sub…
As always, our research is currently free.

Great summary of the current situation at Smart Shooter $SMSH, our second-largest position, from a friend of ours.
We’ve independently reached very similar conclusions and currently see Smart Shooter as one of the most attractive opportunities in the market. That’s exactly why we’re comfortable having such a significant position in the company.
$SMSH $SMSH.TA
I significantly increased my position in Smart Shooter on Monday, the stock now represents >10% of my portfolio.
From my point of view, the R/R has probably never been as good since the IPO as it is right now. Here is my napkin math for FY 2027:
➢ Revenue from Europe, Israel, and APAC in H1/26 was $11.62m USD. Further, these regions contributed $29.7m to backlog. That results in a revenue run rate of $41.32m.
➢ The US JIATF 401 framework, which I covered last week, has a ceiling of $150m. Based on information from other investors who spoke with the company after the announcement, management seems to be confident that the entire $150m volume will be converted into revenue within the 3-year period.
➢ Assuming JIATF 401 contributes $40m in 2027, $50m in 2028, and $60m in 2029 to the topline, adding the RoW run rate brings potential 2027 revenue to $81m. That would represent +47% growth compared to my 2026 estimate of $55m.
➢ I consider the $81m to be clearly conservative, specifically for the following reasons:
◦ JIATF 401 was established to protect military bases, critical infrastructure, and borders. In my view, there is a decent probability that the US will order Smash devices through additional channels for different purposes, such as for special forces and mobile units.
◦ The assumption that the RoW run rate won't increase next year seems unlikely given the omnipresent urgency for C-UAS solutions. On the contrary - Europe / NATO will certainly have followed the JIATF 401 decision closely. US defense procurement decisions carry massive global weight.
◦ The automatic Hopper weapon stations have a 10–12x higher ASP compared to the Smash fire control systems. Their revenue share should continuously increase in the coming years. Long term, Smart Shooter wants to increase the share of Hopper to about 50% of total revenue.
➢ Putting it all together, I stick to my minimum projection of $85m in 2027 revenue, which I laid out in my post on the Q2 results. On EBIT, I see the business capable of delivering a 25% to 30% margin. On $85m of revenue, that translates to $21m–$25m in EBIT, which puts the EV/EBIT 2027e multiple in a range of 9x–10x.
➢ To me, this is way too cheap for a company with an (at least so far) essentially unrivaled product in the field of AI-supported, kinetic drone defense at the soldier level. Peers in the C-UAS space with similar growth rates trade in a completely different stratosphere.
➢ Right now, the stock trades like dogshit and has given back a meaningful chunk of its post-JIATF 401 framework gain. Personally, I think the stock price will rise again as soon as A) the company converts the framework into concrete backlog and revenue and B) the Q3 and Q4 numbers show rising gross margins, EBIT margins, and a decent net profit. My current cost average is 20.86 ILS.
As always: This post does not constitute financial advice, and I am frequently wrong.
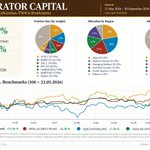
Arborator Capital | Q3 Portfolio Update & Full Portfolio Disclosure🔥📈 1/2
For the first time, we’re sharing almost our entire portfolio, position sizes and the results from our first full quarter managing a meaningful amount of external capital.
Since launching the strategy for external investors on May 21, Arborator Capital returned +12.56% TWR through September 30, equivalent to a +38.7% annualized return over this admittedly very short period.
For comparison over the same period:
Arborator Capital: +12.56%
MSCI World: +6.28%
Nasdaq-100: +3.54%
STOXX Europe 600: +0.87% Arborator_Capital_Kvartalni_report_K004_30.09.2026.pdf
September itself was particularly strong, with the portfolio gaining roughly 5–6%, despite a considerably weaker environment across European equities and many of the small/micro-cap markets where we invest.
It’s obviously far too early to draw conclusions from a few months of performance, and there were plenty of decisions we could have executed better.
But one thing we are particularly happy with so far is the relatively low correlation of our returns with major equity indices.
That is exactly what we’re trying to build: not another portfolio whose performance ultimately depends on whether U.S. mega-cap tech goes up, but a collection of differentiated, concentrated ideas whose return drivers come from completely different sources.
What actually drove the quarter?
Our energy/geopolitical book was probably the biggest success.
Instead of simply buying commodity futures or large producers, we tried to identify small companies where higher commodity prices create enormous operating leverage while company-specific catalysts provide another way to win even if the macro thesis eventually normalizes.
Arrow Exploration ($AXL.L / $AXL.V) and Po Valley Energy ($PVE.AX) became the clearest examples.
Both returned roughly +40% for the fund through September 30, despite being accumulated at different points throughout the period.
Po Valley was particularly interesting. At one point in September, we were almost +80% on a position we had owned for roughly a month. Arrow benefited from higher oil prices while simultaneously increasing production, and we still see the potential Tapir licence extension as an important independent catalyst.
Our largest positions
FitEasy ($212A.T) remains our largest position at roughly 15%.
The latest results were mixed, but our thesis hasn’t materially changed. Monthly operating data suggest the company has already exceeded some of its original full-year objectives, and we think the December full-year results and FY27 guidance could be the next major catalyst.
Smart Shooter ($SMSH.TA) remains our second-largest position at roughly 14%.
This was also probably our biggest execution mistake of the quarter. We might have built the initial position too aggressively and too early, and at one point were down more than 30%.
But we distinguished poor timing from a broken thesis and continued buying within our risk limits. On the final day of September, the company announced the three-year U.S. military framework with a ceiling of up to $150m, and the stock jumped roughly 30% in one session.
The framework is not the same thing as $150m of guaranteed backlog, but relative to Smart Shooter’s historical revenue base, even partial utilization could be highly significant.
Arrow Exploration and Po Valley Energy now follow as two of our other largest positions, alongside names such as SEERS Technology, JSH and 2G Energy.
And that illustrates quite well what we’re trying to do.
🤖 Made with AI


2/2
A Japanese fitness compounder.
An Israeli counter-drone technology company.
Colombian oil.
Italian natural gas.
European distributed power for AI data centers.
Korean healthcare technology.
Japanese niche small caps.
Very different businesses, geographies and return drivers.
Full disclosure
In the attached portfolio graphic, we’re exceptionally disclosing almost the entire portfolio and the actual position weights.
We’ve only hidden a small number of names where we’re still accumulating shares, preparing research for Substack, or simply don’t want to disclose the company publicly yet.
We probably won’t publish exact weights continuously, but we’re considering making this a quarterly portfolio disclosure so people following our research can see not only what we write about, but where we actually put meaningful capital behind our ideas.
We’re also continuing to raise capital. September brought strong inflows, and by quarter-end we were managing approximately €2m, with additional 2-3m already in various stages of discussion.
There is still a huge amount to improve.
Some entries were poorly timed. Some positions should have been larger. Others should have been smaller. And four months certainly prove nothing about whether we can generate long-term alpha.
But so far, we’re reasonably happy with the combination of absolute return, benchmark outperformance and differentiated sources of performance.
And we’re even more excited about what comes next.
Several of our largest positions have important catalysts between now and year-end, and we have a number of new ideas currently under research that we’ll gradually publish on Substack.
Our goal remains simple: find overlooked companies globally, do deeper work than the market, build better information networks around our largest positions, and generate returns that don’t simply replicate the major indices.
We’ll keep sharing the journey — including the mistakes.
Full research on our portfolio companies remains free on Arborator Capital Research:
arboratorcapitalresearch.sub…
Disclaimer: We are a Czech-based investment entity operating under Section 15 of the Czech Act No. 240/2013 Coll., on Investment Companies and Investment Funds (ZISIF). We are not a regulated investment fund and are not supervised by the Czech National Bank (ČNB).
This post is for informational purposes only. It does not constitute investment advice, an offer or solicitation to buy or sell any security, or an offer to invest with us or any affiliated entity. The information reflects our views and estimates, which may be incomplete or incorrect. Past performance is not indicative of future results. Please conduct your own research and consult a qualified adviser before making investment decisions.
We and/or affiliated persons or entities may hold positions in securities mentioned in this post and may buy or sell such securities at any time without notice.
The AI Boom’s Most Unlikely Winner?😳Stock Hidden in Germany’s Fading Industrial Heartland, 20%+ IRR Through 2030!
• €879m+ of new orders in 9 months — >2x last year’s revenue
• Production capacity set to ~3x to ~1GW
• Exploding backlog & data-centre pipeline
• ~43% founder ownership
• Massive operating leverage as volumes ramp
• 20%+ potential IRR through 2030
• Still valued like a German industrial rather than an AI infrastructure company
We are not heavily invested in an AI-related theme as we were a year ago, but we found another story very compelling.
I’ve been bullish on modular, behind-the-meter power for years. Back in 2024, I wrote about $BE on my Czech blog, pitched it in several interviews (no one liked it) and made a video about it for my Czech YouTube channel.
The thesis was simple: the real AI bottleneck wouldn’t just be chips. It would be electricity. Data centres would need huge amounts of reliable power, and they would need it much faster than the grid could provide it. Modular, on-site generation looked like a no-brainer.
$BE has since appreciated by more than 2,000% from around the time I published that thesis.
The problem today? The obvious AI power plays: $BE , $GEV and increasingly $INIO — have already attracted enormous investor attention and, in our view, valuations leave much less room for error.
Then we found this company.
Reading about it immediately reminded me of the original Bloom thesis. Different technology, different company, but essentially the same bottleneck: fast, modular, reliable power behind the meter.
And this time, we think the valuation still makes sense.
The inflection is only beginning. Manufacturing capacity is set to roughly triple just as data-centre orders are exploding, creating potentially enormous operating leverage on both revenue and profitability.
And data centres aren’t the whole story. Behind the AI opportunity sits an established German business: biogas CHP, power generation, Ukraine energy infrastructure, a growing heat-pump business and a highly profitable service operation.
There’s another optionality we find interesting. Modular gas-engine plants are inherently decentralized. Instead of relying on a handful of huge generation assets, critical infrastructure can be supported by many independent units. As Europe thinks increasingly about energy resilience and the protection of critical infrastructure, we believe that characteristic could become significantly more valuable.
Peter Lynch famously warned against looking for the “next Walmart”, “next Microsoft” or “next anything.” Those comparisons usually don’t end well.
So this isn’t the “next Bloom Energy.”
But the market may be giving us a second chance to invest in the same bottleneck — through a different technology, at a very different valuation, just as the earnings inflection begins.
We own it.
Full thesis on our Substack. 👇
arboratorcapitalresearch.sub…
And over the next few days, we’ll also publish a dedicated update on our first full quarter since opening the fund to external investors — including performance, comparison with benchmarks, portfolio characteristics, and some of the most important lessons and developments from the quarter. So stay tuned for that as well.
Credit: @MoodyWriter13 was one of the earliest accounts we found highlighting this company and its behind-the-meter/data-centre opportunity. Big thank you also to our Czech portfolio manager colleague, who firstly brought us this opportunity. His Substack:
substack.com/@fitinvestmenti…

💥 BOOM. Our second-largest position just jumped 30% in a single day. $SMSH
We’re unfortunately just back to break-even (we started buying Smart Shooter too early), but today is a major validation of one of the central assumptions behind our thesis.
Smart Shooter has been awarded a 36-month, single-award IDIQ contract with the U.S. military worth up to $150m for its SMASH counter-drone systems, training and related services. Under this specific contract, Smart Shooter is the sole supplier of the covered SMASH systems.
One important caveat: $150m is a ceiling, not a guaranteed order or backlog. Individual orders still need to be placed.
But the scale is enormous relative to Smart Shooter. And this is exactly why we started building the position before the orders appeared.
Our thesis has always been that kinetic, rifle-mounted counter-UAS systems would become a meaningful procurement category, and that SMASH had a close to monopoly position within that niche. Today’s award is an important piece of evidence in that direction.
Unfortunately, we were early.
Q2 was weak, deliveries were delayed, orders weren’t coming through quickly enough, and the market absolutely punished the stock. We continued adding on the way down, but eventually hit our 15% maximum position size, so there wasn’t much more we could do.
I’ve been here before. Bloom Energy ($BE) was another position where I was far too early and could have bought substantially cheaper later. Being early can look very stupid for quite a while before the underlying thesis starts showing up in the numbers.
What matters now is that we don’t need to materially change the model we previously shared.
We were already assuming a significant ramp in SMASH adoption over the coming years. A month ago, those numbers probably looked like a bull case. After today’s announcement, combined with management increasing production capacity and inventory, I’d increasingly describe them as a reasonable base case.
And there may still be upside to our estimates if actual orders under this framework ramp faster than expected or additional customers follow the U.S. military.
So despite today’s +30% move, we continue to hold the position. We’ll watch the actual purchase orders closely — those matter much more than the headline ceiling — and potentially revise our model upward as we get evidence on volumes.
The timing is also helpful for the portfolio. Some of our energy positions, including Po Valley Energy ($PVE.AX) and Arrow Exploration ($AXL.L / $AXL.V), have cooled after their recent runs because of weakening energy disruption, so having Smart Shooter finally contribute meaningfully to performance is very welcome.
A quick update on us as well: we owe you a few write-ups. We’ve been extremely busy onboarding several larger new investors into the fund before month-end, dealing with operational work, earnings and what has generally been a very eventful market.
Now that the quarter is ending, we plan to publish some data from the first full quarter of the fund with external investors — performance, correlations, portfolio characteristics and comparisons with the major indexes.
We should finish the period at roughly +12% since late May. It hasn’t been our strongest stretch, especially compared with the performance we generated before taking external capital, but we’re increasingly happy with how the portfolio is positioned.
And thank you for the huge increase in followers and Substack subscribers recently. We really appreciate the response and will keep trying to produce as much useful research as possible.
Our full original Smart Shooter thesis, model and assumptions are available on Substack, I’m reposting the model below so you can compare what we expected with what is now actually happening.
Arborator Capital Research on Substack👇
arboratorcapitalresearch.sub…


⁉️40% IRR after the sell-off?
Smart Shooter ($SMSH / $SMSH.TA) sold off more than 20% after earnings. The results were worse than we expected — obviously not ideal — but as we explained in our Substack update, after digging deeper into the numbers, we think the reaction looks overdone and has created a very interesting opportunity.
The price action is also worth watching. When the stock briefly fell below its IPO price and ~1,700, someone bought roughly 500k shares within just a few dozen minutes — close to what normally trades over an entire week. We obviously don’t know who the buyer was, but it looks like a large investor started accumulating aggressively at these levels.
Since then, the price appears to be stabilizing, and we think a significant part of the panic selling may already be behind us.
We added to our position after the sell-off and are attaching our updated model. We don’t think the assumptions are particularly aggressive: no major contribution from new products currently being developed through R&D, no meaningful software/subscription revenues, and no crazy exit multiple comparable to some other Israeli defense-tech names like $ELS.AX or $NXSN.
Even with relatively normal assumptions, our model implies an IRR of around 40% p.a. over the next few years. And we think there is a reasonable chance Smart Shooter can outperform our model if adoption develops as we expect.
You can find our full investment thesis and post-earnings update on Substack:
arboratorcapitalresearch.sub…


Short Portfolio update: back on track — close to +90% YTD 📈🔥
After roughly a quarter of rather disappointing performance, things have finally started moving in our direction again.
The portfolio is now cca 86% YTD, getting close to +90%. Since opening the fund to external investors around the end of May, we’re up 12%+. That’s obviously much less spectacular, as most of this year’s gains came before the fund opened — and unfortunately, we then had our weakest stretch in more than a year almost immediately after taking external capital.
The last few weeks, however, have been much better.
The biggest driver has been our macro/geopolitical book, which is up more than 40% over the past quarter, despite representing only a minority of the overall portfolio.
Some of the biggest contributors:
→ Po Valley Energy ($PVE.AX) — up 80%+ in roughly a month. This was our latest public Substack pitch and has quickly become our second-largest position.
→ Arrow Exploration ($AXL.L / $AXL.V ) — another major beneficiary of our energy/geopolitical thesis. We’re up roughly 40%+ on our average cost, and it is now our third-largest position.
→ Orvana Minerals ($ORV.TO / $ORVMF) — another macro/commodity position that has performed very well.
Our largest position remains FitEasy ($212A.T). The latest results initially looked mixed and the stock sold off, but as we explained in our Substack update, we didn’t think the underlying picture was nearly as negative as the initial reaction suggested. The stock has since recovered nicely.
The largest drag remains Smart Shooter ($SMSH / $SMSH.TA). The performance there has been painful, but our thesis remains intact and we explained in detail on Substack why we continue to hold it.
What I’m particularly happy about is that our returns remain very weakly correlated with the major indexes. Given how concentrated the portfolio is, volatility has also remained relatively reasonable. That’s exactly what we’re trying to achieve: differentiated returns driven by our own ideas rather than simply disguised market beta.
Still, there is plenty of room for improvement. We set a high bar for ourselves and want to maximize alpha while producing more consistent returns across different market environments. May through August certainly wasn’t good enough by our standards.
Fortunately, the last few weeks look much more like what we want to achieve.
And I’m actually quite optimistic about the portfolio into year-end. We see several potentially meaningful catalysts across some of our largest positions over the next few months, which we think could drive further upside before the end of the year.
I’ll go through those catalysts individually — what they are, when we expect them and why we think our largest positions could still appreciate materially into year-end — in upcoming posts and on our Substack.
We also have several new investment theses in the pipeline, including a write-up on another position that has recently started performing very well.
If you don’t follow our Substack yet, everything is still completely free. Our latest public idea has already appreciated by several tens of percent since publication, and we’ll continue sharing new research there.
At the end of the month, we’ll also prepare our next investor report, so I’ll share a more detailed fund performance vs. benchmarks, volatility and portfolio update here as well.
Thanks again for following our work. Hopefully, this positive momentum continues — but more importantly, we’ll keep working to find the next ideas that can drive it.
Follow our Substack so you don’t miss the upcoming year-end catalyst updates and new research.
arboratorcapitalresearch.sub…

Quick portfolio update — mixed few weeks for us.
I’ve just posted several detailed notes in our Substack Subscriber Chat covering what’s happening across our largest positions. There was simply too much to fit into one X post.
$212A.T — FitEasy: The latest results were mixed and the stock reacted accordingly. Our thesis, however, hasn’t materially changed. It is already one of our largest positions, but at these levels we still think the risk/reward is attractive. We explain exactly what happened, why the numbers looked the way they did, and include additional explanations directly from management in the Substack update.
$SMSH / $SMSH.TA — Smart Shooter: Another major position currently experiencing significant weakness. We’ve written a separate update explaining why, despite the disappointing price action, we don’t currently see a good reason to sell and what we’re watching from here.
We also shared what we’ve reduced, what we’ve increased and several new positions we recently added that we haven’t discussed publicly on X yet.
Fortunately, some of our other large positions have been working very well. $PVE.AX — Po Valley Energy and $AXL.L / $AXL.V — Arrow Exploration have been helping offset weakness elsewhere in the portfolio, particularly as our energy thesis continues to play out.
Still, there’s no point pretending everything is great. Since opening the fund to external investors around May, we’re currently only around +5%. We’re still ahead of the relevant indexes, but that’s nowhere near the performance we expect from ourselves.
We set a high bar. Our goal isn’t simply to keep up with an index — we want to generate strong returns even through more difficult markets, while keeping a portfolio of differentiated and relatively uncorrelated ideas. The last few weeks have been very mixed, and we’ll keep working as hard as possible to improve.
The Subscriber Chat update covers our largest positions, recent buys and reductions, new undisclosed additions, and what we’re currently watching across the portfolio.
And finally, thank you for all the support recently — especially the incredible response to our latest write-ups and all the new followers and subscribers. We really appreciate it.
Full portfolio update on Arborator Capital Research Substack 👇
open.substack.com/pub/arbora…
💣🔥Under 1x operating cash flow at current #oil price — our hedge against the biggest oil supply shock in years. $AXL.V
Even after the recent rally, Arrow Exploration has become our second-largest position — and at current spot Brent prices, the company is effectively printing cash.
The macro backdrop for an unhedged oil producer is almost absurd right now:
Hormuz remains closed and Middle Eastern exports are heavily disrupted.
Tanker economics have gone completely insane — shipping crude into China can now cost around $1m/day, versus tens of thousands of dollars historically.
The Middle East conflict continues to escalate, with further disruption to critical energy infrastructure.
The Yanbu pipeline shutdown has removed millions of barrels per day of supply, while Saudi Aramco is restricting European deliveries for the next two months, further tightening an already stressed oil market.
Libya has also seen fresh production disruptions. Russian refineries continue to be hit, tightening an already stressed products market. The U.S. is even considering restrictions on diesel exports as policymakers try to contain domestic fuel prices.
In other words: the physical oil market is extremely tight, and there is no obvious quick fix.
And this is almost the perfect environment for $AXL.
Arrow has just increased production, remains completely unhedged, sells into Brent-linked pricing and has a relatively low-cost production base. At today’s oil prices, the cash generation is enormous relative to its market cap.
In fact, spot prices have moved so far that the sensitivity tables in our original Substack write-up don’t even go high enough anymore.
But what makes the setup particularly interesting is that this is not only a macro trade.
There could be a major Colombia-specific catalyst very soon. Ecopetrol’s shareholder meeting is taking place today, with six of nine board seats expected to change. With Colombia’s new right-wing government, we believe the new board could be materially more supportive of extending Arrow’s crucial Tapir licence — arguably the single biggest company-specific catalyst right now.
If that extension comes through in the coming weeks/months, we think it could unlock another meaningful leg higher.
And there is potentially a second-order opportunity: Arrow is generating substantial cash at these prices while Ecopetrol owns acreage/assets that it may eventually look to monetize. That could give Arrow the firepower to acquire additional production or development inventory, which could Ecopetrol offload for a good price and keep compounding its production base.
The CEO himself has commented that he has rarely seen a company trading at such a low cash-flow multiple relative to its market cap.
High spot exposure. No hedging. Rising production. Huge cash generation. A potentially transformative licence catalyst. And a political backdrop in Colombia that appears to be turning materially more favorable.
Our full $AXL deep dive is on Substack, including the oil-price sensitivity tables and valuation scenarios — although at this point, Brent has literally gone off the top of some of them.
For us, $AXL is increasingly looking like one of the cleanest hedges in the portfolio against a prolonged global oil supply crisis.
🔥 The ultimate portfolio hedge against further escalation in the Strait of Hormuz? We think we’ve found it.
A stock that could benefit enormously if oil prices spike further… while still offering substantial upside even if geopolitical tensions ease.
Since the conflict around the Strait of Hormuz escalated, we’ve been asking ourselves one question:
Is there a stock that benefits massively if oil spikes… but can still generate outstanding returns even if tensions fade?
After weeks of research, we think we’ve found exactly that.
In our view, it’s one of the most attractive macro hedges available today.
If tensions escalate further, it could be among the biggest equity beneficiaries.
If they don’t, we still believe the company is undervalued based on its own fundamentals.
It’s currently our third-largest position, behind only FitEasy $212A.T and Smart Shooter $SMSH . (Other write ups are on Substack)
Here’s why:
• 🛢️ Virtually no oil hedging – almost every additional dollar of Brent flows directly into cash flow.
• 💰 Net cash equal to roughly one-third of its market cap, with no debt.
• 📈 Trading at roughly ~1× this year’s EBITDA (our estimates).
• 💵 EV/FCF below 2× even assuming Brent prices slightly below current levels.
• ⛽ Expected to generate cash over the next two years approaching today’s entire market capitalization.
• 🚀 Several company-specific catalysts (independent of oil prices) that we believe could unlock 30–50%+ upside on their own.
• 📊 Every analyst report we reviewed values the shares roughly 50–100% above the current price.
The market has started to price in higher oil prices, but in our opinion it still hasn’t fully reflected either the improving company-specific outlook or just how much operating leverage this business has to elevated Brent prices.
We published our full investment thesis, valuation model and scenario analysis today.
The full write-up is available on our Substack link in below 👇

🔥 Our post yesterday pushed the stock up more than 10%. You guys are crazy 😂
Thank you for the incredible response to our Po Valley Energy ($PVE.AX) write-up. Assuming yesterday’s activity was largely driven by the post, trading liquidity increased by more than 10x and the share price jumped 10%+ in a single session.
Welcome aboard to everyone who joined us.
Apparently, we even caused a bit of a stir inside the company itself — the CEO emailed us about the unusual attention and trading activity. I guess they’re not quite used to this level of investor interest in a single day.
But I’m sure he doesn’t complain: his stake in the company gained a few hundred thousand euros in value during the session. Ours gained a few tens of thousands too, so we certainly can’t complain either.
More importantly, thank you for the amazing response to the research and to everyone who read, shared, subscribed or reached out. We genuinely appreciate it.
And a huge thank you to everyone who helped spread the idea — especially @capitalemployed for featuring our $PVE.AX thesis as the Best Stock Pitch of the edition, and @TradeIdeasFlow for sharing our research as well. We really appreciate the support and the reach you’ve given our work.
The full $PVE.AX write-up, including our investment thesis, valuation scenarios, catalysts and risks, is available on Arborator Capital Research on Substack.
And welcome to all the new followers and subscribers — hopefully we’ll bring you a few more overlooked ideas like this one soon. 🔥

❗️We just bought almost 1% of a tiny European gas producer.
And we think it may be one of the most asymmetric bets we’ve found this year.
European gas is back above €80/MWh, storage levels are low, and we don’t think Europe’s energy problems are over.
We’re Europeans ourselves, so our thinking is simple: if we’re going to freeze at home this winter, we’d rather get rich while doing it than just freeze.
Over the past few weeks, we’ve therefore bought as many shares as liquidity allowed. Together with our partners, we now own close to 1% of the entire company.
And liquidity matters here. A large part of the shares is held by management, insiders and other long-term holders, so building a meaningful position isn’t particularly easy. We don’t plan on selling ours anytime soon either.
Why do we like this setup so much?
• Potential ~5x production growth. The company is approaching several important catalysts that could allow production to increase dramatically over the coming months and years.
• Multiple near-term catalysts. Permits, reserve development and new production could all materially change the economics of the company. Several of these catalysts could arrive within the next few months.
• Extremely attractive gas economics. The company produces exceptionally clean, low-cost natural gas and sells its production essentially at spot prices, even achieving a premium to the relevant benchmark.
• The downside case still looks attractive. We don’t need another European energy crisis for the investment to work. If only a few things go right and gas prices eventually normalize, we still see a realistic path to 100%+ upside over the next 3–4 years.
• The bull case is much more interesting. The company owns additional projects to which we believe the market currently assigns essentially zero value. If those assets are developed and European gas prices remain elevated, our bull case points toward roughly a 5x return over the next four years.
• And management is unusually aligned. The CEO has significant skin in the game, takes relatively modest compensation, and doesn’t want to endlessly recycle cash into new oil & gas projects. The objective is to derisk and monetize the existing assets and ultimately return the cash to shareholders.
That last point is particularly important to us. We’ve looked at plenty of tiny commodity producers where management seems more interested in building an empire than creating per-share value. We think the incentives here are very different.
The asymmetry is what ultimately made us build such a large position.
If European gas prices normalize significantly, we believe the company can still create substantial shareholder value simply by executing on the assets it already owns.
But if Europe’s energy crisis persists, production ramps as planned, and some of the assets currently valued at essentially zero begin to be monetized, the economics become completely different.
It’s also exactly the kind of diversification we’re looking for right now. While seemingly everyone is chasing the same AI trades at increasingly demanding valuations, this is a tiny, overlooked European gas producer with completely different return drivers and potentially enormous operating leverage to one of Europe’s biggest macro risks.
My colleague put together what I think is one of the best write-ups we’ve published on our Substack so far — very concise, straight to the point, and easy to follow. Definitely worth a read if the idea sounds interesting.
Our full investment thesis, valuation scenarios and the company itself are all in the Substack write-up below.
If you haven’t read this one yet, it’s definitely worth revisiting.
We now own both $150A.T (JSH) and $477A.T (Startline) — two of the most obscure businesses in our portfolio, both built around Japan’s disability-employment system. $477A itself derives essentially all of its business from disability-employment support.
DAAS — Disability as a Service might genuinely be one of the strangest business models we’ve ever found.
And the funniest part? It has become an indirect beneficiary of Japan’s AI / semiconductor CAPEX boom, as tighter labor markets make disability quotas even harder for corporations to meet.
It sounds almost absurd, but we think both $150A and $477A have a realistic chance of materially outperforming the indexes over the next few years.
Probably one of the most entertaining, obscure rabbit holes we’ve gone down so far.
Full deep dive on Substack:
arboratorcapitalresearch.sub…
🔥We just found the strangest, most overlooked way to bet on the current AI buildout.
DAAS (Disability as a Service)⁉️
Probably one of the strangest business models capitalism has managed to create.
A small Japanese company built a business around Japan’s disability employment quota. Large corporations that struggle to meet the legally required quota pay this company to employ and support workers with disabilities at purpose-built hydroponic farms — while helping those corporations satisfy their statutory employment requirements.
Weird enough on its own.
Then TSMC opened its Kumamoto fab.
The semiconductor/AI investment boom tightened the local labor market, making it even harder for companies to meet their disability quotas. Demand exploded — while the company barely needed to spend a yen on marketing to make it happen.
And now the economics are inflecting dramatically:
→ A year ago, the company was loss-making
→ Just two months after issuing guidance, management raised its profit forecast by 100%+
→ Revenue growth is now translating into massive margin expansion and operating leverage
→ Management expects operating profit to roughly triple within two years
→ On our estimates, the stock trades at only around 3–4× 2028 EBIT
→ The company has started paying a dividend
→ It also launched a massive share buyback program — particularly unusual for a Japanese small-cap
→ Yet it remains tiny, underfollowed and largely uncovered by analysts
This might genuinely be one of the most bizarre investment theses we have ever worked on.
But underneath the bizarre story is a company going through a major earnings inflection, with the Japanese semiconductor and AI capex boom becoming an unexpected tailwind.
A strange business, massive operating leverage, 3–4× forward EBITDA, dividends + buybacks, and almost nobody is looking at it.
🔗 Link for the full write up below 👇

1/3 — THE ENERGY CRISIS IS BACK 🛢️🔥
Hormuz is still effectively closed. The war is escalating. Brent is back above $100/bbl. And Europe may be heading straight into another energy shock.
At this point, tankers in the Gulf are starting to look less like commercial vessels and more like targets at a shooting range.
And the problem is no longer just crude oil.
The entire global energy system is becoming increasingly tight at the same time:
→ Brent is back above $100/bbl
→ Normal shipping through Hormuz remains severely disrupted, cutting off one of the most important arteries of the global oil & LNG market.
→ Russian refining capacity and product exports remain constrained.
→ Middle Eastern exports of refined products have been severely disrupted.
→ Global inventories of middle distillates are extremely tight.
→ European diesel is now trading around $200/bbl, while diesel refining margins recently reached all-time highs.
→ US diesel prices have also reached record levels.
And now natural gas is joining the party.
European TTF is approaching €80/MWh — the highest level since early 2023 — while European storage is only ~67% full heading into winter.
This is becoming a particularly nasty combination for Europe:
Less LNG + less refined-product supply + extremely tight diesel markets + low gas inventories + winter approaching.
And unlike earlier this year, this is no longer just a theoretical geopolitical risk premium.
It is showing up directly in physical energy markets.
Diesel cracks are exploding. Gas is exploding. Oil is above $100. Shipping remains heavily disrupted. And the longer Hormuz stays constrained, the more inventories are being drawn down.
We have been positioning our portfolio for this scenario for months.
And interestingly, we don’t think crude oil itself is necessarily the best way to play it anymore.
There are several businesses downstream — particularly refiners and a few very specific European gas producers — where the earnings sensitivity to what is happening right now is absolutely enormous.
Some of them are effectively turning into cash-printing machines at current spot prices.
And that’s where we have been putting capital.
↓ Our three favorite ways to play the energy shock:
🔥 The ultimate portfolio hedge against further escalation in the Strait of Hormuz? We think we’ve found it.
A stock that could benefit enormously if oil prices spike further… while still offering substantial upside even if geopolitical tensions ease.
Since the conflict around the Strait of Hormuz escalated, we’ve been asking ourselves one question:
Is there a stock that benefits massively if oil spikes… but can still generate outstanding returns even if tensions fade?
After weeks of research, we think we’ve found exactly that.
In our view, it’s one of the most attractive macro hedges available today.
If tensions escalate further, it could be among the biggest equity beneficiaries.
If they don’t, we still believe the company is undervalued based on its own fundamentals.
It’s currently our third-largest position, behind only FitEasy $212A.T and Smart Shooter $SMSH . (Other write ups are on Substack)
Here’s why:
• 🛢️ Virtually no oil hedging – almost every additional dollar of Brent flows directly into cash flow.
• 💰 Net cash equal to roughly one-third of its market cap, with no debt.
• 📈 Trading at roughly ~1× this year’s EBITDA (our estimates).
• 💵 EV/FCF below 2× even assuming Brent prices slightly below current levels.
• ⛽ Expected to generate cash over the next two years approaching today’s entire market capitalization.
• 🚀 Several company-specific catalysts (independent of oil prices) that we believe could unlock 30–50%+ upside on their own.
• 📊 Every analyst report we reviewed values the shares roughly 50–100% above the current price.
The market has started to price in higher oil prices, but in our opinion it still hasn’t fully reflected either the improving company-specific outlook or just how much operating leverage this business has to elevated Brent prices.
We published our full investment thesis, valuation model and scenario analysis today.
The full write-up is available on our Substack link in below 👇
2/3 — The real money printer might be refining 🛢️💰
The obvious way to play this energy shock is oil.
We own Arrow Exploration ($AXL.V ) for that exposure, and the thesis has worked very well for us so far.
But right now, we think the more extreme economics may actually be one step further downstream: European refining.
Why?
Because crude is tight — but refined products are even tighter.
The world is effectively missing huge volumes of refined products from Russia and the Middle East, while global refining capacity is struggling to compensate.
The result is something we have almost never seen before:
European diesel cracks have recently approached/exceeded $100/bbl.
For context, they averaged only around $21/bbl in 2025.
That is an absolutely enormous change in refinery economics.
And this is why we have been building positions in two Greek refiners:
HELLENiQ Energy ($ELPE.AT ) and Motor Oil Hellas ($MOH.AT ).
These aren’t random refiners.
They are unusually well positioned for exactly the shortage the world is experiencing today.
HELLENiQ Energy ($ELPE)
$ELPE already produced roughly 56% of its Q2 output as diesel + aviation fuel, while diesel and jet exports increased 35% YoY.
Even before the latest spike in cracks, HELLENiQ generated a $22.5/bbl realized refining margin in Q2 versus a $9.5/bbl benchmark.
And Q2 Refining EBITDA was already around €318m.
Now compare that environment with today.
Our sensitivity model suggested that at an exceptional refining environment with a ~$29/bbl system benchmark and ~$43/bbl realized margin, $ELPE could theoretically generate roughly €2.65bn of annualized refining EBITDA and ~€3bn of Group EBITDA.
And current diesel cracks have moved far beyond the levels that originally looked “exceptional.”
Motor Oil Hellas ($MOH)
Then there is Motor Oil Hellas ($MOH), which may be an even cleaner pure play on the current dislocation.
Its Corinth refinery is highly complex and optimized toward high-value products, while roughly 74% of FY25 volumes were exports + bunkering.
That gives $MOH enormous exposure to international product prices when European diesel and jet markets become dislocated.
Our previous sensitivity work suggested that under exceptionally strong middle-distillate conditions, Motor Oil could potentially generate a €2.6–3.4bn annualized Group EBITDA run-rate.
Again, these are NOT full-year forecasts.
Nobody should assume $80–100/bbl diesel cracks persist indefinitely.
But that’s exactly the point:
They don’t need to.
If these margins persist for even a few months, Q3 cash generation could be extraordinary.
At current spot economics, these refineries may be generating in a single quarter a meaningful portion of what would normally represent an entire year’s earnings.
And the longer Russian and Middle Eastern refined-product supply remains constrained, the more interesting this trade becomes.
$ELPE: FY25 EBITDA was ~€1.1bn. Our ~€3bn run-rate is ~2.7× higher, implying several times higher normalized FCF at current refining economics.
$MOH: FY25 EBITDA was ~€1.2bn. Our €2.6–3.4bn run-rate is ~2.2–2.8× higher, with our model implying roughly 3–4× higher FCF versus a normal year.
Oil above $100 is great for producers like Arrow Exploration ($AXL).
But diesel cracks around historical extremes can be absolutely insane for the right refiners.
And $ELPE + $MOH are currently two of our favorite ways to play it, but we have quite small positions.
But there is one European energy trade we currently like even more… ↓


3/3 — Our favorite asymmetric energy bet 👀🔥
But the energy trade we are most excited about right now is European natural gas.
TTF is now approaching €80/MWh, its highest level since late 2022/early 2023, while European storage is only around 67% full vs. ~80% a year ago. Middle Eastern LNG exports have collapsed and Europe is heading into winter with an unusually thin safety cushion.
And we think we found an almost perfect small-cap way to play it.
We are currently accumulating a tiny European gas producer that:
→ has essentially direct exposure to European spot gas prices
→ has no meaningful hedging, so higher TTF flows almost directly into cash generation
→ already produces gas from existing infrastructure
→ should be able to multiply production over the next few years without having to build an entirely new infrastructure network
→ has very low operating costs, meaning incremental production should carry extremely attractive margins
→ and still trades at a valuation where we see 100%+ potential upside even if European gas prices normalize
The interesting part is the asymmetry.
The company’s existing producing asset was doing roughly 80,000 scm/day at much lower gas prices. In August, at an average realized price of €0.67/scm, the field generated a record month of revenue.
Now imagine production eventually moving toward ~300,000 scm/day while European gas remains anywhere close to current levels.
The FCF sensitivity becomes enormous.
And we don’t need €80/MWh forever for the thesis to work.
Even if the war de-escalates, Hormuz reopens and European gas eventually returns toward much more normal levels, our model still suggests potentially >100% upside as production ramps.
But if the current LNG disruption persists into winter and TTF remains elevated?
The upside gets pretty crazy.
That’s exactly the type of hedge we like: a company where the fundamental production-growth thesis can work in a normalized environment, while an energy crisis gives you enormous additional optionality.
We are still accumulating the position, so we haven’t disclosed the name yet.
But we’re preparing a full deep dive + production model + FCF sensitivity at €30/35/40/50/60/80/100 per MWh for our Substack over the next days.
If you want to see the company before we disclose it publicly, follow Arborator Capital Research:
arboratorcapitalresearch.sub…
This might be our favorite European energy setup right now.