
Trying to find value in the most overlooked sections of the stock market and write about them in my blog Founder of @QualScreener
Joined August 2019
- Tweets496
- Following334
- Followers2.7K
- Likes424
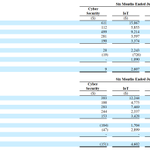





$SPCB Interesting to see SuperCom publish a press release about its cybersecurity segment for the first time since 2022. The segment has been slowly bleeding out, but suddenly grew 50% in H1'26. There could be some momentum building here, although the segment is still small relative to IoT segment.
prnewswire.com/news-releases…

$DOV.MI doValue investor day takeaways:
EBITDA guidance for 2026 was lowered from €300m to €270–290m. This was expected given Italy’s underperformance.
Management guided €330–350m EBITDA by 2029, comfortably ahead of anyone’s expectations. The interesting part is the mix.
coeo EBITDA is expected to grow at a ~30% CAGR, driven largely by margin expansion from 28% to 47%. coeo has had to hire a lot of AI specialists to automate its systems, but those systems now seem to be in place, so operating leverage should kick in. Although this kind of margin expansion sounds unrealistic, the margin target is less aggressive than it sounds. coeo already ran at ~38% in H1 2026. Annualizing H1 2026, the 2029 plan implies only ~8–12% revenue CAGR and margin expansion from 38% to 47%. To me the margin target is still extremely ambitious, as you would expect a lot of competition in a growing market with those kinds of margins. The growth, however, doesn’t look overly optimistic at all.
The legacy NPE guidance, on the other hand, is very conservative. The plan assumes historically low NPL inflows and collections continue, essentially that the market stays at its cyclical low. Importantly, the decline reflects market volumes, not share loss. In every market, most notably Greece, doValue is winning a larger share of new NPL flow than its current market share. Management assumes a significant revenue decline, mostly offset by cost cuts from rolling out AI across the parts of the process where coeo has already implemented it.
They plan to return €150–300m through 2029 via dividends, buybacks and potential bolt-on M&A, which is ~43–86% of market cap. They also launched a €10m buyback (~3% of shares) today, saying the stock is significantly undervalued and buybacks are the best current use of incremental capital.
All in all, thesis still intact and if you want a deeper dive into the company, check out my Substack (Link in bio).


For those wondering what this stock was: Protasco $5070.KL, a Malaysian road maintenance company. It traded at around 2x earnings, with land on the books worth more than the entire market cap.
It was a binary situation. Their concession (the right to maintain all federal roads in a region) expired in early 2026, and they got an interim extension to early 2027. My thesis was that they would very likely win the concession from 2027 onward, for several reasons. That would keep earnings up and let them restart dividends, potentially up to a 20% yield, which I believe would lead to a re-rating in their multiples.
Then @Premski_SGP, who knows the situation well, pointed me to a LinkedIn post by a Roadcare employee. Depending on how you read it, it sounds like the firm lost the concession tender, and the employee is looking for a new job. It's not confirmed by any company filing, and the closing lines of the post are ambiguous. But it was enough to change my odds on the one thing the thesis depended on, so I sold. Link to the linkedin post below.


Just published a write-up on DoValue $DOV.MI.
DoValue is Southern Europe's largest collector of NPLs, loans that are no longer being paid back. Banks and investors pay it to manage and collect them. The shares trade at about €1.65, a market cap of roughly €310m.
On the company's own guidance, doValue will generate about €300m of EBITDA and €90m of free cash flow this year. That puts it at roughly 4x EBITDA once you include the debt, with a free cash flow yield of almost 30%.
A valuation like that comes with problems. doValue took on a lot of debt, partly to buy coeo, a German digital collector of buy-now-pay-later and other consumer debts. Italy also had a weak first half, and the group reported a net loss. The credit market is far less worried: Fitch and S&P both rate doValue BB with a stable outlook, and it recently borrowed at 5.375%.
My thesis is simple:
- The old business is a slowly melting ice cube that still throws off a lot of cash.
- coeo is growing about 25% a year. It diversifies the group away from the traditional business and is already doing better than management expected.
- Debt should come down quickly, helped by the sale of a receivables portfolio that came with coeo.
- The NPL market is at a cyclical low. If credit weakens or we enter a recession, more loans go bad and demand for doValue's services rises. That makes it a useful diversifier in a portfolio otherwise exposed to the broader economy.
If leverage falls from about 3x toward 2x, I don't think the stock stays at 4x EBITDA. And the thesis doesn't need the NPL market to recover. The business already generates plenty of cash, and coeo adds a growth engine on top.
The next catalyst is close: doValue presents its new business plan at a Capital Markets Day on 8 October.
You can find the link to my full write-up in my bio!
While writing the portfolio update, I realised I had too much to say for one post, so I'm splitting it into parts. I wanted to give my two new positions a proper write-up, since neither is widely followed on X. As you may have seen in my last post, I came across a LinkedIn post that changed my entire thesis on one of them, so I won't be writing that one up. The other deep dive is out now. Go check it out.
This weekend I'm posting a portfolio update with 5 new pitches:
- Illiquid Italian company providing zero commentary to the markets. I found out that they got permitted to start a new facility that could almost double earnings, trades at 2.5x current earnings
- Stable, growing company at 1x EBITDA and 3x FCF
- A Speculative stock with massive upside, soon to be uplisted to Nasdaq
- Roll-up firm buying companies at <1x sales and offshoring work to push margins above 20%. Trades at 3.5x FCF
- A stock trading at 0.25x book and 2x on weak earnings
Plus short updates on $SPCB, $DBO.TO and $LODE
Sorry for not writing in a while, I have been working and studying.
Spent days researching a stock, bought in, and almost done with my write-up when a LinkedIn post by an employee flipped the whole thesis. Probably selling on Monday. Hate it, but the hours I put in aren't a reason to stay in.
This weekend I'm posting a portfolio update with 5 new pitches:
- Illiquid Italian company providing zero commentary to the markets. I found out that they got permitted to start a new facility that could almost double earnings, trades at 2.5x current earnings
- Stable, growing company at 1x EBITDA and 3x FCF
- A Speculative stock with massive upside, soon to be uplisted to Nasdaq
- Roll-up firm buying companies at <1x sales and offshoring work to push margins above 20%. Trades at 3.5x FCF
- A stock trading at 0.25x book and 2x on weak earnings
Plus short updates on $SPCB, $DBO.TO and $LODE
Sorry for not writing in a while, I have been working and studying.
SpruceHill Capital retweeted

$DBO.TO $DBOXF $CNK Cinemark Q2 results out this morning. Holy smokes!
New all-time quarterly record for D-BOX ticket sales, up more than 50% yoy! Cinemark is about half of D-BOX's installed base, so we don't know for the other half. But I wouldn't be surprised to see royalties push close to $6M (vs $3.99m last year) based on this new evidence.
Royalties are almost 100% gross margins, by the way.

$SPCB Another contract win, but the comments really caught my interest.
"We are proud to continue our 100% opportunity conversion rate with this new win in New York State," commented Ordan Trabelsi, President and CEO of SuperCom. "This new contract demonstrates New York State's continued adoption of SuperCom's solutions and builds on our 100% submitted RFP win rate in Europe this year. Our consistent wins across multiple regions reflect SuperCom's growing global recognition and the increasing demand for our solutions. "
$SPCB The price action here is strange. Down 1% on the news?
This alone probably added ~20% to H2'26 growth. Yes, it's mostly a one-time payment, but doesn't the market see the momentum this company is building with all these contracts / orders they are getting?

$SNWV I knew this was a risk, though I thought it was rather small. Anyway, it hurts and if this proposal goes through, or even partly, it changes my original thesis quite a lot, so I decided to sell most of my position until we get more clarity.
NFA


SpruceHill Capital retweeted

$SPCB Wins another contract, entering Georgia, its 18th state. The contract is via a service provider, rather than directly with the government and will facilitate the Company's expansion across the provider's entire network.
> The initial deployment is expected to be >2x larger than any former U.S. EM partnership since 2024
> Replaces a 15yr incumbent
> Expected deployment in Aug'26.
> Multi-solution cross-sell opportunity
The size of this deployment is notable. Every win is a notch in the belt and strengthens the outlook, especially going into FY27.
The YE'26 run-rate performance should look better than what will be reported and relative to Q1'26 and what Q2'26 comes in at.

Talkpool $TALK.ST keeps on executing. The stock surged 36% yesterday and is now up 180% since my initial pitch.
To be frank, I did sell a small chunk of my position recently, as I believe the market is finally starting to price in their growth story. However, the deal announced yesterday is a game-changer: a €10m contract over two years in Germany, which I expect to yield roughly 20% EBITDA margins. That translates to an additional €1m in EBITDA per year.
To put that into perspective, even after yesterday's rally, Talkpool’s market cap sits at just €12m. The valuation remains compelling, which is why I'm still holding a sizable 10% position. The only reason I trimmed was to reallocate capital into another high-conviction play where I see an more asymmetric risk-to-reward ratio right now. I believe there is still plenty of upside left here.

Has anyone mapped out how serious SolarCycle is as a competitor to $LODE? $68M raised and Georgia plant already running.