
web3 mastermind, degen, technical analyst, what i post can be a financial advise, if you believe in it, I dont !
Joined May 2011
- Tweets4.2K
- Following294
- Followers1.2K
- Likes483





Mubadala just signed with OpenAI and Inception42 to apply AI to "investment analysis, opportunity identification and risk assessment."
That was one of four Abu Dhabi agreements yesterday, and the one founders raising here should read twice.
I don't know how Mubadala will use it. But once big allocators put models on deal work, your data room has two readers.
The partner reads the story.
The model checks whether it adds up: deck revenue vs the monthly numbers, market size vs its source, cohorts vs the growth chart.
A human skims past a gap between slide 4 and tab 3 of the model. A machine won't.
My advice to founders raising in the Gulf next year: reconcile everything before you send the link. The clean companies will get faster answers.

Source: Abu Dhabi Media Office on the four OpenAI agreements (2 Nov), incl. the Mubadala/Inception42 investment-analysis agreement: mediaoffice.abudhabi/en/crow…
CNBC on the deals: cnbc.com/2026/11/02/openai-a…
Image: screenshot of the Abu Dhabi Media Office release (highlight ours).

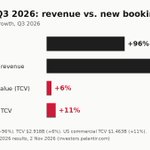
Palantir's revenue grew 96%. New contract value grew 6%.
US commercial revenue +148%. US commercial TCV +11%. Remaining deal value on that side +4% quarter on quarter.
The CFO's explanation: several 8-figure deals were shorter than usual because customers were rapidly adopting initial sovereign AI capabilities. He expects duration and size to grow over time. That may well happen.
But it's the same shape I see in enterprise AI pitches across the Gulf: big pilot cheques, 6–12 month terms, renewals still unproven.
So the question I ask those founders now: how much of your revenue is contracted beyond the next 12 months?
Fast revenue gets you the meeting. Contracted revenue gets you the term sheet.


$PLTR
PALANTIR SURPASSES $2B IN QUARTERLY REVENUE FOR THE FIRST TIME IN HISTORY.
- Revenue of $2.31B, +96% YoY
- U.S. Commercial Revenue $984M, +148% YoY
- U.S. Government Revenue $953M, +96% YoY
- $1.12B GAAP net income, 49% margin
- Net Dollar Retention 165%
- Rule of 40 Score 158%
- FY26 Revenue Guidance Raised to $8.53B
Palantir CEO Alex Karp:
"This moment, remarkable as it is for us, remains the first scene of a first act. It is our firm and unwavering intent to take the entire market, the whole thing. We think it is more likely than not that our raw concentration of creative and technical talent will continue to define the genre and craft the definitive story of software itself over the coming decades."
Speechless.

Source: Palantir Q3 2026 results (revenue $2.313B +96%, TCV $2.918B +6%, US commercial TCV $1.463B +11%, US commercial RDV +4% Q/Q): investors.palantir.com/news-…
CNBC on the results and the call: cnbc.com/2026/11/02/palantir…
Chart: our own, from Palantir's release.

OpenAI is about to call family offices. Some of those calls will come to the Gulf.
Per the FT and WSJ: it asked for $30B at a $1.4T valuation. About $11B is committed. The target is now up to $20B at $1.25T, and family offices and wealthy individuals come next.
The biggest cheque is expected from a UAE group including MGX, with an option for OpenAI to lease new compute in the region.
That's a strategic investor. It gets something besides shares.
A family office gets the shares only, at the same price where some large investors just cut their allocations.
If one asked me before signing, I'd want three answers:
Direct or SPV, and what fees sit on top?
What information rights come with it?
What happens to this mark if the next round or an IPO prices lower?
I'm not against late-stage AI. I'd pass on being the last money in at the institutional price without the institutional terms.

Sources: Reuters on the FT report (target cut to ~$20B at $1.25T, UAE consortium incl. MGX expected to be the largest participant, option to lease new compute in the region, later offering for wealthy individuals): channelnewsasia.com/business…
WSJ's ~$11B figure and the family-office push, via TNW: thenextweb.com/news/openai-f…
Chart: our own, from those reports. Round still open, figures may change.

The headline is 12%. The number I'd look at is zero.
SemiAnalysis says its finance and legal tasks are so hard that basically every model scores exactly 0 on the intended pass/fail grading.
The finance set is deal work inside a ~4,000-file replica of a private equity buyout: LBO models, earnouts, exit waterfalls, IC memos. One wrong key cell fails the task.
That's the work a VC or PE desk actually does.
So the "AI analyst that replaces your associate" decks we keep getting now face one question first: what's your pass rate when a single error fails the whole task?
What I'd rather fund is the layer that built this test. Every domain came from a specialist environment startup. Hard, private, expert-made tasks are scarce, and every lab needs them to train against.


Source: SemiAnalysis GDPx write-up (2 Nov), incl. the finance and legal grading notes: newsletter.semianalysis.com/…
Leaderboard and domains: gdpx.semianalysis.com/domain…

1/ The biggest MENA venture numbers this week weren't startup rounds. They were funds.
Tanmiya Capital Ventures: $130M final close
DPI's Nclude Fund: over $112M
BY Venture Partners Fund III: $60M
Phaze Ventures: two AI funds targeting $75M+, over $40M committed
What it means from a Dubai VC seat, in a short thread.

7/ My read for 2027: plenty of seed money, plenty of fund-level capital, and a squeeze between $5M and $25M.
If you're a founder here raising a seed round next year, plan how you get to the Series B before you take the seed money.
Sources: Arab News Startup Wrap (31 Oct): arabnews.com/startups/startu…
Wamda on BY Venture Partners Fund III: wamda.com/2026/10/venture-pa…
DPI on the Nclude Fund: dpi-llp.com/2026/10/27/dpi-v…
Cohere's Series E release: prnewswire.com/news-releases…
Aramco on closing the HUMAIN stake (1 Nov): aramco.com/en/news-media/new…
Chart: our own, from those figures.

Uber just showed what tokenized cash is actually for. Not trading. Weekends.
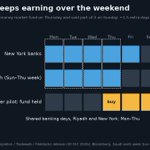
In a pilot with HSBC, Franklin Templeton, Tradeweb and Fireblocks, it used tokenized bank deposits to buy a tokenized money market fund on a Thursday, then sold part of it on a Sunday.
Normally that cash gets pulled before Friday's close. Per Bloomberg, this kept it earning about 1.5 extra days.
Small for Uber. Not small here.
A Saudi company paying in dollars works Sunday to Thursday. New York works Monday to Friday. That's four shared banking days a week, and treasuries hold idle buffers to cover the gap.
This is the tokenization pitch I'd fund: a bank on one side, a regulated fund on the other, a CFO as the buyer. In the Gulf, the first real users won't be crypto funds. They'll be treasurers.

HSBC / Franklin Templeton / Tradeweb / Fireblocks release on the Uber pilot (30 Oct): tradeweb.com/newsroom/media-…
CoinDesk on how it works: coindesk.com/business/2026/1…
Chart: our own, from the release and Bloomberg's report.
Amazon just printed its highest operating margin ever, 13.9%. The stock still sold off after hours.
Read the cash line, not the profit line.
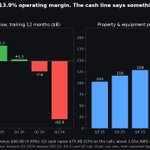
Free cash flow, last 12 months: −$42.4B. A year ago: +$14.8B.
Q3 cash capex: $75.9B, mostly AWS and AI. That's about 1.65x what AWS booked in revenue in the quarter.
Demand isn't the question. AWS grew 39% at a $184B run rate, its fastest in nearly five years.
Timing is. Jassy is guiding AWS growth above 40% in both 2027 and 2028. That's what the build has to earn back.
Public markets just showed how they price AI infrastructure: on when the cash comes back, not on whether demand exists.
If Amazon gets that scrutiny, an AI infra deal reaching a Gulf investor with one anchor tenant should get more.


BREAKING: Amazon stock, $AMZN, collapses over -12% after reporting weaker than expected Q3 earnings.
The stock has now erased -$315 billion worth of market cap in after hours trading.

Amazon Q3 2026 release (AWS +39%, TTM free cash flow, capex guide): ir.aboutamazon.com/news-rele…
CNBC on the print and the cash outflow: cnbc.com/2026/10/29/amazon-a…
Chart: our own, from Amazon's reported figures (Q3 cash capex from the earnings call).