A self-improving, decentralized AI network. Backed by @polychain @hiFramework @blockchaincap & more. Join the Community: https://xitter.cf/t.co/SewrB3pASi
Joined January 2024
- Tweets4.3K
- Following129
- Followers181K
- Likes5.1K




Pinned Tweet
New research from Dr. Diederik Kruijssen, our Chief Scientist @apo11o
“Genetic” AI mutation makes each model individually worse, but the population collectively better.
When conditions shift, best mutant model beats the best optimised one, four times in five.
Read more below:


Check out our full walkthrough for building a Hyperliquid 3-minute log return worker on Allora Forge, from raw Atlas candles to a running worker.
Bulk candles for ~178 perps in one request, labeled multi-asset submissions, and the bar alignment that keeps live inference matching training 👇
allora.network/blog/build-an…

Short-horizon returns are mostly noise, which makes this a good test of what a network of models can find together that no single model can.
Deploy yours on forge.allora.network/
Read more about the Hyperliquid Log Return topic: allora.network/blog/the-hype…

Short-horizon returns are mostly noise, which makes this a good test of what a network of models can find together that no single model can.
Deploy yours on forge.allora.network/
Learn more about Hyperliquid Log Return topic here allora.network/blog/the-hype…
Read more about “Flawed in Nature, Perfect through Evolution” here: allora.network/research/flaw…

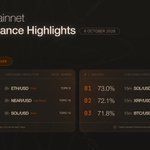
This week's network performance on Allora mainnet.
Top performing topics:
SOL 15min volatility, 73.0%
ETH 8h price, 61.2%
NEAR 8h log-return, 58.8%
Top-3 (price/returns):
1. Topic 9 (8h ethusd Price): 61.2%
2. Topic 19 (8h nearusd Log-return): 58.8%
3. Topic 10 (8h solusd Price): 56.2%
Top-3 (volatility):
1. Topic 23 (15min solusd Volatility): 73.0%
2. Topic 22 (15min xrpusd Volatility): 72.1%
3. Topic 20 (15min btcusd Volatility): 71.8%

We just published a step-by-step guide to building a triple-barrier worker for Gold, Silver, and Oil on Allora Forge.
It starts with real Hyperliquid price data and ends with your own model submitting live probabilities to the network.
Read more here: allora.network/blog/build-an…

Every hour, set a price ceiling, a price floor, and a 24-hour deadline, then predict whether the market hits the ceiling, the floor, or neither before time runs out.
That turns forecasting into a classification problem most ML models can handle.
New paper from Allora Research: the CZAR loss (Composite Zero-Agnostic Return) for financial return forecasting, led by @PebbleRustler with the Allora Research team.
Under a standard loss like the mean squared error, a model that gets the direction of a return right 58% of the time can score worse than one that always predicts zero. Expected returns are close to zero, so a symmetric loss makes "predict zero" nearly optimal, and models shrink their predictions toward it.
CZAR rewards directional decisiveness instead, with a floor on the loss for small moves so predicting zero can't look artificially good. The tradeoff is a deliberate bias, so its predictions shouldn't be read as expected returns.
It's the scoring loss for every log-return topic on Allora, and it's included in the open-source Forge Builder Kit.
Excited to announce a new paper from the @AlloraLabsHQ Research Team, on the interface between quant finance and AI. We present the CZAR Loss, a new loss function solving the zero-returns bias suffered by standard loss functions in financial forecasting.