

High-quality, research-backed financial analysis and practical lessons for intelligent investors. No clickbait, just rigorous, actionable insights.
Joined December 2025
- Tweets890
- Following263
- Followers945
- Likes908






Pinned Tweet
Our goal is to provide useful and practical information for the intelligent investor.
1. We provide financial content based on in-depth, thorough research. You won’t find hundreds of investment theses here, only those in which we actually believe are worth investing.
2. You'll find useful lessons from some of the greatest investors, along with case studies on their investments, not just quotes.
3. We provide a rigorous analysis of the current investment landscape, based on reliable sources, not clickbait.
anomalyinvestments.substack.…

Klarna decommissioned 1,200 external software tools, including Salesforce and Workday.
Employees replaced them by describing what they needed to an AI and getting bespoke internal tools back, keeping only the roughly 20% of functionality the bank actually used.
$FICO gets paid per score, not per loan. A standard mortgage pull carries three scores.
If the FHFA moves lenders from three credit reports to two, FICO sells a third fewer scores on every agency loan, whichever model lenders pick. We estimate $200M to $280M of revenue a year.
Not official yet.

FirstGroup is a £915m UK bus and rail operator with no pricing power and a 10% return on capital.
Our conservative case still returns about 18% a year. Halve the buyback and cut the exit multiple to 10x, and the worst case in our model is still 8%.
Why the floor is that high: anomalyinvestments.substack.…

From 2013 to 2018, Apple's free cash flow grew 7% a year. Free cash flow per share grew almost 13% a year. Buybacks added about 6% annually.
Over the last five years they added about 2.6%.
Same program. Different price per share.
Briggs & Stratton, an S&P 500 company, spun off Strattec, a business worth under $100M. Its institutional holders had no mandate to own it, so they sold.
Joel Greenblatt bought at $10.50 to $12 (about 9x earnings). In under eight months it was $18.
Kelly Partners Group:
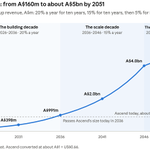
"First, the building decade does the heavy lifting. At 20% a year, revenue grows about six times, to about A$1bn by 2036.... By 2051 the path reaches about A$5.1bn, or about US$3.4bn.
Second, this is an honest ambition, not a stretch. Our plan for the next three years is 25% a year, and we have grown about 30% a year for twenty. Slowing to 20%, then 15%, then 5% assumes that size catches up with us, as it does with most businesses. Not with all of them: one of our heroes, Mark Leonard's Constellation Software, has found ways to keep growing at high rates long after most people expected its size to slow it down. We think we can do the same. But in this article we would rather be conservative, and be proved wrong on the upside.
Third, the pace of buying required is less than it looks. To grow 20% a year by joining, we need to add firms with about A$32m of revenue in FY2027, rising to about A$150m a year by the mid-2030s... Our plan needs us to bring in, each year for the next eight years, less than one platform bought in ten months..."

FirstGroup $FGP.L just sold five depots and 330 buses to the regional authority for £109m, and still won two franchise contracts there.
Our piece flagged exactly this risk: c.£250m of Regional Bus revenue sits in areas moving to franchising, and the market assumed that meant losing revenue and carrying more debt.
Instead, the authority is paying for the assets, FirstGroup keeps running the routes, and the revenue risk moves to the authority.
£109m is about 9% of the market cap. Management has also already bought back 27.5m shares for £49.8m, half of its £100m programme, at an average ~181p.
We built our base case at 170p. The stock is now 227p.
The full case: how contracted revenue goes from 42% to 62%, how we calculate owner earnings, and what buybacks do to the return math.
anomalyinvestments.substack.…

FirstGroup, a UK bus and rail operator, trades at about 13x earnings with a market cap of about £915m.
Its buybacks: £118m (2024), £92m (2025), £50m (2026), and £100m guided for FY2027. That is 11% of the company in one year, 15% with dividends. At £100m a year and a flat share price, diluted shares fall from about 575m to about 399m by 2029.
Contracted revenue is moving from about 42% to about 62% of the total.
What it lacks is pricing power. Return on capital is about 10%, and after losing Liverpool's franchising round on price, the CEO said: "We're not going to do franchising for nothing."
Our base case is a 9% yield on enterprise value by 2029, or about 18% annualized at a 12x multiple. If management hits its own guidance, 44%.
The return comes from cash generation and a shrinking share count, not from raising prices.
In a 1995 survey, 97% of Japanese managers said they would protect jobs before dividends.
In 2023 the Tokyo Stock Exchange launched a campaign aimed at companies trading below book value. Buyback authorizations went from 9.6 trillion yen (2023) to 18 trillion (2024).
TOPIX is up 147% since the start of 2023.
$CSGP Q3 numbers are better than the reaction, but the picture got murkier, not clearer.
The positives are a record adj. EBITDA ($229M), residential profitable for the first time, operating cash flow up from $268M to $455M YTD.
Overall, the business is clearly more efficient.
The red flags are not few though. Consolidated bookings are now down YoY two quarters in a row (-26%, then -56%). Management blames housing and sales capacity. Fair, but Zillow’s multifamily revenue grew +42% in Q2 while Apartments,com slowed to 6%. Maybe competition is creeping in?
The bigger one is capital allocation. The thesis was a shift from “build to harvest”, and that required buybacks to run hard as the stock fell. Instead, $505M at about $44/share in Q1, then $80M a quarter at $30, while $1.5B went to Zonda and Vexcel. Management says Vexcel beats a buyback by year two. Guess we’ll find out. Acquisition track record is good, so giving management the benefit of the doubt isn't unreasonable.
If that cash had gone to buybacks, the reaction would have been different. Not saying it should have. But the market wanted harvest evidence and got more build.
In 2015, Apple traded at 12x earnings and 10x free cash flow. Berkshire's average cost over 2016 to 2018 was about $40 a share (our estimate).
Free cash flow per share is now $9.2, a 23% yield on that cost.
Buy Apple today at $345 and the free cash flow yield is 2.7%.
$GOOG Alphabet's AI investment is obviously driving tremendous revenue growth. The key question however is how much of that growth also translates to profits and at what cost.
That's why return on capital is the variable to watch. Growth is great so long as it generates value, not for the sake of it.
So far, that relationship between dollar invested and profit generated is worsening. Perhaps it needs more time to show. How long will it take though? The longer it takes, the lower the IRR.
Unfortunately for Alphabet, regardless of returns on capital, the company has to committ to winning the AI battle or risk disappearing. It's a prisoners dilema.
What's impressive gowever is that return on capital remains above 20% despite the massive investments, which shows how good the rest of the business is.


Given nearly all growth in the last decade came from price increases, how much is FICO worth if price hikes get a ceiling?
About 90% of $FICO FICO's growth in the last decade came from price hikes. Stock is down over 60%.
Competition has increased thanks to regulators, likely putting pressure on price increases.
How much is the firm worth if price power is diminished?
