

India First | Investing | FIRE | All Views are Personal | No Recommendation.
📖 Learning Hub 👉🏻
Joined March 2014
- Tweets41.1K
- Following516
- Followers37.3K
- Likes84.4K






Pinned Tweet
Wow, such a wonderful gift 🎁 on a Saturday morning. Many thanks for the follow, 👑 @LuckyInvest_ARK Ashish sir. 😎 🤩😇🎉
It certainly means a lot and pushes me to put in the time to add more valuable, productive content to the equity investors community, sir.
✍️ Your indispensable knowledge in picking stocks and sound research have always inspired in my investment journey, sir.
It's such an honor, sir.. I'm grateful and truly humbled. 🙏🏻🙏🏻

🔬 Kwick Forensic Solutions Limited received two orders worth ₹2.53 Crore.
▪️ Client: Forensic Science Department, Chennai
▪️ Order Value: ₹2.53 Crores (including GST)
▪️ Scope: Supply of Genetic Analysers with accessories & kits (for Regional FSLs in Tirunelveli & Coimbatore)
▪️ Execution Timeline: 3 months (by 04/02/2027)
ℹ️ For educational purposes only. Not a recommendation. DYODD.


🔬 Kwick Forensic Solutions: Decoding India’s Next Big Forensic Tech Powerhouse
Kwick Forensic Solutions Ltd is positioning itself as a key beneficiary of India’s push for indigenous forensic science, cyber investigation, and evidence-management technologies under the Make in India initiative.
Here are the key takeaways from their Investor Presentation 🧵👇
1️⃣ Company Snapshot
📍 Headquarters: Chennai (Est. 2005; 20+ years of domain experience).
🛠 Scale: 200+ products, 12+ global OEM partnerships, and 130+ government/institutional clients across India.
🏢 R&D First: In-house DSIR-recognized R&D center & dedicated Private Forensic Lab PoC.
💰 Financial Health: Fully Debt-Free balance sheet.
2️⃣ Diversified Business Verticals
37% – Forensic Science & Physical Evidence Solutions (Kwick Vision Pro, multispectral tools, fuming chambers, crime scene kits).
33% – Cyber & Digital Forensics (Falcon Neo-2 Imager, Detego Triage Kits, Write Blockers).
11% – DNA Forensics (RapidHIT ID System with <90 min profiling, SmallPond software).
10% – Mobile Forensic Vans (25 CSI vehicles delivered to date).
9% – Services, Leasing & AMC (Hand-held X-Ray contraband detectors, 24x7 support).
3️⃣ Indigenous R&D Focus
Kwick is replacing imported gear with internally developed products:
Kwick Vision Pro for latent fingerprints & footwear impression analysis.
Kwick Lite-Pro portable light source for fluid detection & document verification.
Digital Optical Comparators & controlled laboratory processing chambers.
4️⃣ The Next Big Trigger: E-Forensics Suite
An integrated end-to-end digital evidence platform (Crime Scene ➡️ Courtroom) featuring:
Digital chain of custody & secure data encryption.
3D crime scene sketching & audio/video statement recording.
Built-in legal reference tools (BNSS compliance) & judicial support tools.
5️⃣ Massive Sector Tailwinds & Govt Push
📊 Market Growth: India’s Digital Forensics market projected to surge from $0.19B (₹1,603 Cr) in 2024 to $1.39B (₹11,829 Cr) by 2030 (~40% CAGR).
🏛 Government Investments:
₹30,000 Cr planned for national forensic lab network expansion.
₹2,254 Cr outlay under the NFIES scheme (FY25–FY29).
₹1,852 Cr allocated for DNA & cyber forensic upgrades.
Approval for 433 Mobile Forensic Vans across 23 States/UTs.
Target to deploy 35,000 forensic experts by 2029.
6️⃣ Regulatory Catalysts
Forensic examination is now mandatory for offences punishable by 7+ years.
Mandatory videography for search & seizure operations under new procedural frameworks.
Clear legal admissibility for digital evidence and e-FIR provisions.
💡 The Bottom Line: With strong macro tailwinds, mandatory legislative requirements, and a debt-free balance sheet, Kwick Forensic Solutions is well-positioned in India's growing forensic tech market.
🚫 No Recommendation.

INDIAN AEROSPACE & DEFENCE 🚀
Companies posting over 50% Profit Growth in Q2FY27
▪️ Apollo Micro Systems – PAT up 53% YoY (₹46 Cr vs ₹30 Cr)
▪️ Unimech Aerospace and Manufacturing – PAT up 100% YoY (₹32 Cr vs ₹16 Cr)
▪️ Solar Industries India – PAT up 80% YoY (₹650 Cr vs ₹361 Cr)
▪️ Krishna Defence & Allied Industries – PAT up 67% YoY (₹15 Cr vs ₹9 Cr)
▪️ Zen Technologies – PAT up 65% YoY (₹102 Cr vs ₹62 Cr)
▪️ Paras Defence and Space Technologies – PAT up 63% YoY (₹31 Cr vs ₹19 Cr)
▪️ Avantel – PAT up 59% YoY (₹6.81 Cr vs ₹4.27 Cr)
▪️ Ideaforge Technology – Turned profitable at ₹6.46 Cr (vs loss of ₹19.62 Cr)
Educational purpose only. Not a buy/sell recommendation. DYODD.

🚀 Merritronix Limited - Investor Presentation Highlights
Merritronix reported strong growth driven by its mission-critical defence and aerospace electronics capabilities.
🔲 Key Highlights:
▪️ Financial Growth: FY26 Revenue at ₹155.9 Cr (+37.2% YoY), EBITDA Margin up at 17.42%, and PAT at ₹16.1 Cr (+86% YoY).
▪️ Robust Pipeline: Order book stands at ₹98.06 Cr as of June 30, 2026.
▪️ Core Strength: Aerospace & Defence drives ~97.8% of total revenue.
▪️ Capacity Boost: New Panasonic SMT line added, bringing annual installed capacity to ~2.1 million units.
▪️ Strategic Partnerships: Recent MoUs signed with Analinear Design & Stuam Technologies.
🚫 No Recommendation. DYODD.

The Indian Investor retweeted
🔋 India’s BESS Megatrend: 7X Growth by FY32 ⚡️
✅ Capacity projection: 34.7 GWh ➡️ 236 GWh
✅ Potential Investment: ₹3.49 Lakh Crore 📈
The Battery Energy Storage Systems (BESS) expansion is not just about battery cells - it covers power electronics, transformers, grid infra, EPC, and renewable energy.
🗒️ 27 Companies to Track Across the BESS Ecosystem
▪️ Waaree Energies
▪️ Exide Industries
▪️ Amara Raja Energy & Mobility
▪️ Premier Energies
▪️ Vikram Solar
▪️ HBL Engineering
▪️ Hitachi Energy India
▪️ Siemens
▪️ JSW Energy
▪️ Quality Power
▪️ Pace Digitek
▪️ Himadri Speciality Chemical
▪️ Neogen Chemicals
▪️ Advait Energy Transitions
▪️ Godawari Power & Ispat
▪️ Oriana Power
▪️ SPML Infra
▪️ Prostarm Info Systems
▪️ PCBL
▪️ HEG Advanced Materials
▪️ ACME Solar
▪️ KPI Green Energy
▪️ K.P. Energy
▪️ GP Eco Solutions
▪️ Maxvolt Energy
▪️ CLN Energy
▪️ Bondada Engineering
🔀 How BESS Proxy Plays Breakdown Across Sectors:
🔹 Batteries & Chemical Inputs: Exide, Amara Raja, HBL, Himadri, Neogen, PCBL, HEG Advanced Materials, Maxvolt Energy, CLN Energy.
🔹 Solar, Modules & Cell Mfrs: Waaree Energies, Premier Energies, Vikram Solar, ACME Solar.
🔹 Power Electronics & Transformers: Hitachi Energy, Siemens, Quality Power, Prostarm Info Systems, Pace Digitek.
🔹 EPC, Grid & Utilities: JSW Energy, KPI Green, K.P. Energy, Oriana Power, Bondada Eng, Advait Energy, Godawari Power, SPML Infra, GP Eco Solutions.
The Bottom Line 💡
A booming sector doesn't guarantee booming returns.
Before investing, track key metrics:
⚠️ Valuations & P/E multiples
📊 Order-book execution
📉 Profit margins & debt
💵 Sustainable cash flows
Demand is coming - focus on execution leaders.
🚫 For educational purposes only. Not a buy/sell recommendation. DYODD.

🔥 Bulls are back in charge 🚀
📈 Sensex ↑ 2,000+ pts | Nifty ↑ 570+ pts
Key drivers behind the stellar rally:
🛢️ Crude oil hitting a 2-month low
💵 Sustained FII buying momentum
🌍 Strong global cues & positive Wall Street sentiment
#Nifty #Nifty50 #Sensex #Investing

📊 JP Morgan is bullish on 35+ Indian stocks.
Here is the overweight list broken down by sector 👇🏻
🔲 Financials (13)
▪️ ICICI Bank
▪️ SBI
▪️ Bajaj Finance
▪️ AU Small Finance Bank
▪️ PNB
▪️ Angel One
▪️ Nippon AMC
▪️ NSE
▪️ PNB Housing
▪️ IIFL Finance
▪️ Muthoot Finance
▪️ HDFC Life
▪️ ICICI Lombard
🔲 Consumer Discretionary (7)
▪️ Titan
▪️ TVS Motor
▪️ Tata Motors
▪️ Eternal
▪️ Lenskart
▪️ Exide
▪️ Samvardhana Motherson
🔲 Industrials (7)
▪️ L&T
▪️ NTPC
▪️ Adani Ports
▪️ Bharat Electronics
▪️ Polycab
▪️ Hitachi Energy
▪️ GE Vernova T&D
🔲 Health Care (7)
▪️ Apollo Hospitals
▪️ Max Healthcare
▪️ Fortis
▪️ Divi's Labs
▪️ Cipla
▪️ Torrent Pharma
▪️ Anthem Biosciences
🔲 Materials (2)
▪️ JSW Steel
▪️ Pidilite
(Note: IT sector is currently being avoided).
🚫 For educational purposes only. Not a recommendation. DYODD.

🪔 65 Diwali Stock Picks for Samvat 2083 from leading brokerages 📈
As we welcome Samvat 2083, here are the top fundamental and technical stock recommendations curated from leading brokerages (SBI Securities, Mirae Asset Sharekhan, PL Capital, Nirmal Bang, Arihant Capital, and Motilal Oswal) 👇🏻
🔲 Motilal Oswal
▪️ Kotak Mahindra Bank
▪️ Adani Ports and Logistics
▪️ Titan Company Ltd
▪️ Eternal Ltd
▪️ BSE Ltd
▪️ SPR Auto Technologies Ltd
▪️ Shaily Engineering
▪️ Arvind Ltd
▪️ Unimech Aerospace
▪️ Symbiotec Pharmalab
🔲 Mirae Asset Sharekhan
▪️ Bharti Airtel Ltd
▪️ ICICI Bank Ltd
▪️ Larsen & Toubro Ltd
▪️ Titan Company Ltd
▪️ UltraTech Cement Ltd
▪️ Indian Hotels Company Ltd (IHCL)
▪️ Navin Fluorine International Ltd
▪️ Welspun Corp Ltd
▪️ Tata Consumer Products Ltd
▪️ Radico Khaitan Ltd
▪️ Dee Development Engineers Ltd
▪️ Karnataka Bank Ltd
▪️ Lumax Auto Technologies Ltd
▪️ Sagility Ltd
▪️ VA Tech Wabag Ltd
🔲 SBI Securities (SBICAP Securities)
▪️ Tata Steel Ltd
▪️ Indian Hotels Company Ltd
▪️ Multi Commodity Exchange of India Ltd
▪️ Jyoti CNC Automation Ltd
▪️ Sky Gold & Diamonds Ltd
▪️ Genus Power Infrastructures Ltd
▪️ Power Mech Projects Ltd
▪️ Centum Electronics Ltd
▪️ Stylam Industries Ltd
▪️ Sambhv Steel Tubes Ltd
▪️ Lumax Industries Ltd
🔲 PL Capital (Prabhudas Lilladher)
▪️ Apollo Hospitals
▪️ DLF Ltd
▪️ GE Vernova T&D India
▪️ HBL Engineering Ltd
▪️ Jindal Steel Ltd
▪️ Marine Electricals Ltd
▪️ Shilpa Medicare Ltd
▪️ Syrma SGS Technology Ltd
▪️ Transformers and Rectifiers (India) Ltd (TARIL)
▪️ TD Power Systems Ltd
🔲 Nirmal Bang
▪️ Axis Bank Ltd
▪️ Eternal Ltd (Zomato/Blinkit)
▪️ One 97 Communications Ltd (Paytm)
▪️ Prince Pipes Ltd
▪️ Rentomojo Ltd
▪️ SG Finserve Ltd
▪️ Tata Consumer Products Ltd
▪️ Ultratech Cement Ltd
🔲 Arihant Capital
▪️ Sammaan Capital Ltd
▪️ HFCL Ltd
▪️ Sheela Foam Ltd
▪️ Raymond Realty Ltd
▪️ GMM Pfaudler Ltd
▪️ Inox Wind Ltd
▪️ C.E. Info Systems Ltd (MapmyIndia)
▪️ KPIT Technologies Ltd
▪️ Raymond Lifestyle Ltd
▪️ Texmaco Rail & Engineering Ltd
▪️ Nuvoco Vistas Corporation Ltd
▪️ Sudarshan Chemical Industries Ltd
▪️ HEG Advanced Materials Ltd
▪️ Vindhya Telelinks Ltd
▪️ Exide Industries Ltd
▪️ Kirloskar Pneumatic Company Ltd
⚠️ Educational purposes only. No Buy/Sell Recommendation. DYODD.
Wishing you a prosperous Samvat 2083! 🎆

📊 Samvat 2083 Picks from 5paisa
▪️ Reliance Industries
▪️ Kotak Mahindra Bank
▪️ Eternal (Zomato)
▪️ The Indian Hotels Company (IHCL)
▪️ ITC Limited
▪️ Laurus Labs
▪️ HDFC Bank
▪️ TVS Motor Company
▪️ Hindustan Aeronautics (HAL)
▪️ Dr. Reddy's Laboratories
Disclaimer: For educational and analytical purposes only. Not financial advice. Please do your own due diligence before investing.

🪔 65 Diwali Stock Picks for Samvat 2083 from leading brokerages 📈
As we welcome Samvat 2083, here are the top fundamental and technical stock recommendations curated from leading brokerages (SBI Securities, Mirae Asset Sharekhan, PL Capital, Nirmal Bang, Arihant Capital, and Motilal Oswal) 👇🏻
🔲 Motilal Oswal
▪️ Kotak Mahindra Bank
▪️ Adani Ports and Logistics
▪️ Titan Company Ltd
▪️ Eternal Ltd
▪️ BSE Ltd
▪️ SPR Auto Technologies Ltd
▪️ Shaily Engineering
▪️ Arvind Ltd
▪️ Unimech Aerospace
▪️ Symbiotec Pharmalab
🔲 Mirae Asset Sharekhan
▪️ Bharti Airtel Ltd
▪️ ICICI Bank Ltd
▪️ Larsen & Toubro Ltd
▪️ Titan Company Ltd
▪️ UltraTech Cement Ltd
▪️ Indian Hotels Company Ltd (IHCL)
▪️ Navin Fluorine International Ltd
▪️ Welspun Corp Ltd
▪️ Tata Consumer Products Ltd
▪️ Radico Khaitan Ltd
▪️ Dee Development Engineers Ltd
▪️ Karnataka Bank Ltd
▪️ Lumax Auto Technologies Ltd
▪️ Sagility Ltd
▪️ VA Tech Wabag Ltd
🔲 SBI Securities (SBICAP Securities)
▪️ Tata Steel Ltd
▪️ Indian Hotels Company Ltd
▪️ Multi Commodity Exchange of India Ltd
▪️ Jyoti CNC Automation Ltd
▪️ Sky Gold & Diamonds Ltd
▪️ Genus Power Infrastructures Ltd
▪️ Power Mech Projects Ltd
▪️ Centum Electronics Ltd
▪️ Stylam Industries Ltd
▪️ Sambhv Steel Tubes Ltd
▪️ Lumax Industries Ltd
🔲 PL Capital (Prabhudas Lilladher)
▪️ Apollo Hospitals
▪️ DLF Ltd
▪️ GE Vernova T&D India
▪️ HBL Engineering Ltd
▪️ Jindal Steel Ltd
▪️ Marine Electricals Ltd
▪️ Shilpa Medicare Ltd
▪️ Syrma SGS Technology Ltd
▪️ Transformers and Rectifiers (India) Ltd (TARIL)
▪️ TD Power Systems Ltd
🔲 Nirmal Bang
▪️ Axis Bank Ltd
▪️ Eternal Ltd (Zomato/Blinkit)
▪️ One 97 Communications Ltd (Paytm)
▪️ Prince Pipes Ltd
▪️ Rentomojo Ltd
▪️ SG Finserve Ltd
▪️ Tata Consumer Products Ltd
▪️ Ultratech Cement Ltd
🔲 Arihant Capital
▪️ Sammaan Capital Ltd
▪️ HFCL Ltd
▪️ Sheela Foam Ltd
▪️ Raymond Realty Ltd
▪️ GMM Pfaudler Ltd
▪️ Inox Wind Ltd
▪️ C.E. Info Systems Ltd (MapmyIndia)
▪️ KPIT Technologies Ltd
▪️ Raymond Lifestyle Ltd
▪️ Texmaco Rail & Engineering Ltd
▪️ Nuvoco Vistas Corporation Ltd
▪️ Sudarshan Chemical Industries Ltd
▪️ HEG Advanced Materials Ltd
▪️ Vindhya Telelinks Ltd
▪️ Exide Industries Ltd
▪️ Kirloskar Pneumatic Company Ltd
⚠️ Educational purposes only. No Buy/Sell Recommendation. DYODD.
Wishing you a prosperous Samvat 2083! 🎆
The Indian Investor retweeted

KRN HEAT EXCHANGER – Q2 FY27 2 MINUTES CONCALL READ 🔥🔥🔥
➡️ REVENUE GUIDANCE & GROWTH OUTLOOK
▪️ Management indicated that FY27 revenue could exceed the earlier ₹1,200 crore guidance and potentially reach approximately ₹1,250 crore, subject to external factors.
▪️ Export revenue guidance has been increased from around ₹200 crore to approximately ₹250 crore for FY27.
▪️ Management expects at least 30% growth beyond the current year, supported by exports, data centres, automotive, railways and new product segments.
➡️ EXPORT BUSINESS
▪️ Exports nearly tripled during H1 FY27 and contributed approximately 22% of total revenue.
▪️ The US is the largest export market, followed by Canada, France, the UK and Italy. The company also serves markets including UAE, Vietnam, Sri Lanka, Brazil and Nepal.
▪️ Management is targeting 50% export contribution in the fin-and-tube heat exchanger segment by FY28. This is not a target for total company revenue.
▪️ Export customers generally offer 4–5 percentage points higher EBITDA margins than domestic customers, before freight costs.
➡️ CAPACITY EXPANSION & UTILISATION
▪️ KRN operates two major manufacturing facilities at Neemrana, Rajasthan:
Plant I – KRN Heat Exchanger: Total land area of 1,04,948 sq. ft.
Plant II – KRN HVAC Products (wholly owned subsidiary): Total land area of 8,40,128 sq. ft.
▪️ Plant II is approximately eight times larger in land area than Plant I. These figures represent total land area, not built-up factory area.
▪️ The company's website lists annual fin-and-tube production capacity of approximately 10 lakh units at Plant I and 40 lakh units at Plant II.
▪️ Plant I is already operating at near-full utilisation. Plant II is being ramped up, with management targeting approximately 50% utilisation in FY27 and 80% in FY28.
▪️ The new facility supports a wider product portfolio, including fin-and-tube and bar-and-plate heat exchangers, refrigeration components and complete HVAC solutions.
▪️ An analyst referred to approximately ₹1,800 crore revenue potential at 100% utilisation of Plant II. Management did not independently confirm this figure during the call, noting that revenue potential also depends on metal prices.
▪️ Management is also planning a facility in Bengaluru/South India to support future expansion. No specific investment amount or commissioning timeline was disclosed during the call.
➡️ ORDER BOOK & ORDER INFLOWS
▪️ The company follows a rolling order-book model, with orders coming continuously from its customers. Management did not disclose a consolidated order-book figure.
▪️ Demand remains healthy across heat exchangers, data centres, exports, bus air-conditioning and industrial cooling, supporting ongoing order inflows.
➡️ DATA CENTRE OPPORTUNITY
▪️ Data-centre business contributed approximately ₹180 crore during H1 FY27, compared with around ₹38 crore in H1 FY26.
▪️ The company has onboarded domestic and international customers. Some domestic customers are single-sourcing from KRN, while others are allocating 50–60% of their requirements.
▪️ Export data-centre orders exceeded ₹50 crore at the time of the call, with customers generally placing rolling orders covering 1–2 months.
▪️ KRN is developing bridge-plate heat exchangers for liquid-cooling applications. Development is expected to take around 1.5 years, with commercial revenue potentially starting around FY29.
➡️ AUTOMOTIVE & BUS AIR-CONDITIONING
▪️ The Indian bus air-conditioning market is estimated at approximately ₹1,000 crore, growing at 25–30%, with electric buses driving demand.
▪️ KRN has commenced supplies to an OEM and added several bus bodybuilders as customers. It is engaging with additional OEMs for approvals, particularly in electric buses.
▪️ Management indicated that the company is currently slightly below its earlier 15% market-share ambition and expects better visibility on progress by Q3.
▪️ In-house heat exchanger tubing and FRP capabilities provide backward integration for this business.
▪️ The company is also working on local development of compressors for bus air-conditioning systems.
➡️ RAILWAY BUSINESS
▪️ Prototype development for railway air-conditioning systems has been completed. The company is pursuing the required plant approval to participate in railway tenders.
▪️ Initial focus will be on driver-cab AC systems, followed by LHB coaches, Vande Bharat trains and Metro projects.
▪️ Management expects approximately ₹20 crore revenue from railway HVAC systems next year.
➡️ PRODUCT PORTFOLIO EXPANSION
▪️ KRN is expanding beyond fin-and-tube heat exchangers into bar-and-plate heat exchangers, refrigeration components and complete HVAC systems.
▪️ New product categories include dry air coolers, open-top condensers, adiabatic coolers, remote radiators and cold-storage solutions.
▪️ Bar-and-plate heat exchangers, bus AC systems and complete HVAC solutions offer opportunities for a better product mix and higher margins.
▪️ More than 30 new customers were added across product segments during the previous quarter.
➡️ TECHNOLOGY & TESTING CAPABILITIES
▪️ The Thermotech Research Laboratory has started internal testing, supporting product validation, performance testing and value engineering.
▪️ The facility can help optimise designs and reduce copper consumption while maintaining product performance.
▪️ NABL certification was expected within 4–5 weeks of the call, followed by HRI certification. External testing services could commence 2–3 months after the required certifications.
➡️ WORKING CAPITAL & RAW MATERIALS
▪️ To manage new BIS requirements for copper tubes, the company has increased inventory, is developing domestic suppliers and plans to use advance licences for export-related sourcing.
▪️ Management stated that changes in copper, aluminium and stainless-steel prices are generally passed on to customers through quarterly price revisions.
▪️ SAP-based inventory monitoring, export factoring and buyer's credit for imports are among the measures being implemented to improve working-capital efficiency.
▪️ Management expects working-capital and cash-flow improvement by the end of FY27.
➡️ MARGIN OUTLOOK
▪️ Management indicated FY27 EBITDA margin guidance of approximately 17–18%, with a medium-to-long-term margin ambition of 18–20%.
▪️ Near-term margins are affected by higher export freight costs, metal prices and certain customer-specific pricing arrangements.
▪️ Management expects Q3 margins to remain broadly similar, with potential improvement in Q4 through higher volumes, operating leverage and a better export mix.
➡️ KEY MONITORABLES
▪️ Nimrana utilisation and progress on the Bengaluru facility.
▪️ Export growth and achievement of the FY28 export-mix target.
▪️ Data-centre order inflows and liquid-cooling product development.
▪️ Electric bus OEM approvals and railway plant certification.
▪️ Commercialisation of new products and improvement in working capital.
Disclaimer:
For educational purposes only. Not a buy/sell recommendation. DYDD.


KRN HEAT EXCHANGER – Q2 & H1 FY27 INVESTOR HIGHLIGHTS ❄️🧊
About the company
▪️ KRN caters to multiple industries, including HVAC, refrigeration, data centres, automotive, railways, industrial cooling, process applications, power and marine.
▪️ The company focuses on customised product development, precision engineering, integrated manufacturing, testing and quality control.
Data centre cooling – an important growth opportunity
▪️ Management highlighted data centre cooling as an important emerging growth engine for KRN.
▪️ New customers in the data centre segment have started working with the company.
▪️ Customers are planning their requirements and placing orders well in advance, providing better visibility for future business.
▪️ KRN's existing Fin & Tube product portfolio includes solutions for data centres, server rooms, precision air conditioning and CRAC units.
▪️ The company is also developing products for liquid cooling as data centre cooling technology evolves towards this solution.
▪️ Increasing demand for data centres and associated thermal-management infrastructure could create opportunities across the company's cooling product portfolio.
Bus AC business – new growth segment
▪️ During 2025–26, KRN established its wholly owned subsidiary, KRN HVAC Products Private Limited, and acquired the Bus AC division of Sphere Refrigeration Systems.
▪️ The acquisition expands the company's presence into bus air-conditioning solutions.
▪️ Management confirmed that supplies to an OEM have commenced.
▪️ The company is gradually adding more customers in this segment.
▪️ Its product portfolio includes electric bus AC and conventional bus AC systems, catering to city, school, staff and electric buses.
Exports and international presence
▪️ KRN has an established export presence across North America, Europe, the UAE and other international markets.
Export contribution to total revenue:
▪️ FY24 – 14.68%
▪️ FY25 – 15.69%
▪️ FY26 – 16.57%
▪️ H1 FY27 – 22.01%
▪️ Domestic sales contributed 77.99% of H1 FY27 revenue, while exports contributed 22.01%.
▪️ H1 FY27 country-wise export revenue distribution:
▪️ USA – 43.75%
▪️ Canada – 12.82%
▪️ France – 12.67%
▪️ UK – 7.93%
▪️ Italy – 7.65%
▪️ Others – 15.19%
▪️ Management stated that exports have grown several times over the first half of FY27, with increased business from customers in North America and Europe.
Certifications and competitive positioning
▪️ The company holds multiple quality and compliance certifications supporting its domestic and international operations.
▪️ Key certifications include CE, IMS, ZED Silver, EN ISO 15609-1:2019, ISO 9606-1:2017, BS EN ISO 13134, BS EN ISO 13535, AHRI, UL 207 and IS 11329:2018.
▪️ KRN has received recognition from global industry participants, including Carrier, Daikin, Honeywell and Schneider Electric.
Management outlook and growth strategy
▪️ Management described H1 FY27 as a strong period, with growth across customers, products and geographies.
▪️ Expanded manufacturing capabilities at Neemrana are expected to support larger customer programmes.
▪️ The company is continuing to qualify more customers and widen its product portfolio.
▪️ Management sees opportunities across data centres, infrastructure, mobility and industrial cooling.
▪️ Data centre cooling is becoming an important growth engine, with customers planning and placing orders well in advance.
▪️ Liquid cooling product development is another area the company is working on.
▪️ In the Bus AC segment, supplies have commenced to an OEM, and the company is working on adding more customers.
▪️ Management remains optimistic about the opportunities ahead and is strengthening its teams and systems to support expansion.
KRN is expanding beyond its traditional heat exchanger business into a broader HVAC&R solutions platform.
Data centre cooling, liquid cooling development, exports and the newly added Bus AC business provide multiple potential growth avenues. Its wider product portfolio, manufacturing infrastructure and international customer relationships are important strengths to track.
For educational purposes only. Not a buy/sell recommendation. Please do your own research before making any investment decisions. DYDD.

🔋 India’s BESS Megatrend: 7X Growth by FY32 ⚡️
✅ Capacity projection: 34.7 GWh ➡️ 236 GWh
✅ Potential Investment: ₹3.49 Lakh Crore 📈
The Battery Energy Storage Systems (BESS) expansion is not just about battery cells - it covers power electronics, transformers, grid infra, EPC, and renewable energy.
🗒️ 27 Companies to Track Across the BESS Ecosystem
▪️ Waaree Energies
▪️ Exide Industries
▪️ Amara Raja Energy & Mobility
▪️ Premier Energies
▪️ Vikram Solar
▪️ HBL Engineering
▪️ Hitachi Energy India
▪️ Siemens
▪️ JSW Energy
▪️ Quality Power
▪️ Pace Digitek
▪️ Himadri Speciality Chemical
▪️ Neogen Chemicals
▪️ Advait Energy Transitions
▪️ Godawari Power & Ispat
▪️ Oriana Power
▪️ SPML Infra
▪️ Prostarm Info Systems
▪️ PCBL
▪️ HEG Advanced Materials
▪️ ACME Solar
▪️ KPI Green Energy
▪️ K.P. Energy
▪️ GP Eco Solutions
▪️ Maxvolt Energy
▪️ CLN Energy
▪️ Bondada Engineering
🔀 How BESS Proxy Plays Breakdown Across Sectors:
🔹 Batteries & Chemical Inputs: Exide, Amara Raja, HBL, Himadri, Neogen, PCBL, HEG Advanced Materials, Maxvolt Energy, CLN Energy.
🔹 Solar, Modules & Cell Mfrs: Waaree Energies, Premier Energies, Vikram Solar, ACME Solar.
🔹 Power Electronics & Transformers: Hitachi Energy, Siemens, Quality Power, Prostarm Info Systems, Pace Digitek.
🔹 EPC, Grid & Utilities: JSW Energy, KPI Green, K.P. Energy, Oriana Power, Bondada Eng, Advait Energy, Godawari Power, SPML Infra, GP Eco Solutions.
The Bottom Line 💡
A booming sector doesn't guarantee booming returns.
Before investing, track key metrics:
⚠️ Valuations & P/E multiples
📊 Order-book execution
📉 Profit margins & debt
💵 Sustainable cash flows
Demand is coming - focus on execution leaders.
🚫 For educational purposes only. Not a buy/sell recommendation. DYODD.
🚨 Gift Nifty +400 🔥
All global markets started celebrating as if the entire world had gained freedom from that one and only 🇺🇸 🤡 👿

The Indian Investor retweeted
COMPANIES THAT REPORTED MORE THAN 100% YOY SALES GROWTH IN Q2 FY27 🔥🔥🔥
▪️ E2E Networks – 411%
▪️ Netweb Technologies – 336%
▪️ SPARC – 282%
▪️ MTAR Technologies – 200%
▪️ Innovassynth Technologies – 175%
▪️ Asian Energy Services – 161%
▪️ Prizor Viztech – 154%
▪️ Sterlite Technologies – 145%
▪️ HEG Advanced Materials – 144%
▪️ HFCL – 144%
▪️ Viviana Power – 141%
▪️ Kolte-Patil Developers – 141%
▪️ Juniper Green Energy – 136%
▪️ Diamond Power Infrastructure – 134%
▪️ Trishakti Industries – 133%
▪️ Madhusudan Masala – 118%
▪️ Antelopus Selan Energy – 116%
▪️ SG Finserve – 116%
▪️ Multi Commodity Exchange (MCX) – 114%
▪️ SBC Exports – 113%
▪️ Kanohar Electricals – 112%
▪️ Bharat Parenterals – 111%
▪️ KRN Heat Exchanger – 110%
▪️ Accretion Nutraved – 109%
▪️ Infinity Infoway – 106%
▪️ T N Petro Products – 105%
▪️ SEAMEC – 103%
▪️ Anlon Healthcare – 102%
▪️ Sathlokhar Systems – 100%
Good numbers attract attention. Consistent execution creates long-term value.
Have I missed any company that reported more than 100% YoY sales growth in Q2 FY27? Mention it in the comments below.
Disclaimer:
This list is based on the quarterly figures shown in the shared screenshots. For educational purposes only. Not a buy/sell recommendation.

The Indian Investor retweeted
SHREE REFRIGERATIONS – H1 FY27 CONCALL 3-4 MINUTES READ 🥶❄️🧊
GUIDANCE & GROWTH
▪️ Management reiterated its 40% revenue growth CAGR guidance and expressed confidence in sustaining this growth trajectory.
▪️ Management stated that the existing manufacturing capacity is sufficient to support the current growth guidance. Capacity can be expanded further as and when new opportunities arise.
▪️ Around 8 orders/opportunities are in the pipeline. Management expects order inflows during H2 to support its growth guidance.
EBITDA MARGIN GUIDANCE
▪️ FY27 EBITDA margin guidance retained at around 22%.
▪️ Management expects H2 margins to be better than H1, supported by higher delivery volumes, improved fixed-cost absorption and a favourable product mix.
▪️ Naval project deliveries are generally weighted towards the second half because of shipbuilding schedules.
▪️ The margin and revenue mix is expected to become less seasonal as the contribution from new builds, retrofits, spares and services increases.
They indicated that this normalisation could take another 2–3 years.
ORDER BOOK & ORDER INFLOWS
▪️ Order book stood at approximately ₹198.6–200 crore as of September 2026, compared with around ₹270 crore at the beginning of FY27.
▪️ Naval platform orders generally come between August and February/March. Management expects orders to continue coming in during H2 and is confident of maintaining a healthy year-end order book.
▪️ The company has around 10 ongoing live projects, including turnkey projects involving HVAC, AC plants and refrigeration plants.
▪️ Fleet Support Ship is an important project where the company is supplying an integrated HVAC, AC and refrigeration solution. They described its refrigeration plant as the largest ever procured by the Indian Navy.
DEFENCE PIPELINE & UPCOMING PROGRAMMES
▪️ Next Generation Corvettes (NGC): Management expects to be closely associated with the programme. Some enquiries may convert into firm orders during FY27, with further orders potentially coming in FY28.
▪️ P75I submarine programme: The company is already working with Mazagon Dock Shipbuilders (MDL) on solutions and is awaiting the required government sanction.
▪️ Management also highlighted opportunities from the ongoing naval shipbuilding cycle, with HVAC and cooling equipment generally required during the early stages of ship construction.
MARKET OPPORTUNITY
▪️ Indian defence shipbuilding: Management referred to more than 200 ships by 2032 and approximately 230–250 ships by 2035.
▪️ Financial approvals of around ₹2.75 lakh crore were highlighted. Management estimates its addressable HVAC/R opportunity at approximately 1%, translating to around ₹2,750 crore over the next two years.
▪️ Non-defence shipbuilding: Team referred to approximately 475 ships under construction/planned and estimates its potential contribution at around 0.5%, or approximately ₹2,500 crore.
▪️ Management's broader estimate for the combined shipbuilding opportunity is approximately ₹4,000–5,000 crore.
MANUFACTURING CAPACITY & CAPEX
▪️ New Unit 2 has been commissioned, taking the total manufacturing area to approximately 70,000 sq. ft., comprising the existing 20,000 sq. ft. facility and the new 50,000 sq. ft. facility.
▪️ An additional 50,000 sq. ft. of land is available for expansion. The land has already been levelled, and management indicated that further capacity can be added by constructing a shed.
▪️ Unit 1 is being developed into a testing-focused facility.
▪️ The new manufacturing setup includes laser cutting, bending, robotic welding, painting facilities and other integrated manufacturing capabilities.
▪️ Testing infrastructure includes a controlled ambient test room and tilt-testing facilities to simulate ship movement.
▪️ They confirmed that current capacity is sufficient for its existing guidance. No specific amount for a fresh expansion CapEx was quantified during the call.
COMPETITIVE ADVANTAGE & TECHNOLOGY
▪️ Management described the company as a leading manufacturer with the highest market share in its niche of naval HVAC systems, AC plants and refrigeration plants.
▪️ A key differentiator is its ability to manufacture electrical control panels in-house, allowing greater control over the product value chain.
▪️ Indian Navy has standardised six AC plant capacities, of which five are already type-tested by the company.
▪️ Around 75% of HVAC components are already type-tested. This qualification advantage can reduce the time and cost required to execute new orders.
▪️ The company's business extends beyond equipment supply to retrofits, spares, installation, commissioning and lifecycle servicing.
▪️ It has service teams positioned across major Indian Navy ports, supporting installation and after-sales requirements.
DATA CENTRE COOLING
▪️ The company currently has no confirmed data-centre orders and management acknowledged that it has missed a few opportunities.
▪️ The strategy is to initially source products from an Australian partner and consider manufacturing in India once volumes become meaningful.
▪️ The company is focusing on oil-free and magnetic-bearing Turbocor chiller technology.
▪️ Management believes its existing naval service network can support installation, commissioning and lifecycle servicing for data-centre customers.
▪️ Adoption remains relatively slow because of the higher initial CapEx associated with this technology and customer focus on upfront cost.
▪️ Management expects traction in approximately 6–8 months, potentially around a year.
▪️ Importantly, data-centre revenue is not included in FY27 or FY28 guidance. Any contribution during this period would be incremental.
AQUILON – NEW BUSINESS VERTICAL
▪️ The company has incorporated a wholly owned subsidiary, Aquilon, to enter the industrial sub-zero chiller segment.
▪️ Target industries include chemicals, food processing and pharmaceuticals.
▪️ Commercial operations and initial billing are expected in FY28.
▪️ Management sees a market opportunity of several thousand crores and aims to establish a strong position in this segment.
▪️ Initial CapEx requirement is expected to be relatively small.
DANFOSS TURBOCOR PARTNERSHIP
▪️ Shree Refrigerations has become an authorised TASP (Turbocor Authorised Service Partner) for compressor servicing and repairs.
▪️ Earlier, certain compressor repairs had to be sent to the US. These can now be undertaken in India.
▪️ Management indicated that only 2–3 such authorised partners exist globally and expects to service the Indian market, with potential coverage of nearby countries.
▪️ The Indian Navy already has an installed base of more than 100 chillers and 200 compressors using this technology.
▪️ Management team positioned this primarily as a strategic capability-building opportunity rather than a major near-term revenue contributor.
WORKING CAPITAL & RECEIVABLES
▪️ Inventory increased from ₹54 crore to ₹80 crore, primarily due to strategic procurement of metals and copper to protect margins against commodity inflation and support H2 deliveries.
▪️ Trade receivables increased from ₹105 crore to ₹128 crore. Trailing receivable days stood at approximately 252 days.
▪️ Working-capital days had reduced from over 500 days post-IPO to around 370 days, but have moved back to approximately 400 days due to strategic inventory stocking.
▪️ Management expects working-capital days to move towards 350 days or below as the inventory gets utilised for Q3 and Q4 deliveries.
▪️ The company is also working towards reducing receivable days to approximately 200 days over time.
▪️ Higher short-term borrowings and cash-credit utilisation were attributed to the increase in operating requirements.
CASH FLOW
▪️ Operating cash flow was negative by approximately ₹42 crore in H1 FY27, mainly due to higher inventory and receivables.
▪️ Management expects operating cash flow to turn positive by the end of FY27 as working-capital requirements improve.
OTHER IMPORTANT DEVELOPMENTS
▪️ SIDM Champion Award 2026: The company received recognition in the SME import-substitution category for indigenising the submarine air-conditioning system. The award was presented by Defence Minister Rajnath Singh. L&T won the corresponding category in the large-enterprise segment.
▪️ Promoter holding: Management stated that promoters continue to hold the same number of shares as before the IPO, with no promoter selling.
▪️ Depreciation policy: The company shifted to the straight-line method, stating that it better reflects the usage of its assets. Management also noted that the change comes in a year of significant CapEx.
📌 KEY THINGS TO TRACK
▪️ Execution of the existing order book and conversion of the eight identified pipeline opportunities.
▪️ H2 delivery performance and progress towards the 22% annual EBITDA margin guidance.
▪️ Order inflows from NGC and progress on P75I.
▪️ Working-capital reduction, inventory utilisation and improvement in operating cash flow.
▪️ Commercial launch of Aquilon and progress in data-centre cooling.
Disclaimer:
For educational purposes only. Not a buy/sell recommendation. Please do your own research before making any investment decisions. DYDD.

🪔 65 Diwali Stock Picks for Samvat 2083 from leading brokerages 📈
As we welcome Samvat 2083, here are the top fundamental and technical stock recommendations curated from leading brokerages (SBI Securities, Mirae Asset Sharekhan, PL Capital, Nirmal Bang, Arihant Capital, and Motilal Oswal) 👇🏻
🔲 Motilal Oswal
▪️ Kotak Mahindra Bank
▪️ Adani Ports and Logistics
▪️ Titan Company Ltd
▪️ Eternal Ltd
▪️ BSE Ltd
▪️ SPR Auto Technologies Ltd
▪️ Shaily Engineering
▪️ Arvind Ltd
▪️ Unimech Aerospace
▪️ Symbiotec Pharmalab
🔲 Mirae Asset Sharekhan
▪️ Bharti Airtel Ltd
▪️ ICICI Bank Ltd
▪️ Larsen & Toubro Ltd
▪️ Titan Company Ltd
▪️ UltraTech Cement Ltd
▪️ Indian Hotels Company Ltd (IHCL)
▪️ Navin Fluorine International Ltd
▪️ Welspun Corp Ltd
▪️ Tata Consumer Products Ltd
▪️ Radico Khaitan Ltd
▪️ Dee Development Engineers Ltd
▪️ Karnataka Bank Ltd
▪️ Lumax Auto Technologies Ltd
▪️ Sagility Ltd
▪️ VA Tech Wabag Ltd
🔲 SBI Securities (SBICAP Securities)
▪️ Tata Steel Ltd
▪️ Indian Hotels Company Ltd
▪️ Multi Commodity Exchange of India Ltd
▪️ Jyoti CNC Automation Ltd
▪️ Sky Gold & Diamonds Ltd
▪️ Genus Power Infrastructures Ltd
▪️ Power Mech Projects Ltd
▪️ Centum Electronics Ltd
▪️ Stylam Industries Ltd
▪️ Sambhv Steel Tubes Ltd
▪️ Lumax Industries Ltd
🔲 PL Capital (Prabhudas Lilladher)
▪️ Apollo Hospitals
▪️ DLF Ltd
▪️ GE Vernova T&D India
▪️ HBL Engineering Ltd
▪️ Jindal Steel Ltd
▪️ Marine Electricals Ltd
▪️ Shilpa Medicare Ltd
▪️ Syrma SGS Technology Ltd
▪️ Transformers and Rectifiers (India) Ltd (TARIL)
▪️ TD Power Systems Ltd
🔲 Nirmal Bang
▪️ Axis Bank Ltd
▪️ Eternal Ltd (Zomato/Blinkit)
▪️ One 97 Communications Ltd (Paytm)
▪️ Prince Pipes Ltd
▪️ Rentomojo Ltd
▪️ SG Finserve Ltd
▪️ Tata Consumer Products Ltd
▪️ Ultratech Cement Ltd
🔲 Arihant Capital
▪️ Sammaan Capital Ltd
▪️ HFCL Ltd
▪️ Sheela Foam Ltd
▪️ Raymond Realty Ltd
▪️ GMM Pfaudler Ltd
▪️ Inox Wind Ltd
▪️ C.E. Info Systems Ltd (MapmyIndia)
▪️ KPIT Technologies Ltd
▪️ Raymond Lifestyle Ltd
▪️ Texmaco Rail & Engineering Ltd
▪️ Nuvoco Vistas Corporation Ltd
▪️ Sudarshan Chemical Industries Ltd
▪️ HEG Advanced Materials Ltd
▪️ Vindhya Telelinks Ltd
▪️ Exide Industries Ltd
▪️ Kirloskar Pneumatic Company Ltd
⚠️ Educational purposes only. No Buy/Sell Recommendation. DYODD.
Wishing you a prosperous Samvat 2083! 🎆
📊 NIFTY 50 STOCKS: YTD PERFORMANCE IN 2026
🚀 Best Performer: BSE (+32.6%)
📉 Worst Performer: TCS (-33.9%)
🟩 Above +10% (Top Gainers)
▪️ BSE
▪️ Apollo Hospitals
▪️ Titan
▪️ Adani Ports & SEZ
▪️ Bajaj Auto
▪️ Adani Enterprises
▪️ Eternal
▪️ JSW Steel
▪️ Tech Mahindra
▪️ Trent
▪️ Grasim
🟦 0% to +10% (Moderate Gainers)
▪️ Power Grid
▪️ Hindalco
▪️ State Bank of India (SBI)
▪️ Coal India
▪️ Dr. Reddy's
▪️ Kotak Mahindra Bank
▪️ ICICI Bank
▪️ Sun Pharma
▪️ Cipla
▪️ UltraTech Cement
▪️ 0% to -10% (Mild Correctors)
▪️ ONGC
▪️ Bajaj Finance
▪️ Nestlé India
▪️ NTPC
▪️ Bharti Airtel
▪️ Larsen & Toubro (L&T)
▪️ Bharat Electronics (BEL)
▪️ InterGlobe Aviation (IndiGo)
▪️ Axis Bank
▪️ Tata Steel
▪️ Eicher Motors
🟧 -10% to -20% (Moderate Decliners)
▪️ Asian Paints
▪️ Reliance Industries
▪️ Bajaj Finserv
▪️ Shriram Finance
▪️ Hindustan Unilever (HUL)
▪️ SBI Life
▪️ Max Healthcare
▪️ HCLTech
▪️ Tata Consumer Products
▪️ Below -20% (Significant Laggards)
▪️ Jio Financial Services
▪️ Infosys
▪️ Tata Consultancy Services (TCS)
▪️ HDFC Life
▪️ Mahindra & Mahindra (M&M)
▪️ Tata Motors
▪️ HDFC Bank
▪️ Maruti Suzuki
(As of 2 November 2026 close. Price returns since 31 Dec 2025; Source: NSE, NSE Indices)
Educational purposes only. Not investment advice.

The Indian Investor retweeted
KRN HEAT EXCHANGER – Q2 & H1 FY27 INVESTOR HIGHLIGHTS ❄️🧊
About the company
▪️ KRN caters to multiple industries, including HVAC, refrigeration, data centres, automotive, railways, industrial cooling, process applications, power and marine.
▪️ The company focuses on customised product development, precision engineering, integrated manufacturing, testing and quality control.
Data centre cooling – an important growth opportunity
▪️ Management highlighted data centre cooling as an important emerging growth engine for KRN.
▪️ New customers in the data centre segment have started working with the company.
▪️ Customers are planning their requirements and placing orders well in advance, providing better visibility for future business.
▪️ KRN's existing Fin & Tube product portfolio includes solutions for data centres, server rooms, precision air conditioning and CRAC units.
▪️ The company is also developing products for liquid cooling as data centre cooling technology evolves towards this solution.
▪️ Increasing demand for data centres and associated thermal-management infrastructure could create opportunities across the company's cooling product portfolio.
Bus AC business – new growth segment
▪️ During 2025–26, KRN established its wholly owned subsidiary, KRN HVAC Products Private Limited, and acquired the Bus AC division of Sphere Refrigeration Systems.
▪️ The acquisition expands the company's presence into bus air-conditioning solutions.
▪️ Management confirmed that supplies to an OEM have commenced.
▪️ The company is gradually adding more customers in this segment.
▪️ Its product portfolio includes electric bus AC and conventional bus AC systems, catering to city, school, staff and electric buses.
Exports and international presence
▪️ KRN has an established export presence across North America, Europe, the UAE and other international markets.
Export contribution to total revenue:
▪️ FY24 – 14.68%
▪️ FY25 – 15.69%
▪️ FY26 – 16.57%
▪️ H1 FY27 – 22.01%
▪️ Domestic sales contributed 77.99% of H1 FY27 revenue, while exports contributed 22.01%.
▪️ H1 FY27 country-wise export revenue distribution:
▪️ USA – 43.75%
▪️ Canada – 12.82%
▪️ France – 12.67%
▪️ UK – 7.93%
▪️ Italy – 7.65%
▪️ Others – 15.19%
▪️ Management stated that exports have grown several times over the first half of FY27, with increased business from customers in North America and Europe.
Certifications and competitive positioning
▪️ The company holds multiple quality and compliance certifications supporting its domestic and international operations.
▪️ Key certifications include CE, IMS, ZED Silver, EN ISO 15609-1:2019, ISO 9606-1:2017, BS EN ISO 13134, BS EN ISO 13535, AHRI, UL 207 and IS 11329:2018.
▪️ KRN has received recognition from global industry participants, including Carrier, Daikin, Honeywell and Schneider Electric.
Management outlook and growth strategy
▪️ Management described H1 FY27 as a strong period, with growth across customers, products and geographies.
▪️ Expanded manufacturing capabilities at Neemrana are expected to support larger customer programmes.
▪️ The company is continuing to qualify more customers and widen its product portfolio.
▪️ Management sees opportunities across data centres, infrastructure, mobility and industrial cooling.
▪️ Data centre cooling is becoming an important growth engine, with customers planning and placing orders well in advance.
▪️ Liquid cooling product development is another area the company is working on.
▪️ In the Bus AC segment, supplies have commenced to an OEM, and the company is working on adding more customers.
▪️ Management remains optimistic about the opportunities ahead and is strengthening its teams and systems to support expansion.
KRN is expanding beyond its traditional heat exchanger business into a broader HVAC&R solutions platform.
Data centre cooling, liquid cooling development, exports and the newly added Bus AC business provide multiple potential growth avenues. Its wider product portfolio, manufacturing infrastructure and international customer relationships are important strengths to track.
For educational purposes only. Not a buy/sell recommendation. Please do your own research before making any investment decisions. DYDD.
The Indian Investor retweeted
LIST OF SME COMPANIES THAT HAVE POSTED Q2 FY27 RESULTS IN THE LAST 3-4 DAYS 🧵
▪ Madhusudan Masala – ↑118%
▪ Chemkart India – ↑99%
▪ Kody Technolab – ↑97%
▪ Technocrats Plasma – ↑97%
▪ OBSC Perfection – ↑97%
▪ Concord Control – ↑95%
▪ GP Eco Solutions – ↑93%
▪ HOAC Foods – ↑91%
▪ Shree Refrigerations – ↑85%
▪ Sunlite Recycling – ↑75%
▪ Fabtech Technologies Cleanrooms – ↑75%
▪ Taurian MPS – ↑73%
▪ Jay Jalaram Tech – ↑69%
▪ Baheti Recycling – ↑68%
▪ Gayatri Rubbers – ↑59%
▪ Credent Connect N Care – ↑53%
▪ Spunweb Nonwoven – ↑48%
▪ Rajesh Power – ↑46%
▪ Effwa Infra – ↑45%
▪ Cryogenic OGS – ↑44%
▪ Monarch Surveyors – ↑36%
▪ Shera Energy – ↑34%
All results are given below for reference 👇
PART - 01 👇
Disclaimer:
For educational purposes only. Not a buy/sell recommendation. Please do your own research before making any investment decisions. DYDD.


🎇 Happy Muhurat Trading 2026 !!
Welcome Samvat 2083 with new opportunities to learn, grow, and prosper.
#Samvat #Samvat2083 #Investing

The Indian Investor retweeted
Kanohar Electricals - Q1 FY27 Concall 2-3 Minutes Read 🔥🔥🔥
Management guidance and order visibility
🔹 FY27 revenue target: Approximately ₹950 crore, with an EBITDA margin profile broadly similar to FY26.
🔹 FY28 outlook: Management indicated that a broadly similar year-on-year growth trend to FY27 could continue in FY28, although no specific revenue guidance was provided.
🔹 Order inflows: ₹332.2 crore in Q1 and ₹867.3 crore in Q2 (July–September), including a large PSU order of ₹250 crore and above.
🔹 Order book: ₹2,026 crore as of June 30, 2026, up 11% from ₹1,818.3 crore as of March 31, 2026.
🔹 Execution: H2 is expected to remain the key execution period. Industry lead times are currently around 18–24 months.
Business overview
Kanohar Electricals is an engineering company with over 40 years of experience, specialising in high-value power transformers and electrical infrastructure.
Its business is primarily divided into:
🔹 Transformers: Approximately 85% of FY26 revenue.
🔹 EPC: Approximately 15% of FY26 revenue.
The EPC business is strategically important because utilities often bundle transformers into larger substation packages. EPC capabilities allow the company to bid for these packages directly, widening its addressable market and improving its chances of winning orders.
Key product capabilities:
Power transformers up to 500 MVA, 400 kV.
Scott-connected traction transformers up to 100 MVA at 220 kV and 132 kV.
Shunt reactors up to 125 MVAr, 400 kV.
Manufacturing capacity and expansion
The company operates two manufacturing facilities in Meerut:
🔹 Combined installed capacity: Approximately 19,200 MVA.
🔹 Gangol facility: Approximately 18,000 MVA, primarily focused on large power transformers and shunt reactors.
Expansion plans:
Brownfield expansion of approximately 18,000 MVA at Gangol.
Part of the IPO proceeds will be utilised for this expansion.
Existing capacity is expected to be sufficient through FY28.
New capacity is targeted to be in place for FY29.
📌 The expansion is also being designed to accommodate 765 kV transformers.
Competitive advantage and certifications
One of the important points highlighted by management is that manufacturing capacity alone does not qualify a company to participate in large utility and railway tenders.
Two major requirements are:
Past performance – transformers must demonstrate satisfactory operation in the field for a defined period.
Short-circuit certification – certification is required for the specific transformer rating.
For a 500 MVA transformer, the certification process can take approximately 18–24 months from concept to certification.
Kanohar's qualifications:
Completed more than 200 successful short-circuit tests at government laboratories.
Among the few Indian manufacturers certified for 500 MVA, 400 kV transformers.
First Indian company to receive RDSO approval for a 100 MVA, 220 kV Scott-connected transformer.
One of only two companies certified at this rating.
For 100 MVA, 132 kV Scott-connected transformers, the company is among four certified players.
These certifications and execution history help the company qualify for technically demanding tenders.
Product mix and premiumisation
The company has witnessed a significant shift towards high-voltage transformers.
Contribution from 400 kV transformers:
FY24: 10.3%
FY26: 52%
Q1 FY27: Approximately 70%
Management highlighted that higher manufacturing contribution compared with EPC has helped improve the blended gross margin profile.
Within its focused manufacturing portfolio, 400 kV power transformers, Scott-connected transformers and shunt reactors have broadly similar margin profiles.
Distribution transformers have a lower margin profile and remain a negligible part of the company's revenue and order book.
Industry opportunity
Management believes India is entering a structural investment cycle in power transmission and railway infrastructure.
Key demand drivers include:
Industrialisation and urbanisation.
Rising electricity consumption.
Data centres and electric mobility.
Renewable energy evacuation.
Expansion of intra-state transmission infrastructure.
Railway modernisation and dedicated freight corridors.
Green Energy Corridor III
Government outlay of approximately ₹1.85 lakh crore.
Focused on intra-state transmission.
Management highlighted that 400 kV is typically the highest voltage used at the state transmission level, which aligns with the company's capabilities.
400 kV transformer opportunity
Estimated annual Indian market size: ₹4,000–₹6,000 crore.
Demand during the previous year: Approximately 60,000–70,000 MVA.
Management expects industry demand to grow by at least 10–15%.
Railway opportunity
India has already completed approximately 99.6% broad-gauge railway electrification.
The next phase involves the 2x25 kV AC system for high-speed rail and heavy-haul projects, including Vande Bharat and dedicated freight corridors.
This creates demand for specialised Scott-connected transformers.
Management shared the following opportunity:
Approximately 1,000 traction substations are envisaged over the next 5–10 years.
Each substation requires two transformers.
This translates into approximately 2,000 transformers.
Estimated market opportunity: Around ₹20,000 crore over the next 5–10 years.
Management also confirmed that Scott-connected transformers have broadly similar margins to its focused power transformer products.
Shunt reactors
Shunt reactors are important for maintaining grid voltage stability as more renewable energy capacity gets connected to the transmission network.
Management expects shunt reactors to contribute approximately 10–15% of revenue on an average basis.
As of June 30, 2026, they accounted for approximately 13.1% of the order book.
765 kV transformer opportunity
765 kV is the company's next major technological step.
Important management comments:
Technology has already been developed in-house.
No Indian player had completed a 765 kV short-circuit test at the time of the call.
The company is ready to manufacture a prototype.
No technology tie-up is required.
The key requirement is to secure initial orders and establish satisfactory field performance.
Management expects a 3–4-year journey before becoming eligible for regular 765 kV tenders.
The upcoming 18,000 MVA capacity expansion will also be suitable for manufacturing 765 kV transformers.
Backward integration
The company has invested in manufacturing several critical components in-house, including:
Transformer tanks.
Control panels.
Radiators.
Insulation components.
These components are primarily meant for captive consumption.
Management highlighted that in-house manufacturing improves control over product quality, reliability and delivery timelines.
There are currently no major plans to expand backward integration into additional components beyond these areas.
Working capital and execution
Management shared the following working capital details:
Receivables: Approximately 120 days.
Inventory: Approximately 80 days.
Payables: Approximately 70–80 days.
Net working capital cycle: Approximately 120 days.
The company expects net working capital to remain broadly in the 110–120-day range.
Management clarified that this is primarily due to the long manufacturing and execution cycle of large transformers. Its customers are central and state utilities, and management stated that the company has not faced any payment delinquencies.
Raw material price protection
On concerns around transformer oil, copper and other raw material inflation, management explained that most contracts contain the industry-standard IEEMA Price Variation Clause.
This mechanism adjusts contract prices for raw material price movements, helping protect the company against input-cost volatility.
Management also indicated that the current order book and ongoing tender pipeline have a broadly similar margin profile to FY26, with a stable margin outlook over the next 3–4 years.
However, management acknowledged that supply-demand mismatches could create some short-term margin pressure beyond this period.
Exports and other updates
🔹 Exports: The company has previously exported to markets including the US, West Africa and Southeast Asia. However, management is currently prioritising the domestic market and may revisit exports in 3–4 years.
🔹 Solar power plant: Approximately 2,500 kW capacity is planned using part of the IPO proceeds. Management expects electricity cost savings but did not quantify the expected savings during the call.
🔹 Revenue per MVA: The company generated approximately ₹6.1 lakh per MVA in the previous year. Management clarified that this figure varies depending on the product and rating mix.
🔹 Inverter duty transformers: Not a focus area for the company.
Key points to track
Execution of the ₹950 crore FY27 revenue target.
Order inflows and order book conversion.
Sustaining the FY26 EBITDA margin profile.
Further improvement in the 400 kV product mix.
Progress on the additional 18,000 MVA capacity expansion.
Growth in Scott-connected transformers and shunt reactors.
Development and qualification of 765 kV transformers.
Working capital remaining within the guided range of 110–120 days.
Overall takeaway: Kanohar is positioning itself in the premium end of the transformer market, supported by specialised certifications, a growing order book and structural opportunities in power transmission and railways. The key factors to monitor are execution, product mix, margin sustainability and timely capacity expansion.


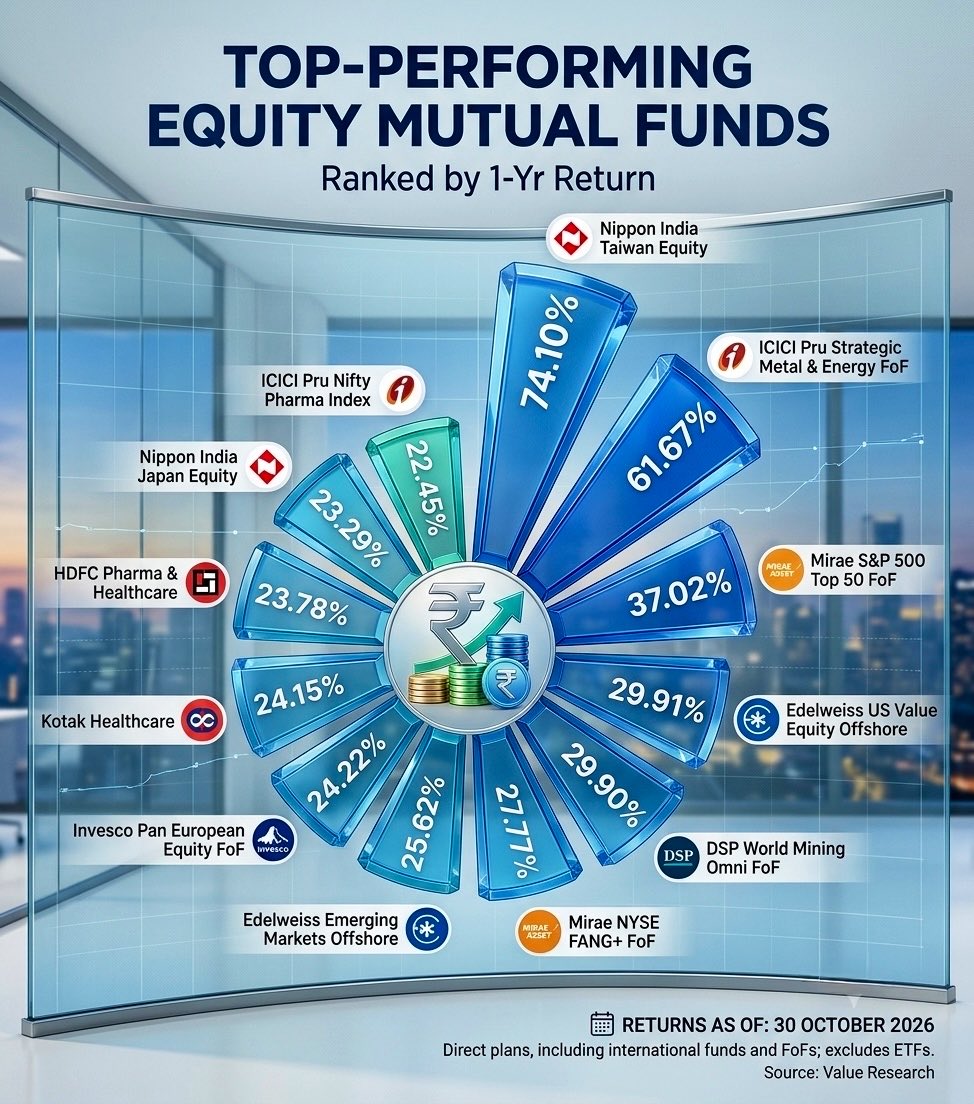
🏆 Top-Performing Equity Mutual Funds by 1-Yr Return (as of 30 October 2026)
▪️ Nippon India Taiwan Equity: 74.10%
▪️ ICICI Pru Strategic Metal & Energy FoF: 61.67%
▪️ Mirae S&P 500 Top 50 FoF: 37.02%
▪️ Edelweiss US Value Equity Offshore: 29.91%
▪️ DSP World Mining Omni FoF: 29.90%
▪️ Mirae NYSE FANG+ FoF: 27.77%
▪️ Edelweiss Emerging Markets Offshore: 25.62%
▪️ Invesco Pan European Equity FoF: 24.22%
▪️ Kotak Healthcare: 24.15%
▪️ HDFC Pharma & Healthcare: 23.78%
▪️ Nippon India Japan Equity: 23.29%
▪️ ICICI Pru Nifty Pharma Index: 22.45%
Data source: Value Research (Direct plans, including international funds & FoFs; excludes ETFs).
Disclaimer: Mutual fund investments are subject to market risks. Read all scheme-related documents carefully before investing.
🐴 Real horsepower 🔥
Cars became a necessity, so the rich went back to actual horses to keep flexing 😅

The Indian Investor retweeted

Kanohar sold 𝗮𝗹𝗺𝗼𝘀𝘁 𝗻𝗼 𝘀𝗵𝘂𝗻𝘁 𝗿𝗲𝗮𝗰𝘁𝗼𝗿𝘀 last year. In H1 FY27, they were 𝟮𝟮% 𝗼𝗳 𝗿𝗲𝘃𝗲𝗻𝘂𝗲.
Q2 revenue was ₹𝟮𝟬𝟵 Cr vs ₹𝟵𝟴 Cr. EBITDA was ₹𝟳𝟯 Cr vs ₹𝟮𝟳 Cr, and the margin went from 𝟮𝟴% 𝘁𝗼 𝟯𝟱%. Other income was just ₹2.6 Cr, so this is operating profit.
Shunt reactors go into 𝗿𝗲𝗻𝗲𝘄𝗮𝗯𝗹𝗲 𝗴𝗿𝗶𝗱 𝗶𝗻𝘁𝗲𝗴𝗿𝗮𝘁𝗶𝗼𝗻. Kanohar is also 𝗼𝗻𝗲 𝗼𝗳 𝗳𝗶𝘃𝗲 𝗰𝗼𝗺𝗽𝗮𝗻𝗶𝗲𝘀 𝗶𝗻 𝗜𝗻𝗱𝗶𝗮 certified for 500 MVA 400 kV transformers.
Put those together and products of 𝟮𝟮𝟬 𝗸𝗩 𝗮𝗻𝗱 𝗮𝗯𝗼𝘃𝗲 𝗮𝗿𝗲 𝗻𝗼𝘄 𝟳𝟴% 𝗼𝗳 𝗿𝗲𝘃𝗲𝗻𝘂𝗲, up from 53% a year ago. That’s where the jump in 𝗴𝗿𝗼𝘀𝘀 𝗺𝗮𝗿𝗴𝗶𝗻 𝘁𝗼 𝟰𝟲% came from.
The orders followed. They won ₹𝟴𝟲𝟳 Cr 𝗶𝗻 𝗤𝟮, taking the 𝗼𝗿𝗱𝗲𝗿 𝗯𝗼𝗼𝗸 𝘁𝗼 ₹𝟮,𝟳𝟭𝟭 Cr, about 𝟰𝘅 𝗙𝗬𝟮𝟲 𝗿𝗲𝘃𝗲𝗻𝘂𝗲.
𝗧𝘄𝗼 𝘁𝗵𝗶𝗻𝗴𝘀 𝗸𝗲𝗲𝗽 𝗺𝗲 𝗰𝗮𝗿𝗲𝗳𝘂𝗹.
𝟭. 𝗖𝗮𝘀𝗵 𝗰𝗼𝗻𝘃𝗲𝗿𝘀𝗶𝗼𝗻
- H1 operating cash flow was ₹𝟮𝟯 Cr against ₹𝟭𝟭𝟮 Cr EBITDA. FY26 looked the same: ₹𝟮𝟲 Cr OCF on ₹𝟭𝟴𝟬 Cr EBITDA.
- So this isn’t just stocking up for H2. It’s how the business runs when 𝟵𝟴.𝟳% 𝗼𝗳 𝗿𝗲𝘃𝗲𝗻𝘂𝗲 𝗰𝗼𝗺𝗲𝘀 𝗳𝗿𝗼𝗺 𝗴𝗼𝘃𝗲𝗿𝗻𝗺𝗲𝗻𝘁.
𝟮. 𝗠𝗮𝗻𝗮𝗴𝗲𝗺𝗲𝗻𝘁 𝗴𝘂𝗶𝗱𝗮𝗻𝗰𝗲
- Management kept 𝗙𝗬𝟮𝟳 𝗿𝗲𝘃𝗲𝗻𝘂𝗲 𝗴𝘂𝗶𝗱𝗮𝗻𝗰𝗲 𝗮𝘁 ₹𝟵𝟱𝟬 Cr, with a margin similar to FY26’s 𝟮𝟳.𝟲%.
- After a 𝟯𝟮% 𝗛𝟭 𝗺𝗮𝗿𝗴𝗶𝗻, that implies 𝗛𝟮 𝗺𝗮𝗿𝗴𝗶𝗻𝘀 𝗻𝗲𝗮𝗿 𝟮𝟱%.
- Either they’re being conservative, or 𝘁𝗵𝗲 𝗽𝗿𝗼𝗱𝘂𝗰𝘁 𝗺𝗶𝘅 𝗻𝗼𝗿𝗺𝗮𝗹𝗶𝘀𝗲𝘀.
- 𝗜’𝗺 𝘄𝗮𝘁𝗰𝗵𝗶𝗻𝗴 𝗛𝟮 𝗺𝗮𝗿𝗴𝗶𝗻 𝗺𝗼𝗿𝗲 𝘁𝗵𝗮𝗻 𝗛𝟮 𝗿𝗲𝘃𝗲𝗻𝘂𝗲.
No Buy/Sell Recommendations
