

Bloomberg terminal? Brother, I got a cracked iPhone, a nicotine addiction, and the gift of prophecy.
Behind The Counter
Joined October 2026
- Tweets76
- Following31
- Followers42
- Likes134
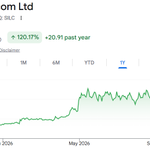


$SILC, An Overlooked AI Infrastructure Earnings Inflection?
We've been examining Silicom ($SILC), a ~$220M microcap providing specialized networking hardware, SmartNICs, FPGA adapters, cybersecurity infrastructure, and emerging AI inference solutions.
What initially caught our attention wasn't the business. It was the extremely unusual relative price performance.
Since May 20:
$SILC: −7.9%
$CRDO: −19.5%
$AEHR: −32.8%
$IREN: −52.7%
$AAOI: −59.2%
$POET: −63.1%
$NVTS: −63.5%
Despite October's substantial AI infrastructure correction, SILC has retained considerably more of its value than many peers. This is especially interesting given its extremely small market capitalization and limited liquidity.
The fundamentals may explain part of this divergence.
Quarterly revenue has progressed from $15.6M to $16.9M, $19.1M and $23.8M. Q2 revenue increased 59% YoY, while GAAP net losses narrowed to $2.1M.
Management now projects $93–95M in FY2026 revenue, has secured multiple material design wins, and expects to return to quarterly non-GAAP profitability during the second half.
The valuation is also unusual: approximately 1.8x forward EV/revenue, with roughly $55M in cash and marketable securities and no conventional financial debt.
The ownership structure is arguably just as interesting.
Portolan Capital disclosed a 5.06% ownership position in September. Meanwhile, reported short interest stood at approximately 3% of float, puny for a speculative microcap.
The next catalyst is October 29 earnings.
We're watching revenue acceleration, GAAP operating leverage, inventory conversion, cash flow, and whether emerging AI inference design wins translate into meaningful 2027 production revenue.
Risks remain substantial. SILC is small, highly speculative, illiquid, currently GAAP loss making, and carrying unusually elevated inventory. Its AI opportunity is still early stage.
Nevertheless, the combination of relative price resilience, institutional interest, modest valuation, and accelerating fundamentals is difficult to ignore.
We believe $SILC warrants serious consideration as a speculative earnings recovery opportunity, not simply another AI infrastructure momentum trade.
TLDR This is risky, but the price action is so incredibly weird, a company this small in ai infra should be beaten into the floor, but instead its been virtually flat since may.
Disclosure: I have held a position in $SILC since before the launch of Smoke Shop Finance. This is an existing investment, not a newly initiated position.

SMOKE SHOP FINANCE
$MO Altria Group | LONG TERM BUY, likely set to outperform into 2027
With increasing uncertainty surrounding technology valuations, persistent inflationary pressures, and elevated Treasury yields, I believe Altria Group offers an attractive opportunity for investors seeking defensive exposure, consistent income, and moderate earnings growth.
Dividend Yield & Shareholder Returns
At $74.09 per share, Altria offers an annualized dividend yield of approximately 6.0%, supported by a quarterly distribution of $1.11 per share.
The company has increased its dividend 61 times over the past 57 years, demonstrating a longstanding commitment to shareholder returns.
Unlike many high growth equities that are currently popular on X, a substantial portion of Altria's investment proposition comes from recurring cash distributions rather than expectations of future multiple expansion.
Earnings Growth & Valuation
Despite declining cigarette consumption, Altria continues to generate earnings growth through pricing power, operational efficiency, and share repurchases.
Adjusted EPS increased 4.4% in 2025. Management currently projects 2026 adjusted EPS of 5.61–5.72, representing growth of 3.5%–5.5%.
At approximately 13.1x forward adjusted earnings, the valuation remains attractive for a mature business generating substantial cash flow and returning capital consistently.
Defensive Characteristics
Tobacco consumption has historically demonstrated relatively low sensitivity to economic cycles, with established consumer habits supporting recurring demand.
During the inflationary bear market of 2022, Altria generated approximately 4.4% in total shareholder returns, including reinvested dividends, compared with an 18.1% decline in the S&P 500.
This illustrates the defensive characteristics of its business model during periods of market stress.
Investment Outlook
Regulatory exposure, declining cigarette volumes, and competition from alternative nicotine products remain material risks.
Nevertheless, Altria's pricing power, recurring cash generation, and substantial dividend provide a compelling foundation for long term total returns.
I view $MO as an attractive defensive holding, particularly for investors seeking portfolio income and reduced dependence on technology sector valuations.
Rating: LONG TERM BUY
— Smoke Shop Finance 🚬
Wall Street has officially run out of people I respect.
I will now be conducting equity research from a smoke shop in Los Angeles.
Our Bloomberg terminal is a stolen calculator.
Our investment committee is me.
Our compliance department is currently serving 6 to 8 years.
$MO dividends got me feelin' bullish.
Welcome to Smoke Shop Finance. 🚬