Love him or hate him, this is why he wins.
Just did a round table review with the Grok @Bot engineering team.
Fixes are being implemented overnight and you should notice a dramatic improvement by tomorrow. If not, reply to this post and we will address any remaining issues right away.
Owners usually look at financing their receivables when cash is tight. The question to ask first is why it's tight.
If good customers are simply paying slowly, that's a timing problem. Getting that cash sooner for a fee can be a reasonable trade.
If the jobs behind those invoices lose money, that's a margin problem. Financing doesn't fix it. It just gets the loss to you faster, with a fee on top.
Say you invoice $10,000 for a job that cost $10,800. A lender advances $8,500 now and charges 3% of the invoice, which is $300. The cash shows up sooner, but the job still lost $800, and with the fee it's $1,100.
So before signing a receivables facility, run job margin on the invoices you'd be financing. That tells you whether you have a timing problem or a margin problem.
AI can make a messy financial process look impressively efficient.
That’s part of what makes it dangerous.
If your chart of accounts is inconsistent, your reporting cadence is unreliable, and nobody agrees on which numbers matter, automation just gets you to a confusing answer faster.
I see this when owners want to jump straight to dashboards, integrations, and AI-generated reports.
Those tools can be useful.
But first, someone needs to decide what the business is trying to understand.
Are margins healthy by service line?
Is cash getting collected quickly enough to cover upcoming obligations?
Which operating number is actually limiting growth?
Once the questions are clear, technology can do a lot of the heavy lifting.
We use automation to pull information together and speed up the reporting process.
Then a human checks the work before and after the system runs.
Financial decisions have real consequences.
Which is why the goal is a reporting process that helps an owner make a better decision before a problem becomes expensive.
So start with the question.
Then build the process.
Then decide where technology earns a seat at the table.
Our clients get a full financial dashboard from us. It's one of the most useful things we build. But there's one habit I ask every owner to keep when they use it.
If you're looking at the current month, or any month the books haven't been closed for, check with your bookkeeper before you act on it.
An open month usually has transactions that haven't been coded yet. In my experience that makes revenue look lower or the P&L look messy, not better. A month that shows more revenue than you expected because of uncoded items is unusual.
Say the dashboard shows $42,000 of revenue for the month, and $8,000 of sales are still sitting uncoded. Revenue is closer to $50,000. Make a staffing or spending call off the $42,000 and you're deciding on the wrong number.
So use the dashboard every day. Just treat closed months as the ones to decide on, and ask your bookkeeper about the rest.
In a planning meeting for a service business we work with, someone suggested a small monthly add-on fee for a new client dashboard we're considering. It's a fair idea, and nothing has been decided.
What I keep thinking about is what an add-on does to how clients see the feature. A small extra fee tells them it's optional. Plenty of clients skip optional things, and the ones who skip it never see the value.
Sometimes an add-on is still the right call. Other times it's better to include the feature in the base price, let every client use it, and later raise the price because the service is better.
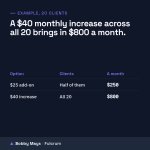
Say there are 20 clients. A $25 monthly add-on that half of them take brings in $250 a month. A $40 monthly increase across all 20 brings in $800 a month. Neither is guaranteed to land.
So when you add something clients value, think about how the pricing makes them feel about it, not just what it brings in next month.
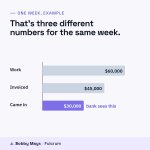
Say one week a business did $60,000 of work and invoiced $45,000, and $30,000 actually came in. That's three different numbers for the same week, and a cash forecast built from the bank alone only sees the last one.
That's why our team updates a client's weekly cash forecast from three files instead of one: the bank statement, the receivables report, and the work-completed report.
Each one answers a different question. The bank shows where cash actually moved. Receivables show what was invoiced and what has been collected against it. The work detail shows what got done, billed or not.
The differences between those three are where cash surprises come from: work that hasn't been invoiced yet, and invoices that haven't been paid. If you only watch the bank balance, you find out about both late.
Don't shrug off a 1 or 2 point margin win. Say revenue is $3M and margin improves by 2 points. That's $60,000 a year, or $5,000 a month. At scale, those points are real money.
Last week I cancelled a reporting tool in my business. The product was fine. When the vendor asked why, the honest answer was that the business had changed and we didn't need it right now.
We just weren't using it the way I assumed we would when I signed up. That's easy to miss, because the charge shows up every month whether anyone logs in or not.
The question worth asking of every recurring tool is simple: are we using this the way we assumed when we bought it? If the answer is no, a good product is still a cost you're carrying for a business you don't have anymore.
Say a tool costs $150 a month and gets opened eight times a year. That's $1,800 a year, or $225 each time someone uses it. Framed that way, cancelling a good tool gets a lot easier.
The first hire at one of my clients took 4 months to fully onboard.
The second took 2 months.
That improvement didn’t come from finding a dramatically better employee.
It came from finally paying attention to what the first hire had to figure out alone.
This client runs a podcast editing company, and when we started working together, there was no client list and no clear picture of the work moving through the business.
Every new person had to learn by asking whoever happened to have the answer.
We built an Airtable dashboard to give the team one place to see the work, the clients, and the handoffs.
Then we started documenting the process behind the work.
The goal wasn’t a perfect operating manual with every possible exception covered…
The goal was to make the next person less dependent on someone else remembering how things had always been done.
Most businesses think they have a hiring problem when they really have an onboarding problem.
A great hire still needs a clear path to become useful.
If it takes months for every new person to find their footing, the process is carrying far too much inside people’s heads.
There are about nine weeks left in 2026. That's still enough time to make year-end tax decisions on purpose. By late December, the only options left are rushed ones.
The decisions are usually the same four: equipment purchases, bonuses, owner pay and retirement contributions. Decided one at a time in December, each can look fine on its own. Decided together now, against a year-end projection, you can see what the set does to the tax bill and to cash.
After each move, check the reserve, not just the tax line. A plan that lowers the bill but leaves the reserve thin going into the new year needs another pass.
The specifics of what each move does on the return are a conversation for your CPA. The projection is what lets you have that conversation in the next two weeks instead of the last two.
It's easy to keep paying for new leads while years of past customers sit in old files with no follow-up, even when the work you did for them needs doing again.
Part of the reason is that the leads come with a bill and the old customers don't. Nobody is sending you an invoice to remind you they exist. But they already know you, and if the work repeats, some of them are due for it now.
Before buying the next batch of leads, I'd pull a list of past customers who are due for the same work again and actually work through it.
Then track it like any other channel. How many jobs did it book, what did it cost in time and money, and how does that compare with what you're paying per booked job from the leads?
I wouldn't assume it wins every time. But it deserves to be measured the same way as the channel you're paying for, instead of being skipped because it doesn't show up as a line on the bill.
Most businesses have some element of seasonality that needs to be considered.
Some are obvious, like a business that hangs Christmas lights, or one that sells fireworks. But nearly everyone has a slow season, if only because clients go on vacation.
Know yours so you can plan. Here's how ours generally shakes out:
Our new-client conversations drop by about 40% in early summer and pick up again around back-to-school. Late in the year, prospects tend to push to January once the holidays start. So, for us, the first of the year and early fall are our busiest onboarding periods, and summer and November/December are relatively slow. I push to lock starts before Thanksgiving instead of treating that slowdown like a pipeline problem.
This changes how and when we spend money, make hiring decisions, push marketing, negotiate with vendors, etc.
If you mostly understand that by feel and not backed by numbers, find someone who does, and I bet you will save a bunch of money and stress.
Where you put delivery payroll on the P&L can change the margin you use to make decisions.
Say a business has $100,000 in monthly sales and $40,000 in materials and subcontractors. With those costs alone, gross profit is $60,000, or 60%.
But suppose another $30,000 of payroll belongs to the crew delivering that work and is recorded in overhead. Including it in cost of sales leaves $30,000 of gross profit, or 30%.
Total operating profit hasn't changed. The report now shows more of the cost of delivering the work before you get to office overhead.
I'd review that classification with the bookkeeper and use it consistently. I'd also keep the distinction between fixed and variable costs when making a pricing decision. Moving payroll to a different line doesn't mean all of it disappears if you take one less job.
Why did this make me more excited than most announcements?? Very few things annoy me like password management.
Today we announce 1Password for Agents platform, building with companies @Muse, SpaceX Super Intelligence Grok @Bot, @AnthropicAI’s @Claudeai, @OpenAI, @TownAI, @Browserbase, @Browser_use, @heydana_ai, Instinct, @usekernel, @Perplexity_ai, @tryramp, @Tomo, and @wajo_ai, with more integrations on the way. 🎉
We've heard from so many of our customers who want to use these new personal AI agents to help them get more done, but want more control over what the agent can access with the same trust and ease of use they get when using 1Password directly.
1Password for Agents gives your agents access without giving up your passwords. When an agent reaches a sign-in form, it requests a credential from your vault. If you approve the request, 1Password directly auto-fills the credential in the destination site so the agent can’t see or take possession of the credentials.
The agent gets the task done, but it doesn’t get your passwords..
You stay in control. 1Password for Agents free and optional for personal and family accounts. Unless you opt-in to an agent connector, agents cannot touch your vault.
➡️Learn more: bit.ly/487da6J
A team can usually handle bad news.
What they struggle to handle is a leader who makes every piece of bad news feel dangerous.
When an owner gets stressed, it changes the energy in the room for the worst.
People start withholding details.
They wait too long to raise problems.
They bring solutions only after they’ve tried to hide the issue long enough that the options are worse.
And I understand the impulse.
As the owner, the stakes feel personal because they are personal.
You have way more stake in this.
Worst case for you is bankruptcy. For everyone else, they just need to look for another job.
And you’re the one who has to pick up the pieces if something goes sideways.
But your team still needs to believe the mountain is there, even when you’ve hit a rock on the trail.
That doesn’t mean pretending everything is fine. I’m not saying that.
It means acknowledging the problem without letting panic become the go-to response every time.
This is why the best founders I know carry a certain kind of optimism through difficult times.
That temperament is more valuable than most leadership advice gives it credit for.
A business can show a good profit while depending on the owner to do work someone else would have to be paid for.
Suppose annual operating profit is $400,000 after $80,000 of owner compensation has already been recorded as an expense. Replacing the owner's work would cost $190,000 a year, including employer costs.
Add back the $80,000 that would stop, then subtract the $190,000 replacement cost. That leaves $290,000 of operating profit, assuming everything else stays the same.
That isn't necessarily cash a buyer can take home. Taxes, debt payments and reinvestment still need their own analysis.
The useful question is what work must continue after the owner leaves and what it will actually cost to cover it. I'd want that understood before using the current profit to discuss a purchase price.
An AI review of a cash forecast our team was building flagged a starting revenue assumption above the recent average.
I asked whether that was planned growth. There was a reason for the increase: the business was heading into a busier period. Part of the amount was still a judgment call.
That's worth discussing before the owner relies on the forecast. Expected growth can be reasonable without being certain.
We agreed that the assumptions needed a clearer explanation and that we should walk through them with the owner. That conversation was still ahead of us.
I'd want to know what supports the growth, what the owner expects, and what happens to cash if sales come in lower. A comfortable forecast is more useful when you can see which assumptions are making it comfortable.
Owner pay needs a place in the cash plan before the owner takes money out.
I'd agree on the amount and timing, then check what that leaves for taxes, committed bills and a reserve. Additional withdrawals need the same check. A profitable month doesn't necessarily leave that profit available in cash.
Separately, I want to understand what the business earns after allowing for the work the owner does. If the owner is doing a full-time job without a comparable cost in the numbers, the apparent return can be misleading.
Those are related planning questions, but the accounting treatment depends on the business structure. A draw isn't automatically a payroll expense.
Work through the treatment with the accountant, then keep the cash plan clear about what the owner can expect and when.