

toronto rates + credit pm
Joined May 2020
- Tweets455
- Following2.7K
- Followers2.6K
- Likes4.8K




3 part story for curve today:
1. Started the day as bear flattener AGAIN (4-day streak): 2y +5, 10y +4, 2v10 -1 to new 1m low
2. Then Warsh flipped it to twist steepener: 2y -6 to low of day, 10y +2 to high of day, curve +9 to high of day
3. Then Vance/Iran story had brief bull flatten that faded: 2y -1, 10y -3
Full day: 2y -2, 10y +3, 2v10 +5
Have to trust the highest magnitude move which was the twist steepener in part 2. I hate twist steepener because you got 2y down but 10y up and therefore no clue on overall duration. But high magnitude steepening (+9!) off 1m lows tells me steepening is likely the next trade and you get good value here coming off 1m lows on 2v10.
Could be bull steepener (weak data, more AI slowdown, Iran deal) or bear steepener (no QRA change, gov and corp bond supply accelerates). Both are reasonable guesses. Bull flattener for the past 2 weeks probably out of steam but could keep going. Bear flattener just got murdered by Warsh.
So my odds point to steepener for curve with good size because entry levels are decent at 1m flats. But no size for overall duration (am small short 10y) until more clarity on price action, data, events.
Box trade of steeper US curve against flatter CA curve is an interesting variation too. IMO the BOC is looking committed to more hikes.


Feeling funny... how can Warsh kill forward guidance?
Let Jefferson/Waller/Williams guide the market to no hike (<10% odds), and then lmao side with the 3 hawkish dissents, flip 3 undecided voters like Cook/Barr/Powell (Powell won't dissent from Warsh), and surprise hike.
Market will stop listening to forward guidance from anyone. Also builds some credibility and distances himself from Trump before the House and Senate flip Democrat.
Regime change for duration positioning (bond bulls are truly back) or just a short squeeze panic and time to fade? I have small shorts I am considering upsizing.


"Becoming increasingly clear that we are re-pricing the left side of 2027+ growth distribution... re-think on AI trajectory... correlations reversed because prior assumption of forever capex no longer true"


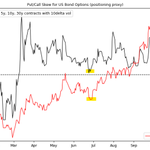
1-day delay on my futures put/call data source but I'll guess the real-time ratio is flirting with the June lows after today's rally. Think mean reversion is the play until we learn more from Fed/Midterms/QRA. 10y is a short below 5.10 and a long above 5.30.


New BIS Bulletin talks about increasingly non-linear inflation risks with Iran dragging on longer than expected and inventories rapidly depleting. BIS using "non-linear" language is a trigger for me.
bis.org/publications/bulleti…

Since the June bimonthly central bank governors meeting at the BIS, the BIS has published 3 Bulletins that read overly hawkish. These will be heavily discussed at their next meeting in September.
Bulletin 133, Aug19 on TERM PREMIUM: “term premium weakens the currency, heightens concerns that fiscal will constrain central bank independence, raises costs for credit-reliant firms, builds higher inflation into price and wage setting… term premium feeds thru to inflation expectations more rapidly when debt is elevated… adverse non-linearities raise the cost of delayed policy action… paramount for monetary policy to focus firmly on the price stability mandate”
Bulletin 131, Aug5 on ENERGY SHOCKS: "inflationary impact of energy shocks twice as large when inflation expectations are above target... tight labor markets intensify wage demands as labor seeks to reserve purchasing power... energy price surge combined with loose fiscal is followed by higher inflation... central bank wait-and-see strategy risks ripple effects such as unanchored inflation expectations and may warrant hiking more quickly"
Bulletin 130, Jul28 on AI IMPLICATIONS: "central banks too accommodative if they underestimate demand or overestimate supply improvements... demand effects already large and observable, supply effects remain uncertain on scale and timing... AI capex has not come at expense of less capex elsewhere... AI capex driving upward growth revisions... labor displacement has been limited... uncertain AI translates into higher aggregate total factor productivity... near-term inflationary effects already emerging... AI inflationary if households boost consumption in anticipation of stronger future income... AI wealth-driven consumption can boost aggregate demand and add to inflation... financial markets may lift household consumption thru wealth effects"
Notable because BIS messaging tends to lead global central bank messaging.
bis.org/bisbulletins/index.h…

The question for bonds is are we going to "v-top" on yields (like 2022, 2023, 2025) or not?
Consensus last week with us10y at 5.35 was no because a v-top doesn't kill inflation (it didn't in 2022/2023/2025). Only sustained higher for longer can kill inflation.
Then we get a bond short squeeze on AI slowdown fears and now people think THIS CYCLE WITH THESE ECO NUMBERS will v-top at 5.35 during a week that had hot cpi and hot ppi?!
I don't think yields will do a v-top, but even if they do v-top, I still don't think this week was THE v-top... hence I am looking to short duration soon.
Some bond thoughts...
1. Price action feels more short squeezy than fundamental especially with hot cpi/ppi... how many were long tech + short bonds because "only high rates can crack tech" and now forced to unwind both sides?
2. Potential Friday 12pm dealer survey surprise (cut 20y auctions?) is preventing duration sellers from stepping in
3. If spreads behave then next week every corporate will want to issue bonds at these rates, especially with no data volatility, also gets them ahead of potential Fed volatility the following week
4. Bull flattening shouldn't keep going unless equities actually crack but all signs point to rotation not outright selling
5. 2y at 4.70 is only pricing 2 more hikes (remove the last 2 insurance cuts), don't think it can price less hikes without cold inflation prints which are now >4 weeks away
6. 10y at 5.05, who wants to buy 10y with a 4-handle? 4.98 is 50% retrace
7. This is still a long-term bond bear market right? You buy consolidations after breakouts to catch the potential face ripping reversals. Then you reset the shorts. You don't chase reversals until you have conviction in fundamentals changing.
I sold my duration longs today and cut my flattener in half. I want to be short duration next week if nothing fundamentally changes by Friday.
US2v10 now 38bp with -3bp today from hot CPI. Next target is 50% retrace from Sep23 low of 17bp to Oct8 high of 54bp, which is 36bp and should hit before Friday catalyst.
IMO Bessent adding a new question to Friday's primary dealer survey (cancel/reduce 20y auction sizes) is a no cost lever that opens door but doesn't box him into actual changes at Nov QRA. I do think he pulls that lever on Friday, but curve will bear steepen if he doesn't.


When Mnuchin added the question on sizing new 20y on 1/17/2020, he preceded with surprise press release on 1/16/2020 at 6pm. Perhaps we get a news bomb Thursday night before the scheduled Friday 12pm release. home.treasury.gov/news/press…

Something to consider for all those thinking BOC won't hike (Oct pricing only 27%)...
RBA minutes: considered arguments for not hiking, one reason was falling housing prices, but analysis suggested even large falls in housing prices would only have modest effects on spending
RBA has already hiked +100bps after cutting -75bps in 2025