

Ex-IB. Ex-startup founder, $100M+ exit. Former Special Operator. Defense tech, AI infra, Space, BTC, public market asymmetry.
Joined May 2026
- Tweets5.1K
- Following134
- Followers38K
- Likes12.5K






Pinned Tweet
New account, so here’s the short version.
I started at JPM.
Built a company.
Sold it for $100M+.
Served in places where risk was not theoretical.
Now I spend my time looking for public companies sitting at the intersection of capital, technology, and strategic necessity.
Defense tech.
AI infrastructure.
Space.
Bitcoin.
Critical infrastructure.
I am not here to post 50 tickers and celebrate the ones that work.
I am here to find the few names where the market is using the wrong frame.
Old category.
New asset.
Messy transition.
Right team.
Massive demand pull.
That is where the asymmetry usually lives.
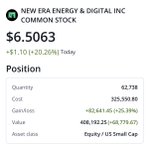
$NUAI has been hammered. High $7s after the Vistra PPA, now in the $2s.
I've talked about this name a lot, so I'm not going quiet now. I've made some bad calls before and I'll prob make more. I don't think this is one of them.
The co controls 493 acres in Odessa w/ a signed 20-yr PPA for up to 207MW from Vistra. LT the site has potential for up to 1.4GW. Power is still one of the biggest bottlenecks in AI infra, and I don't think the mkt appreciates what this asset could be worth w/ the right tenant.
Mgmt. has been substantially rebuilt w/ real experience in hyperscale DC development and financing.
But a PPA isn't a lease. And a lease isn't a finished, income producing DC.
The co still needs a tenant, construction financing on decent terms, permitting and ultimately delivery. Dilution is a real concern, particularly at these prices, and financing costs aren't getting easier. None of this is trivial.
At a mkt cap of c.$300M, I think the asymmetry is extraordinary if mgmt pulls this off. The opportunity hasn't deteriorated anywhere near as much as the price.
I added yesterday at $2.82. Position: 120,888 shares, plus long Jan '27 $7.50 calls.
Plenty of ppl here own this, some much higher. I won't tell you to hold, buy or sell. Make your own call.
If the tenant doesn't materialize, or the financing wrecks the economics for common SHs, my thesis changes.
Until then, I think the mkt has this one very wrong.
Some predictions for the rest of 2026 and into 2027. Let's see how wrong I am.
Rest of 2026:
I think earnings season confirms there's no meaningful slowdown in AI capex. If anything, I expect the hyperscalers to collectively raise their spending outlook and for rev/earnings guidance to continue improving.
Despite that, I expect AI infra stocks to keep chopping around. Macro, rates, financing fears and HF positioning continue to dominate price action. More violent moves in both directions.
I don't think we've seen the end of the volatility.
2027:
This is where I get particularly bullish.
A lot of the enormous contracts signed over the last 12 mths start converting into actual rev. Capacity gets delivered, GPUs come online and the numbers start catching up to the promises.
I expect hyperscaler capex to remain enormous, but the demand story to broaden well beyond them. Enterprises, govts, defense, big pharma etc. are only getting started.
I also think we'll see a much bigger separation btwn cos that can finance and execute the buildout and those that can't. Some will struggle badly, particularly those relying on constant dilution or expensive debt. Others will grow rev and earnings at rates that make today's valuations look ridiculous.
My bet is that several of the beaten down AI infra names materially outperform the Nasdaq in 2027 as the market starts rewarding actual execution and cash flow.
I also expect macro to become less hostile, although I've got far less conviction predicting rates, oil or geopolitics than I do compute demand.
What would make me rethink all this is sustained cuts to hyperscaler capex, meaningful contract cancellations, delays or financing conditions that prevent even the better operators from delivering.
Overall I'm extremely bullish on 2027. I think the fundamentals will continue improving well before stock prices consistently reflect them, and I expect that gap to close meaningfully next yr.
I reckon there's a very good chance we look back at some of today's prices and wonder what on earth everyone was so worried about.
Spot on.

This is heavily misleading. Yes, the cost per token is going down but with every token cheaper the use cases broaden. If it costs 1M tokens to run a query in an LLM and it costs 1T tokens to cure cancer the value per token is less, but the price someone is willing to pay in aggregate is way more because the returns are substantially higher. Or take robotics for example, where once it economically makes sense to train models on 1T tokens because of the returns on the other side. A bunch of companies enter in and set a baseline floor for that new use case in token consumption. Hence Jevons Paradox.
I’m starting to think half the HF industry has developed ADHD.
High conviction on Monday, panic selling by Thursday. Nothing material changed at the co.
For all their resources, leverage, risk limits and obsession w/ qrtly performance have turned a lot of them into incredibly impatient investors.
And I think that’s a massive advantage for retail.
If you can afford to sit tight while the supposed professionals lose their shit, you have an edge they simply don’t.
3 of my highest conviction holdings, each exposed to what I think will be among the biggest growth opportunities of the next decade.
Intelligence becoming abundant. Warfare becoming autonomous. Connectivity from space.
$IREN - My favorite name in the entire AI trade. Landlord, Power, DCs, GPU cloud and a growing software layer. Contracts w/ $MSFT, $NVDA, @AnthropicAI and other tier 1 customers. The contracted rev ramp is enormous and I think the market is badly underpricing both the existing business and what the platform can become. I see substantial upside to FMV from here. The scale of compute needed over the next decade is hard to comprehend and very few cos are positioned to deliver it like $IREN from business and r/r POV.
$ONDS - Closest thing I've found to a 1 of 1 autonomous defense platform. Drones, counter-UAS, loitering munitions, ground robotics, stratospheric ISR and the software tying it all together. $PLTR partnerships, $1bn+ cash and rev growing at an insane rate. I think the valuation is completely disconnected from the opportunity and the rev trajectory ahead. Autonomous warfare is going to be enormous and I believe $ONDS is worth substantially more than the market is giving it credit for.
$ASTS - D2D cellular from space. Partnerships w/ AT&T, Verizon, Vodafone etc. Ordinary phones connecting directly to satellites. This one's harder to value bc so much depends on launch cadence, execution, competition from $SPCX and the eventual economics of the network. It's much more of a venture bet than the other 2. But at $40 I think the asymmetry is incredible if they can pull it off.
What I like is that the underlying bets are very different. $IREN needs to finance and execute the buildout. $ONDS needs to win contracts and scale across defense programs. $ASTS needs to launch and commercialize its network.
Obvs all 3 can get hammered together when the market turns on high beta. We've seen that plenty.
But I don't own these just bc I think their industries will change the world. I own them bc I think the upside relative to what I'm paying today is enormous.
Particularly $IREN and $ONDS, where I think the market is massively underestimating the rev and earnings these cos can generate over the coming yrs, and the valuations that would justify.
My best guess at what happened in AI infra / high beta this week.
Mostly mechanics stacked on macro, not some grand conspiracy.
Rates, oil and inflation spooked the market. Again. The AI credit scare kicked in w/ $CRWV bonds trading below 80 cents and concerns about financing spreading across the sector.
AI infra was already a crowded HF trade. Once the selling started, risk limits, margin calls, leveraged ETF rebalancing, options hedging and stop losses likely amplified the move.
Narrative contagion. Problems at one co suddenly became problems at every co, regardless of their actual financing, customers or economics.
I suspect a large chunk of the selling was funds reducing exposure and ppl being forced out rather than investors suddenly changing their LT views.
As usual, I struggle to believe fundamentals deteriorated anywhere near as quickly as prices did.
Not advice but forced sellers eventually run out and dare I say, there are some real discounts out there.
Okay, a bit of a longer one but wanted to share some of my own internal thinking on AI infra. I'm as bullish as one can be, but I do spend a lot of time trying to work out where I could be wrong.
I think demand for compute is going to be enormous. Everyone talks about hyperscaler spending, but that's before most enterprises, govts, healthcare, robotics and defense have even really got going. And as inference gets cheaper I don't think demand slows. I think ppl just use a ton more of it.
Then there's the physical side. You need actual power, grid connections, energized land. These things take yrs. You can't throw $ at them and expect capacity to appear overnight.
And ironically, expensive capital could be great for the cos that survive it. If a bunch of marginal projects can't get financed, that's less supply arriving down the road. Even better for whoever already has contracts, prepayments and financing in place.
That's broadly what keeps me bullish.
Here's what bothers me.
For starters, I could be completely right about AI demand and still wrong about the economics of supplying it. Railroads, airlines, telco. Incredible industries, real demand, enormous amounts of SH capital destroyed.
What if compute gets commoditized faster than I expect? Models get more efficient, $ per GPU hour falls, margins get squeezed. Or everyone builds against these enormous forecasts and too much capacity arrives at once.
Depreciation is another one I keep coming back to. GPUs cost a lot and better hardware keeps showing up. What's the residual actually worth when the first contract rolls off? How much more capex just to stay in the game? Nobody really knows and everyone's modelling it like they do.
Then financing, which genuinely is a worry. You can have real customers, incredible contracts and impressive growth, and still leave common SHs with very little if you keep raising on bad terms. You can watch the thesis work while your share of it keeps shrinking.
There's customer concentration too. Some of these cos lean on a handful of counterparties, several are VC backed and burning cash themselves. If liquidity dries up across that group, a bunch could fail together.
Another thing I think about is the hyperscalers simply slowing down for a while. Doesn't require demand to fall. They could spend a few qrts digesting what they've already built or committed to. For cos spending billions against continued growth, even a temporary pause could be very painful.
And who actually captures the value here? Could be the models, the apps, the chipmakers or the end users. Not necessarily the cos spending billions building the thing.
And I do wonder whether this time really is different. I know how dangerous that sounds.
Railroads made moving things cheaper. The internet made moving information cheaper. AI is making intelligence itself cheaper. We're talking about replacing or augmenting an enormous amount of cognitive work across practically every industry, and I don't think anyone has a real idea how much demand that creates as the cost keeps falling.
There's also who's paying for all this. The hyperscalers are some of the most profitable cos on earth, and govts increasingly see AI as a national security issue. This isn't just speculative capital chasing an opportunity. For some of these buyers, falling behind might be more expensive than overbuilding.
That said, parts of this absolutely rhyme w/ telco. Especially the leveraged cos borrowing billions against future demand and contracts that haven't been delivered yet. The demand for internet traffic was real too. Didn't stop a lot of SHs from getting wiped out.
I struggle to find a historical comparison for what this technology becomes. Human behaviour, speculative excess and capital cycles are probably identical to every other boom. The thing driving them might not be.
So yeah, still extremely bullish. We're very early and the eventual scale is going to surprise even the bulls.
And obvs valuation matters enormously. A co can have many of the problems above and still be a fantastic investment if the market has already priced in a disaster that never happens.
But being right about demand isn't enough. I want to be right about who gets paid for supplying it, what I pay to own a piece of that business and what's left after the debt, capex and dilution.
The thing that bothers me most isn't AI failing. It's AI succeeding beyond our wildest expectations while a lot of investors lose a fortune financing it.
Really good work by @matt_solomon10 on $IREN here.
What caught my attention wasn’t the upside case. It was that at $28, his model values the co roughly around a scenario where it signs no new 2027 business.
I think that says something about how the AI infra trade has changed this yr.
First the market rewarded anyone w/ a credible plan to build.
Then it rewarded whoever controlled scarce assets. Power, land and sites that could actually be developed.
Now it seems increasingly unwilling to pay for capacity until there’s a credible path to getting it contracted, financed and delivered.
I understand the skepticism. You can have enormous demand and sign incredible contracts, but if the cost of delivering that capacity eats the returns, SHs still get crushed. Financing terms matter prob just as much as financing availability. A project can be fully funded and still leave very little for commons.
What’s interesting to me is what happens now. If expensive capital stops marginal builders bringing capacity online, the demand doesn’t disappear. It means less supply arrives when the market expected it to.
And if demand keeps growing, the cos that already have power, financing and customers could find those assets worth a lot more. $IREN and $NBIS are the two I own on that basis.
I’m still very bullish on AI infra. But we’re entering a period where the difference btwn owning an ambitious plan and owning a business that can deliver one clearly matters a lot.

Follow-up to my downside post: here's my base case for $IREN through calendar year-end 2027 (my numbers, NFA, I'm long). I've tried to keep it conservative.
What has to happen:
• MSFT: H2–4 delivered by year-end '26, per the original plan. Recent reports make a slip into Q1 '27 possible, but that's inside the grace period (~Apr 1) and worth only ~$2–3/share near-term. The ~5-yr service term starts at delivery/acceptance, so revenue gets pushed back, not lost, and the MSFT GPU loan doesn't wait on acceptance.
• First 2027 contract Nov '26–Jan '27, likely the Childress retrofits
• ~455 MW of unsold 2027 capacity: about half signed by Mar '27, all by Jun '27
• Pricing $18–20M per MW/yr, at or below recent 3-yr deals (>$20M per management) and well below the ~$25M they say they're discussing. Depending on the customer mix, I'd honestly be disappointed not to see ~$25M on most of the 2027 capacity
• 45–55% prepay + GPU-backed loans (Mackenzie's covers ~90% of GPU cost), so customers and lenders fund most of the GPUs
• A ~$2B capital raise by Jun '27 (could be debt, a convert or equity). To stay conservative, my targets assume it's all equity at ~$35 (hope this is wrong but market is being a bully)
What that's worth (value/share):
• Dec '26: ~$28–42 (~$28, roughly the already-signed book and about today's price, if the first contract slips to Jan; ~$42 if the retrofits sign by Dec 31)
• Jun '27: ~$69–71
• Dec '27: ~$97 at $18M/MW, ~$106 at $20M
All targets are per share after dilution, and the share count depends on the price, because most of the converts only convert well above today's price:
• 2029/2030 notes convert at $13.64/$16.81: already in the money, ~30M shares
• 2032 + Jun-2033 notes at $51.40
• Dec-2033 notes at $73.07
• 2031 notes at $85.63
Share count at each target (net of capped calls):
• ~$28–42 (Dec '26): only 2029/2030 convert → ~450M shares
• ~$70 (Jun '27): + the $51.40 notes + the $2B raise → ~545M
• ~$97 (Dec '27): all six convert → ~594M vs ~394M today
At $97 that's ~100M from converts (which also wipes out all ~$6.75B of convert debt, so it's a debt-for-equity swap, not pure dilution), ~57M from the $2B raise, ~35M of employee awards and ~6M from the NVIDIA warrant. Value/share checks out: the model's Dec '27 equity value is ~$57.8B, and ~$57.8B ÷ ~594M ≈ $97.
Upside case ($22–25M/MW, most capacity signed by Mar '27, a Sweetwater anchor): ~$115–128 by Dec '27, ~$155+ if the multiple re-rates a turn.
Downside (no contracts at all + MSFT delayed): ~$22–26.
If you force a probability weighting (floor 25% / base 50% / upside 25%), you get ~$83–91 for Dec '27. To be clear, I don't love valuing it this way. I'm not in this name for a blended average; I'm in it because, top down, I think the upside is the most likely outcome: power and energized capacity are the bottleneck, and IREN has a lot of both. Even so, at ~$28 the market is pricing the floor as the outcome, not a 25% chance of it.
Not in my numbers yet: Mirantis. It's clearly making progress, and I'd like some color from management on the mix of bare metal vs. managed cloud. By next year I'd love to see the Mirantis software layer showing up as upsells and pricing power on top of raw capacity especially for certain contracts.
What gets us there: one 2027 contract at a good price with a real prepay. Nov 5 is the first check.
Every cycle has a price you’ll later swear you’d never see again. This might be one. Sized to be wrong, positioned to be right.
A lesson from days like today is to keep cash on hand.
There's obvs a clear trade-off btwn being fully deployed and holding cash. You can run the math on what you give up during a rally vs. what you gain by having capital available during a sell-off.
For me, I'm happy to be deployed up to a point on my equities sleeve, but I want at least 30% available for days like today. I think the ability to pick up discounted shares / calls can more than offset the drag from sitting on cash.
That's not to say today is the bottom or we cant go lower but my sense is that sellers are starting to exhaust themselves.
And I love fighting someone who's exhausted.


Been patiently waiting for an entry into $CIFR.
Decided to start today w/ 65 Jan ’28 $15 calls at $3.20 rather than commons.
Will see how this develops.

If you were unlucky enough to buy near or at the top in a lot of the classic FinX names, you’ve sat through drawdowns of 50% or worse this yr.
I’ve been in the thick of it too.
It’s easy to talk about conviction and volatility when everything is going up. Living through it is a completely different experience, and nobody who hasn’t done it understands just how long a yr feels when you’re down.
Worse when the index is at ATHs. You’re not just losing money, you’re watching the easy version of this work out fine without you.
If you’re still in the game after all that, respect.
I'm genuinely struggling to read this market.
On one side, the AI buildout looks as compelling as ever. Demand for compute is enormous and obvious, capacity is scarce and the scale of the contracts being signed is truly insane.
On the other, the market is hammering many of the cos expected to deliver that capacity. Rates are high, financing is expensive and suddenly everyone is asking whether the economics justify the capex.
I understand both sides. A co can have incredible demand and still be a terrible investment if the cost of delivering it under delivers returns. Equally, the market can price in a financing disaster that never shows up - it in of is already with a lot of circular financing (much of the economy is like this anyway but it's harder to see).
What's strangest to me is the broader market sitting near ATHs while parts of AI infra feel like a full blown bear market. A bunch of names down 50%+ easily.
My conviction in the LT buildout hasn't changed. I think the market is badly mispricing some of these businesses and that several will be worth substantially more in a few yrs, like orders of magnitude more.
But here's something important about how I approach risk.
I'm generally very bullish and willing to push the limits on position sizing. The single most important thing for me is that I cannot be forced to sell.
I don't use margin. Most of my wealth sits outside this public equity book in a safety sleeve of fixed income, bonds, uncorrelated HFs and other investments.
That structure affords me the luxury of being wrong. I can be wrong on timing for yrs, or even wrong outright on individual investments, without jeopardizing my financial position or being forced to liquidate at the worst possible time.
That's how I reconcile my appetite for risk with my approach to managing it. I'm willing to tolerate enormous volatility in this part of my portfolio precisely bc I've structured the rest of my wealth to withstand it.
I don't know when this market will turn or what finally changes sentiment. But I remain extremely optimistic on what's being built, and I've put myself in a position where I can afford to wait and my hunch is that that's a good call.
Brian is not a finfluencer but I’d bet many folks would want him to be.
Great take on $ASTS.

Not sure about where the SP will be, but assuming the following are true, which look at least in the realm of possibility
-TMUS signs
-JLeo announced
-Gov’t awards are clarified
-Ligado is approved
-beta (10-15 hrs coverage ) for US is in the hands of 400m JV subscribers before the Starlink constellation is up
Do you think the market will see value in a near term open source D2D counterbalance to Starlink that is working before their constellation is up? How will they value this?
Do you think the government will allow a monopoly in D2D, or do everything in its power to enable competition?
Do you think Starlink will dilute enough, especially with their AI investments, to acquire any of the top 3 to expand their spectrum holdings? What would that do to their multiple?
Ex-US, do you think Musk is popular with the governments of the EU, India, Japan, Australia, Mexico, Canada? Or do you think they’ll seek a sovereign solution where they own their data sovereignty?
A few things I think investors put far too much weight on:
- A bank raising or lowering its PT. The number means very little on its own. What changed in the assumptions behind it?
- BlackRock or Vanguard showing up in a 13F. Seeing them on the register tells you almost nothing about their conviction or why they own it.
- IR being responsive to retail. Nice but doesn’t make the co more valuable or improve execution.
- Mgmt. saying they’re in advanced discussions. Again nice but discussions aren’t contracts. Counterparty, economics and commitments are what matter.
- A strategic partnership announcement. Unless there are real commercial obligations attached, it can amount to nothing.
- A senior hire or a big name joining the board. Hiring someone impressive isn’t the same as them changing anything yet (I have personal experience w/ this).
- The stock moving 20% on no news. That changes your opportunity, not the business.
- A famous investor or FinX account taking a position. You don’t know their size, horizon, hedges or why they own it (unless they tell you).
What I actually watch:
- Contracts signed on commercially meaningful terms.
- Capital secured on terms that don’t wreck you.
- Revenue converting into cashflow.
- Execution against dates they set themselves.
- Whether capital raised creates more value p/share than it costs you.
- Unit economics.
- Whether the asymmetry still exists at today’s price.
Any of the things in first list can matter. But ask yourself what actually changed about the business, its economics or your thesis. If the answer is nothing, you're confusing news with progress.
You don’t need people to agree with you. You need enough disagreement to create asymmetry and enough humility to know when they’re right and you’re wrong. The goal isn’t to win the argument on X. It’s to actually make money.

Whether you’re an AI bull or bear be thrilled so many investors think you’re dead wrong. The gap between what AI believers and skeptics see has never been bigger. And current valuations leave plenty of room for either side to be spectacularly right or wrong. That’s where the opportunity is.
Stop getting pissed at people who disagree with you. If you’re right those people are the reason there’s still so much money to be made.
Anyway happy Friday everyone. life is good. Hook ’em
Got called a scammer this week by someone who’s never spoken to me.
So here’s the deal.
I post what I own, what I paid, what I’m up/down and what I think. I’ve explained the $100m+ exit including what that number actually meant for me. I’ve said the book you see here is only part of my wealth. I post screenshots of positions, trades and prems. I chat to lots of folks via DMs constantly and give away everything I’m willing to share about how I think.
I sell nothing. No course, no sub, no paid room, no signals. The only money this account makes is whatever X pays creators.
I’ve also been clear about what I want. Reach. A large audience might give me access to ppl I otherwise wouldn’t have if/when I decide to build again.
I’m anon bc I value my privacy. That’s really it.
I’ve told you I’ve had a pretty unusual life experiences across SpecOps, finance, building and selling a co and now managing my own capital. I try to turn what I’ve learned across all of it into something useful for ppl here, for free.
Those are things I’ve told you about myself. Believe them or don’t. The screenshots are receipts. My bio isn’t.
At some point there’s nothing left to show short of putting my LinkedIn and my passport on the timeline.
And none of this means you should outsource your judgment to me. Quite the opposite.
Don’t fall for fallacies, don’t confuse randomness with skill. Look at the evidence, understand the incentives, find the truth as best you can and then be brave enough to make your own decisions.
That’s basically the only thing I want anyone to take from this account.
And when someone calls a stranger a scammer with nothing behind it, apply the same standard to them.
Good luck friends.
- TCL