

Investor | $3M personal portfolio | 25–30% CAGR over 8 years. I write about earnings, valuation & long-term compounding. Not financial advice
Singapore
Joined July 2025
- Tweets1.2K
- Following203
- Followers463
- Likes386






Ames uses hydrogenolysis, which consumes molecular hydrogen to break and saturate hydrocarbon chains.
Even with an inexpensive catalyst, the overall process must account for hydrogen production or procurement, compression, delivery, safety systems and energy requirements.

Our NGP Pilot Plant is demonstrating consistent, repeatable performance across changing polyolefin feed compositions. 👉 investors.adurocleantech.com…
The latest 75-hour campaign processed approximately 758 kilograms of polymer across three controlled blends, progressing from 100% polypropylene to higher polyethylene content, with product-quality indicators consistent with prior campaigns. After changes in process conditions, the system returned to target operating conditions approximately two hours sooner than in the comparable prior run, a measurable indication of improving process control.
Saipem is already receiving NGP operating data as part of Early Works engineering for our FOAK Program at @Chemelot. We expect the next stage to include longer campaigns using waste-plastic materials from prospective FOAK feedstock partners.
$ACT.TO $ADUR #CleanTech #EcoInnovation #ChemicalRecycling #PlasticRecycling

ALT Graphic that reads: "Aduro Reports 88.8% to 90.8% Condensable Hydrocarbon Yield Across Changing Polyolefin Feeds in 75-Hour NGP Campaign". An image below shows workers in hard hats working with the pilot plant.

New interview from $ROOT CEO Alex Timm
A few observations:
1. You can tell Root is confident in their market position and that they're leading from a position of strength
2. Root is telling their story more. Momentum will come back with a good quarter.
roundtable100.com/asset/root…

Yes, that's ofc not the only criterion. I am bullish this company. It's just a strong signal - not a standalone filter :)

100% agree. The biggest question for me is the new user onboarding given the funnel intake has changed with Ai LLMs
You are good at many things, but this just doesn't make any sense. You are basically saying that in 5 years, it's going to be a $2T company!
Assume a 20x PE, they would have to make ~$100B in earnings. Today, that is ~$15B. The estimates say it's growing by ~5-7%. Let's take high side, 10%, you are talking about net income of $24B, no where close!
Let's assume higher growth and give a 30PE for your case to work. Basically you are saying the company will grow the revenues by 20% CAGR for next 5 years, reaching to ~$36B net income that might then command this PE and hence maybe justify this.
Please stop giving useless targets.
I don't disagree with the fact that it's a great company trading at a good valuation, but let's please be realistic.
And the CEO buys in as well. Don't bet against them betting their own money. Time will tell. I'm bullish $BABA


This $BABA sell off does not make much sense to me. They are basically diluting a ~3.5% to raise some money in HK for international cloud expansion as they can't use their RMB local cash. The management has already stated the strong ROI (2.5-3 yr break even).
Buying opportunity imo. We'll add.
I see all the chatter about $RDDT and yes if you look at the metrics it looks like a great business with strong moat today. But, the whole discovery funnel works on the new user to land on the reddit webpage, scroll and read through the answers he is searching for and then start engaging. If the top of the funnel, the discovery phase, is fundamentally changing due to how users are discovering answers, doesn't that change the Reddit thesis? This hasn't happened yet, but 10 years down the line, what is to say - people will fundamentally shift the way they consumer search.

The Compound Atlas retweeted
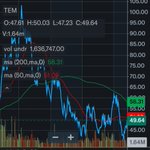
$TEM this is going to $60
