

$18 million in student loan forgiveness for teachers. Former teacher who now specializes in financial planning and student loan planning for other educators.
Check out my links page
Joined January 2022
- Tweets4.5K
- Following347
- Followers1.1K
- Likes2.5K



If you thought the student loan landscape was crazy before, it just got 10x crazier!
One new loan...
One new consolidation...
One wrong move...
And you could lose access to old repayment plans, payment caps, and forgiveness opportunities.
Don't navigate student loans by yourself!
Let's go through your situation in a one-hour student loan consult:
k-12planning.com/student-loa…
It's wild that a subset of the financial industry will recommend a Roth conversion without a tax projection.
Every company in my junk mail and LinkedIn messages: "What if we could book you 20-25 extra meetings per month"
Me: "Heck no, that's WAY too many meetings!"
I talk with teachers about their money...
Every day!
There are a few things that come up time and time again...
Let's talk about them:
k-12planning.com/post/the-4-…

David Gourley, EA, M.Ed retweeted
When I see a student loan question come up over and over, I know a blog post needs to be written on the topic.
Here is what I see every single day in the student loan forums:
"Why does my statement show a large payment increase in one year?"
Here is your answer:
k-12planning.com/post/why-do…
When I see a student loan question come up over and over, I know a blog post needs to be written on the topic.
Here is what I see every single day in the student loan forums:
"Why does my statement show a large payment increase in one year?"
Here is your answer:
k-12planning.com/post/why-do…
You've got 90 days to leave the SAVE plan and choose a new repayment plan.
Where can you go:
ICR
IBR
PAYE (if you qualify)
RAP (won't show up until July)
PAYE and ICR will sunset in 2028.
You can go to studentaid.gov/idr to see your options.
Need help determining the best path moving forward?
calendly.com/k-12planning
David Gourley, EA, M.Ed retweeted

The fastest way to spot a useless financial advisor?
“I can’t give tax advice”
“Ask your CPA”
Tax planning 𝘪𝘴 financial planning
Varying payment counts towards PSLF can benefit from a consolidation...
But you need to do it ASAP!
Consolidation loans processed after July 1, 2026 will ONLY be eligible for RAP (Repayment Assistance Plan).
It's going to be another wild few months in the student loan world!
Just casually changing someone's life this fine Monday evening.
$41,000 in student loans gone.
21 years of payments.
19 years of public service.
$466 per month of additional income (no longer going towards student loans).
“Do I really need a financial planner?”
A lot of the talking heads say no...
But after reviewing tons of real situations, I keep seeing the same pattern:
Missed strategies.
Missed timing.
Missed opportunities.
And it shows up as:
1. Paying more in taxes than you should have
2. Avoidable student loan payments
3. Inflated ACA premiums
4. Inefficient cash flow decisions
Financial advice shouldn't be about product sales.
It’s about not overpaying for life.
So many public servants are STILL sitting on their own personal golden ticket...
And they don't even know!
I do student loan consultations every single week...
And I consistently see situations like this one.
Look at the date at the top of the letter (April 22, 2026).
Look at the date of effective forgiveness (December 31, 2024).
For 18 months, they have been paying on loans that could have been forgiven.
And they didn't even know that they qualified.
Tons of things changed with the IDR Waiver...
Which is over now but the impact of it remains.
Immediate forgiveness is out there for so many older teachers/public servants!
Let's get a consultation scheduled if you want to review your situation!

Student loan consult client sold a property and had a very low tax year...
We immediately did an income recertification to get them a $0 payment moving forward.
Student loan planning is so powerful!!!
(old payment was $550 per month)


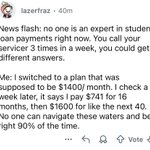
When you say "no one".......
I saw this on Reddit, but the same thing pops up on all social media.
Student loans are confusing.
But there are some people who understand it inside and out.
You just have to find the right person!

It can sound crazy to file your taxes MFS compared to MFJ...
Until you realize you can save $10,000 per year in student loan payments.
If you've got student loans, make sure to have a tax projection run both ways!!!
All of this is why I get paid to help people navigate PSLF and the student loan system.
People are confused.
People are angry.
And loan servicers don't help actually answer your questions.
I'm here to help if/when you need help!!!

This is absolutely insane
- This American borrowed $96,000 in student loans for a bachelors degree
- She’s already paid back $165,356
- She still owes $220,810.73
Again, she only borrowed $96,000
“I have paid almost double what I even borrowed in the first place, and I owe so much money. I am running backwards at this point”
How is this legal? This is such a scam. This is why students can’t pay off their loans, the terms are beyond predatory