

The deal and funding database built for biopharma. Curated deal comps, company profiles, pipelines, dedicated analyst support so you do better research faster
San Mateo, CA
Joined January 2017
- Tweets485
- Following249
- Followers461
- Likes100





Median licensing payments varied significantly by development stage across 2024–2026 YTD.
Find additional biopharma deal data and charts on DealForma.

Large-cap biopharma continued to pay higher upfronts for later-stage assets in 2026 YTD.
Find additional biopharma deal data and charts on DealForma.

Big pharma’s sourcing from Chinese biopharma continued to accelerate in 2026.
Find additional biopharma deal data and charts on DealForma.


A few large transactions drove cardiovascular dealmaking in Q3 2026. Partnership and M&A deal counts fell from Q2, while venture and IPO capital rose.
Read our research
na2.hubs.ly/H08t5bk0


Biopharma M&A activity cooled in Q3 2026, while licensing upfront payments remained relatively steady.
Find additional biopharma deal data and charts on DealForma.

Deal flow across healthcare, therapeutics, and medtech continued to slow in Q3 2026.
Find additional biopharma deal data and charts on DealForma.

Autoimmune dealmaking shifted to larger checks in Q3 2026. IPOs returned, while venture funding cooled.
Read our research
na2.hubs.ly/H08kpTd0

Stifel remains optimistic on biotech into 2027, expecting renewed M&A, strong capital markets, and continued pharma demand to support the sector despite near-term macro and political headwinds, with market & transaction data provided in part by DealForma.
na2.hubs.ly/H08knQ90

Q3 2026 dealmaking cooled across every channel, with value falling faster than volume.
Read our research
na2.hubs.ly/H08dHFj0

In H1 2026, reverse merger and SPAC activity grew in breadth, not scale; more companies reached the public market, but each carried far less upfront value.
Read our research
na2.hubs.ly/H089tk00

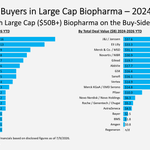
During H1 2026, large-cap biopharma R&D partnering was defined by concentration and back-weighted economics. A small group of buyers drove most deals and dollars, led decisively by Eli Lilly.
Read our research
na2.hubs.ly/H07Z5qC0

Large-cap biopharma M&A in H1 2026 turned narrow. One company dominated deal flow, one therapeutic area absorbed most of the capital, and a small group of names accounted for the rest.
Read our research
na2.hubs.ly/H07TLpT0

Antibody dealmaking shifted from licensing to buyouts in H1 2026, with ADCs and bispecifics at the center. Partnerships stayed big but paid less upfront. M&A surged. Venture held firm, and IPOs stayed thin.
Read our research
na2.hubs.ly/H07xK5_0

AI and machine learning drove biopharma’s biggest capital events in H1 2026, though dealmaking turned selective after an intense Q1.
Read our research
na2.hubs.ly/H07qlb80

Medtech, medical devices, digital health, and wearables M&A activity remained active through H1 of 2026, even as headline value cooled.
Read our research
na2.hubs.ly/H07mXx90
