

Full Time “Investor” and Part Time Degenerate || Founder of the South Park Investment Theory 💅
Chinatown, Manhattan
Joined February 2024
- Tweets738
- Following420
- Followers132
- Likes315





Pinned Tweet
Throwback to when I became the Founder of the South Park Investment Theory.
Thesis states that over any period of time, investing in stocks mentioned on South Park will outperform the S&P 500.
Shoutout to my pupils and critics below:

🎯

the final user interface is now fairly clear, or at least more clear than ever before:
language (text / voice) in → intelligence → text/voice out or generated interface out (if needed) → repeat.
i suspect this is likely going to be the default in how you will interact with every computing device / agent you ever interact with in the future. in every single context.
You’re telling me I can buy $NKE Nike at 2014 levels?!?!?!?
Positioning for a long-term investment into Nike, one of the strongest brands in the world next to Louis Vuitton, Rolex, and Apple.
DTC revenues are struggling both domestically and in China, with profits being squeezed by higher tariffs and a jump in the tax rate.
Not a great story, but the stock feels like it’s almost fully priced in the negatives. Doubles if Nike can figure out how to be “cool” again.

Need private shares for Neuralink ASAP. $1T company in 10 years and potentially the biggest company in the world in 20.

I use SPACs as an indicator for market bottoms. When SPACs start trading at or below NAV, we’re usually close to a bottom. Investors are being forced to exit their SPAC positions just to cover losses elsewhere from overleveraged or margined trades.
$RTAC already had a few days under NAV. I’m watching $AEXA (the Chamath SPAC, probably the most widely followed on the market) and waiting for it to trade below $10.50 before I buy back into tech and growth stocks.
Until then, it’s hard to buy common equity in a turbulent market with Ukrainian crypto bros on 20x perps and the average Robinhood trader with access to 2x leverage at 6%.


I’m buying Sweetgreen $SG common stock before earnings tonight.
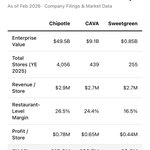
My favorite thesis is buying good companies under $1B enterprise value. $SG currently trades at a ~$700M market cap / ~$950M EV.
$SG generates the same revenue per store as Chipotle $CMG and CAVA $CAVA but trades at a 5 to 8x discount on EV per store.
$SG has the best price to quality ratio of any fast casual product on the market today. The revenue is there, the issue is profitability, which makes it a strong candidate for either an acquisition or an operational turnaround through cost restructuring.
As long as per store revenue holds at these levels, this is a great stock to own from a relative value perspective.

Just started a position in Fiverr $FVRR before earnings release tomorrow morning.
Trading at a $200MM Enterprise Value. Peaked at a $6B EV in 2020.
My thesis for 2026-2028 is that there will be a major return of the gig economy and digital nomadism as corporate unemployment continues to rise (52% of Gen Z college graduates are underemployed).
Not only will there be a rise in micro entrepreneurs looking to outsource aspects of their business through Fiverr, but there will also be talented, underpaid or laid off employees who choose to monetize their skills on Fiverr as opposed to staying in a corporate job.
Fiverr is the eBay of this market, acting as both intermediary and fulfillment center to make transactions as seamless as possible.
Its only major competitor is Upwork, which should also benefit from these economic shifts but is nowhere near as cheap. The key difference: Upwork has buyers post jobs and wait for contractors to reach out, while Fiverr flips the model. Sellers list their services and buyers come to them. I think that’s the stronger approach.
Just bought another 1,000 shares of $RTAC at $10.54. NAV is $10.33 so a $10k incremental investment has a $280 downside.
Learned my lesson on patience with $TINV merging to $GRND after 2.5 years.
Good deals take time. November 2027 would be 24 months + 6 month extension.
My opportunity cost at the moment is cash. Equities have too much macro risk and the market seems to rinsing away over levered players.
People forget about the 2022/23 stock market. Difference is in 2026 the average retail investor is somehow given access to 10x leverage through crypto.
$DAAQ DA. Seems like a poor deal. This SPAC was supposed to be circle.

$DAAQ 🤝✅ OFFICIAL DA:
Old Glory Bank and Digital Asset Acquisition Corp. Announce Business Combination Agreement to Create a Texas Company Publicly Listed on Nasdaq
globenewswire.com/news-relea…
$FVRR Fiverr trading at a $340MM Enterprise Value is absolutely insane. There is no scenario where this company goes bankrupt under current operations or is acquired for less than $1B.
Stock passes every quantitative test. 6x Forward looking P/E, 4x FCF to EV. This tech company MAKES MONEY and trades at T-Shirt store multiples.
My issues are qualitative, webapp is incredibly slow and glitchy. They seem to be innovating (rewards, gamification tiers). But they can’t quite figure out the right pivot as they reposition for AI and the return of the gig economy.
I think this stock is 1 move away from a 10x if Fiverr is to position itself as the shovel salesman during this AI Gold Rush.
As a reminder this stock went from $18 to $300 during COVID. I’ll be buying Jan 2027 $25 Calls for $1.00.

After $CAEP ended up being a Hookah Flavor company, who knows what CEPF will end up being.
Not too interested in $CEPF, as it seems these Cantor SPAC’s are becoming founder share arbitrage vehicles.
You’re unable to view this Post because this account owner limits who can view their Posts. Learn more
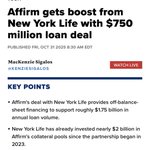
$AFRM Affirm balance sheets so much consumer debt that they now have a $750MM credit line with New York Life.
This is the strongest short candidate on the market as consumers seem to be overextended on buy now, pay later loans as a replacement to credit card debt.
Credit reporting companies have also started to account for buy now, pay later defaults and late payments, which in turn will impact individuals’ interest rates for home loans, car loans, and other major purchases.
Big short level snowball effect. If buy now, pay later loans were an investment note it would be priced at 30%++ as it seems to be the most junior level of personal debt and the first to be wiped.


Keep an eye on $BLUW. $BLUWW warrants are already moving. Many people will profit off of this charade. Put yourself in position to be one of them alongside Trump & his team who purchased this CITGO SPAC in November.
Warrants trading at $0.70 which means $1k would unlock $12k if commons were to trade at just $20.

$BLUW could be the most interesting way to play the Venezuelan crisis.
Previously had a bid to purchase CITGO assets under old SPAC regime. The SPAC has now been purchased by Trump Team (Devin Nunes & Co).
Deal couldn’t get done with either of the 3 bidders due to Venezuelan national oil stating a “forced sale”.
Only a Trump related company would be able to get a deal like this done. Too many lawsuits, corruptions, and liens owned by Russia & China.
May be a bit messy for a SPAC to unlock value for shareholders, but could be interesting to track.
You’re unable to view this Post because this account owner limits who can view their Posts. Learn more


You know there’s a bubble when you sit with a Real Estate Private Equity veteran and they can’t stop talking about $Pengu / Pudgy Penguin Coin.
Top signal for crypto or bottom signal for Real Estate?
Either way he got me to throw some bread in this thing. YKTV


I’m getting back into $SLG SLGreen now that yields are at 7%. This is not only a bet on NYC office market but also a levered bet on interest rates coming down.
Jan 2028 call options trade at an insanely low price given this is a REIT with low forward looking Implied Volatility (IV).

$SG Sweetgreen trading under $1B Market Cap & Enterprise Value. There is no scenario where Sweetgreen gets acquired for less than $3B.
Strong candidate for automation (currently have 20 workers at 1740 Broadway location in NYC and 4-5 workers at random sites in DC). $16 salad is also becoming one of the cheaper lunch options in NYC.
Love the tailwinds here as other lunch options continue to get more expensive and more disgusting at the same time.
