

An E-Commerce Financing RWA Platform on @BNBCHAIN, backed by @mhventures @Maple_block @moonhillcap @ArcaneGrp
BNB Chain
Joined May 2013
- Tweets202
- Following22
- Followers208K
- Likes135





BNB Chain is becoming a serious market for tokenized assets.
Tokenized equities are already seeing substantial trading activity, alongside deep DEX liquidity, stablecoin markets and established lending protocols. Few ecosystems offer this combination at comparable scale.
Keep an eye on the BNB Chain ecosystem. You might want to know your way around it soon.


Your Vault won't be the only thing worth checking on Dow.
Soon, the little things you do here might start adding up.
Stay close.

Financial infrastructure scales when new technology fits into existing workflows.
The same applies to credit. Financing becomes more scalable when it is built around how businesses already sell, receive payments and manage cash flow, rather than requiring them to change how they operate.


Additional rewards for @volo_sui Dow Stables S1 Vault are now claimable in $U on @BNBCHAIN through Dow Protocol.
Eligible participants on Volo Sui can claim rewards by binding a BNB Chain Wallet together with whitelisted Sui Wallets at app.dowprotocol.com/points
Dow Protocol will continue expanding @UTechStables’s use in e-commerce financing and onchain settlement.

Dow Protocol’s Institutional Vault has completed its subscription period, with $7.93M in total deposits.
The capital now moves toward deployment into advances against merchant receivables from the world's largest e-commerce marketplaces, supporting a more efficient and scalable approach to working-capital finance through onchain infrastructure.


Not every tokenized asset should be expected to behave the same way onchain.
Credit is built around holding an asset against a stream of future cash flows. Its onchain value will therefore show up differently, not necessarily through constant turnover, but through how effectively that position can be used within financial markets.

On September 17, the SEC granted temporary, conditional relief to facilitate limited onchain trading of tokenized U.S. stocks. As regulatory pathways clear and issuance of real-world assets onchain accelerates, the most interesting question, besides how much is onchain and how much is used, is whether these markets behave like the ones they reference or differently enough to produce new signals and opportunities.
That's what this report set out to measure, across cash equivalents, credit, commodities and equities.
After Issuance: Reading the Onchain RWA Market → eu1.hubs.ly/H0yJP7G0
A fund can be onchain while its information remains offchain.
Tokenized ownership, 24/7 transferability, and smart-contract settlement do not automatically make the underlying risk more observable.
If portfolio data still arrives monthly, the investor is holding a digital asset with an analogue information cycle.
For onchain credit, the real upgrade is not just tokenizing the fund. It is shortening the distance between what happens in the underlying asset and what the investor can actually see.

Most credit data will continue to originate offchain.
The interesting question is whether lenders can verify its source and integrity before it reaches the credit engine.
This becomes particularly relevant for receivables and working-capital finance, where underwriting depends on transaction and settlement data generated continuously by the underlying business.

Trust in official statistics underpins evidence-based policy. But how can a user know a data set they downloaded is the one the publisher released? Our new paper proposes an answer. bit.ly/3UxqxcX
#SDMX #OfficialStatistics

Dow Protocol Institutional Vault is now open.
A dedicated access point for institutional capital into short-duration e-commerce credit.

One under-discussed effect of blockchain in private markets is that it can change the minimum economical size of a financial asset.
Traditional private credit carries a lot of fixed overhead: documentation, reporting, reconciliation, servicing and administration. Below a certain ticket size, the economics simply stop working.
Automation changes that threshold.
When more of the lifecycle can be standardized and executed programmatically, smaller and more granular assets become economically viable to finance at scale.
That may be one of RWA’s more important effects: not just making existing markets more efficient, but making previously uneconomic markets financeable.

Dow Protocol Institutional Vault is coming soon.
Built for institutional capital seeking exposure to short-duration, self-liquidating e-commerce credit.
The Vault is backed by an overcollateralized receivables pool with ≥120% coverage, alongside structured repayment controls and short underlying asset duration.
Institutional access to real-world working capital, built around repayment.

The next phase of RWA is not about moving the real economy onchain.
It is about rebuilding the financial infrastructure around it.
The SEC’s new tokenized-stock framework is a useful signal. The company stays the same. Shareholder rights stay the same. Securities law still applies. What changes is the market infrastructure around the asset: public ledgers, auditable smart contracts and programmable execution.
That is a more realistic model for how onchain finance scales.
Businesses do not need to become crypto-native for their financing to become programmable.
The real opportunity is to upgrade the financial layer without asking the underlying economy to rebuild itself.

Blockchain spent years building parallel financial rails.
Now the more consequential shift is happening in the opposite direction: regulated finance is absorbing the rails.
That is when tokenization starts becoming infrastructure rather than a market category.

💡 Did you know?
Swift's blockchain-based ledger has been built with our community and is ready for use, with 17 early adopter institutions helping bring tokenised value into the regulated financial system.
Find out how the industry is preparing for always-on, cross-border value transfer: swift.com/payments/payment-i…
#CrossBorderPayments #SwiftBlockchainLedger
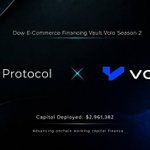
Dow Protocol’s E-Commerce Financing Vault on @volo_sui has completed Season 2 deployment.
A total of $2,961,382 has been deployed to finance short-duration merchant receivables on the world’s largest e-commerce platform.
Dowsure has an exclusive partnership with the world's largest e-commerce platform, under which merchant sales proceeds are repaid directly by the platform, without passing through the merchant. This materially reduces collection and diversion risk, contributing to an industry-low average default rate of 0.05%.
Each financing position is also backed by 120% receivables coverage, creating a substantial protection buffer against settlement delays, adjustments, or other uncertainties.
Risk management is powered by platform-native merchant data accessed directly from the underlying e-commerce ecosystem, enabling underwriting based on real operating and transaction data rather than self-reported information. The underlying credit-risk infrastructure is also used in financing workflows by multiple top-20 global banks.

Dow Protocol retweeted

The Dowsure Stable Vault remains open for deposits until SEP 9.
Grab the opportunity for a 15% target APR for your USDC, powered by real-world yields.
Deposit now: volosui.com/vaults/0x11fc786…

1/ Dowsure Vault: Round 2 is now open 🔓
volosui.com/vaults/0x11fc786…
A new round of the Dowsure Vault, launched in collaboration with @DowProtocol and Dowsure, is targeting 15%+ APR on USDC.
Deposits are open until September 9, giving users one week to enter
More details below👇

Goldman Sachs, Bank of America, Citi, Deutsche Bank and 17 other financial institutions are now preparing a joint dollar stablecoin.
The important shift is not another stablecoin entering the market. It is that programmable money is moving closer to the banking system that originates and finances real-world economic activity.
For Dow Protocol, that convergence matters. We are building the credit side of the same infrastructure: bringing commerce receivables, funding, ownership and repayment onto programmable rails.

24/7 markets will become inevitable as banks begin overhauling the accounting and ledger infrastructure beneath the financial system.
And once that foundation changes, the rest of the asset lifecycle will have to follow.
Trading, underwriting, servicing and settlement cannot remain on different clocks forever.

Exclusive: Securitize will become NYSE’s first digital transfer agent, allowing it to create shares for stocks and exchange-traded funds as digital tokens on a blockchain on.wsj.com/3Nyh8Pj

Figure and its partners have already originated over $30 Billion of loans through a blockchain-native capital-markets stack. BIS argues why this matters since tokenization can collapse messaging, reconciliation and settlement into one operation, replacing multiple ledgers and hand-offs with a single programmable asset record.
Dow Protocol applies that architecture to commerce credit with ownership, repayment waterfalls and risk triggers are defined at origination, not reconciled after the fact. The important point is not that blockchain eliminates credit risk, but that live underwriting plus pre-programmed cash-flow control leaves fewer places for risk to hide.
