

Searching for high-quality, durable businesses with robust competitive advantages, runways for growth, and a history of creating value for shareholders.
Joined January 2022
- Tweets2.6K
- Following485
- Followers7.6K
- Likes4.1K
Pinned Tweet
For those curious, here's the latest state of the Durable Value Creators investable universe. I was working through the physical infrastructure group when I made the initial post, but I've now officially included it. There's a couple changes to the core but largely the same ideas


The backlog grows but what about the actual production rate? Wasn't there a report that the US burned through ~5 years worth of missile production in Iran in just 40 days? The backlog numbers don't excite me until the defense industry shows they can increase throughput. $LMT $RTX

Lockheed Martin received $55B in net new missile orders in Q3.
That's their largest quarterly backlog growth ever.
Total Missiles Backlog: $143B
$LMT

$GE is such a great business. I'd even go as far as saying it's a top 5 business in the world. The biggest challenge for investors today is determining what's a fair value to pay for it?

GE Aerospace CEO: "We delivered strong results this quarter as solid demand drove orders up 49%, with strength in commercial services up 23%, total revenue up 18% and EPS up 36%. We are raising our 2026 guidance across the board..."
$GE: -4.4% Today

Anecdote: I remember there was an interview with the former CEO of Verisk $VRSK floating around a while back. I believe he did a lot of dancing around the term "monopoly" and just how entrenched their insurance data solutions were. Now contrast that with $FICO's CEO...

We had a good thing, you stupid son of a bitch. We had the mortgage. We had the score. We had the one number every lender in America was too scared to close a loan without.
Thirty years. Thirty years, nobody could touch you.
You could’ve shut your mouth, raised prices bit by bit, and made as much money as anyone ever needed. It was perfect.
But no — you had to jack it 17x in five years. You and your pride and your earnings calls. You just had to squeeze every drop. You just had to be the man.
If you'd known your place and let the pennies roll in, we'd all be fine right now.
Instead, VantageScore's through the door, the FHFA's circling, and the whole industry's finally asking why they ever needed you at all.
$FICO

I tagged $FICO as uninvestable in my own notes months ago when Pulte kept bringing them up. It's unfortunate for the people that were lured in by the financial metrics and past performance. To me, the stock/company has entered Chinese equity (under the Chinese govt) territory...
Biggest problem for Rollins $ROL imo is too much of the business (close to half?) is residential pest control services. Even without AI search risk/fears, that was always the lower quality side of the business (higher churn), plus the only real pool for left for M&A deals.
Oh man, read the headline fast and saw “engineered-castings”, “Precision” and “Berkshire” and thought $GE had just pulled off a blockbuster deal.

GE Aerospace $GE just announced that it has agreed to acquire engineered-castings maker Consolidated Precision Products from private investment firms Warburg Pincus and Berkshire Partners for
$11.75 billion

$TTD was added to the S&P 500 on July 18th 2025 while trading at ~$81/share and exits the index just over a year later at $14/share. Great job by the selection committee.

My controversial data center opinion is I'd rather we stop growing almonds over stop building data centers. Almonds are overrated as a food, an ecological waste, and do a lot of damage to US commercial beehives, which must be shipped in to pollinate the almond trees each spring.


NewMarket's $NEU legacy business is fuel additives and lubricants. But in recent years they've done a couple acquisitions for mission-critical space/rocket/propulsion materials... AMPAC and Calca. These still represent a small % of total sales but will be interesting to watch.


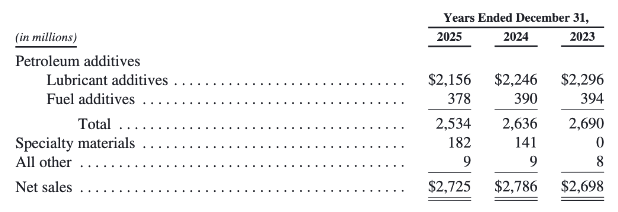
The additives business is largely a melting ice cube when you consider the slow but ongoing transition to EVs. They also historically don't do M&A, and both of these deals were acquired from the same PE firm. So it's yet to be seen if this is a new chapter for the company. $NEU
And one note, to be fair to $NEU. Not all of the lubricants business is tied to gasoline/cars. There are industrial machinery, heavy equipment, and hydraulic end markets as well. But the overall industry isn't a growth story when fuel additives + engine oil are a large %.
Don't the Musk comments just reaffirm the $GEV thesis? The blades aren't the only choke point in turbine manufacturing, but SpaceX making their own could help GEV fill its own blade orders. Plus, it highlights just how important power is, more important than chips at this point.
Surely there was a better choice out there than the CFO of Rivian... $GEV


Kinda funny, I work for a Fortune 500 that is absolutely not a tech company and we've had access Opus for a while now. We also get the newest versions relatively quickly. I can't imagine being limited to such inferior models, no wonder so many people are skeptics.


Thinking about it some more, I'm not a huge fan of this deal. Cleanwater1 is more of a capital equipment-based company than a customer opex chemical company like other WQ businesses. Rich multiple too. Will VES prove to be a meaningful difference maker? We'll see. $VLTO
New acquisition for Veralto $VLTO announced today in their water quality segment.
"Over the next few years, Veralto expects Cleanwater1's sales to continue growing in the low double-digits, leveraging Trojan Technologies customer relationships, servicing the installed base"

A fully valued deal of a lower quality business model suggests the pool of available deal targets in water quality isn't wide or deep. That being said, if management can cross-sell Clearwater1 solutions, expand margins, and grow recurring sales, it's not the worst deal. $VLTO
New acquisition for Veralto $VLTO announced today in their water quality segment.
"Over the next few years, Veralto expects Cleanwater1's sales to continue growing in the low double-digits, leveraging Trojan Technologies customer relationships, servicing the installed base"
Finding a good investment opportunity should go beyond the company's moat. While yes, that moat is important for survival, an insufficient reinvestment runway and/or inability to capture incremental profits can greatly limit the long-term compounding story.
On margin capture, it depends on switching costs, industry concentration, and cost to customer relative to value. Is there an alternative product, and is it worth switching? Class 1 rails (oligopoly, no alternative) vs P&C insurance (fragmented, customers choose cheapest option).
Waste Connections $WCN is a good example of a company that fits this framework. High barriers to entry industry create the moat, healthy amount of opportunity for tuck-in waste hauling deals, good pricing power on contract renewals for an essential service that communities need.