

The European Credit Research Institute (ECRI) is an independent non‐profit research institute focused on European credit and payments markets.
Brussels, Belgium
Joined July 2018
- Tweets796
- Following152
- Followers430
- Likes251




European Credit Research Institute (ECRI) retweeted

⚡ 𝗧𝗵𝗲 𝗻𝗲𝘄 𝗖𝗼𝗻𝘀𝘂𝗺𝗲𝗿 𝗖𝗿𝗲𝗱𝗶𝘁 𝗗𝗶𝗿𝗲𝗰𝘁𝗶𝘃𝗲 𝟮 (𝗖𝗖𝗗𝟮) 𝗶𝘀 𝗻𝗼𝘁 𝗮𝘀 𝘁𝗲𝗰𝗵𝗻𝗶𝗰𝗮𝗹 𝗮𝘀 𝗶𝘁 𝗺𝗶𝗴𝗵𝘁 𝘀𝗲𝗲𝗺. The rising cost of living is taking a toll on households, and even on our democracies. Rules that protect consumers, prevent over-indebtedness and thus protect financial stability are urgent.
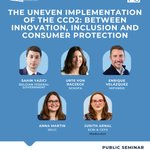
Today I had the pleasure of moderating an @ECRI_CEPS and @CEPS_thinktank event on "The uneven implementation of the CCD2: between innovation, inclusion and consumer protection", with four brilliant panellists: Sahin Yazici (Belgian Federal Government), Urte von Raczeck (SCHUFA Holding AG), Enrique Velazquez (Mifundo) and Anna Martin (BEUC - The European Consumer Organisation).
🔹 𝟭𝟲 𝗠𝗲𝗺𝗯𝗲𝗿 𝗦𝘁𝗮𝘁𝗲𝘀 𝗮𝗿𝗲 𝘀𝘁𝗶𝗹𝗹 𝗹𝗮𝘁𝗲. The deadline was 20 November 2025. On 1 October the Commission sent reasoned opinions to the 16 that have still not communicated complete transposition. The rules apply from 20 November 2026.
🔹 It is an ambitious directive that brings 𝗕𝘂𝘆 𝗡𝗼𝘄 𝗣𝗮𝘆 𝗟𝗮𝘁𝗲𝗿 into its scope. Marginal in 2008, with the first CCD, today it is used by around one in three consumers. The risk is not one BNPL purchase, but the accumulation of many, which can lead to over-indebtedness.
🔹 It also introduces mandatory forbearance measures and allows Member States to cap interest rates.
🔹 For the coming months, some Member States will apply the old CCD and others the CCD2. Even when all have transposed, there will be more than 20 national options and discretions. But the deviations that matter are not the legal, visible ones. They are the ones we cannot see, and they stand in the way of a single market for credit.
🔹 𝗧𝗵𝗲𝗿𝗲 𝗶𝘀 𝘀𝘁𝗶𝗹𝗹 𝗻𝗼 𝘀𝗶𝗻𝗴𝗹𝗲 𝗺𝗮𝗿𝗸𝗲𝘁 𝗳𝗼𝗿 𝗰𝗿𝗲𝗱𝗶𝘁. Cross-border credit is limited, but mobility is not marginal: 𝟰𝟱 𝗺𝗶𝗹𝗹𝗶𝗼𝗻 consumers have a financial history in more than one country. Yet lenders often do not even ask whether an applicant has a financial history in another market.
🔹 And when they do, getting the data is hard. Credit bureaus differ widely. Data exchange is bilateral, bureau to bureau, and rudimentary. Even with the same wording, definitions differ and there are gaps.
🔹 The CCD2 opens a door. Article 6 on non-discrimination, with Articles 18 and 19 on creditworthiness assessment and databases, can allow better data flows and a real internal market for credit.
✅ 𝗧𝗵𝗿𝗲𝗲 𝗽𝗼𝗹𝗶𝗰𝘆 𝗿𝗲𝗰𝗼𝗺𝗺𝗲𝗻𝗱𝗮𝘁𝗶𝗼𝗻𝘀:
1️⃣ Immediate transposition and enforcement. Late Member States must close the gap now. Supervisors must then enforce the rules and keep monitoring the market, for instance through mystery shopping.
2️⃣ Supervisory awareness of mobile consumers. Supervisors should track what happens to consumers who move, and quantify how many struggle to get credit.
3️⃣ Clear legal grounds for data processing. Without them, Articles 6, 18 and 19 will not turn into real cross-border data flows.
Many thanks also to my dear colleagues Alice Orlandini, @FredHAndersson and Carlota Cabarrocas López for their support in making this event a success!

🙌Thanks to all who joined today’s discussion on the uneven implementation of #CCD2!
Our panel explored the problems it aims to solve, its application across Member States, as well as cross-border credit data transfers in the Single Market 👇
@CEPS_thinktank

🚨 Last chance to register for our seminar "The uneven implementation of the CCD2" on 19 October!
With:
🎙️Sahin Yazici, Belgian Federal Government
🎙️Urte von Raczeck, @SCHUFAHoldingAG
🎙️Enrique Velazquez, Mifundo
🎙️Anna Martin, @beuc
REGISTER HERE: tinyurl.com/4mbvt9ry

🗓️SEMINAR: "The uneven implementation of the new Consumer Credit Directive" | 19 Oct at @CEPS_thinktank
With:
🎙️Sahin Yazici, Belgian Federal Government
🎙️Urte von Raczeck, @SCHUFAHoldingAG
🎙️Enrique Velazquez, Mifundo
🎙️Anna Martin, @beuc
Register here: tinyurl.com/4mbvt9ry

European Credit Research Institute (ECRI) retweeted
⚡ 𝐓𝐨𝐤𝐞𝐧𝐢𝐬𝐞𝐝 𝐝𝐞𝐩𝐨𝐬𝐢𝐭𝐬 𝐚𝐫𝐞 𝐧𝐨𝐭 𝐚𝐛𝐨𝐮𝐭 𝐟𝐚𝐬𝐭𝐞𝐫 𝐩𝐚𝐲𝐦𝐞𝐧𝐭𝐬
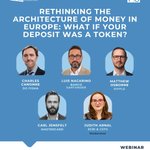
Today I moderated an @ECRI_CEPS and @CEPS_thinktank webinar on tokenised deposits and the future of digital money with Charles Canonne, Carl Jensfelt, Luis Nacarino and Matthew Osborne. Many thanks to all of them for a very rich discussion.
Some broad ideas that emerged:
🔹 𝐓𝐡𝐞 𝐯𝐚𝐥𝐮𝐞 𝗼𝗳 𝘁𝗼𝗸𝗲𝗻𝗶𝘀𝗲𝗱 𝗱𝗲𝗽𝗼𝘀𝗶𝘁𝘀 𝐥𝐢𝐞𝐬 𝐞𝐥𝐬𝐞𝐰𝐡𝐞𝐫𝐞. In Europe, instant payments already allow money to move almost immediately. The potential added value of tokenised deposits lies in programmability, conditional payments, automation and closer integration between the cash and asset legs of transactions. Use cases include securities settlement, corporate treasury, trade finance and supply chains.
🔹 𝐓𝐨𝐤𝐞𝐧𝐢𝐬𝐞𝐝 𝐝𝐞𝐩𝐨𝐬𝐢𝐭𝐬 𝐚𝐧𝐝 𝐬𝐭𝐚𝐛𝐥𝐞𝐜𝐨𝐢𝐧𝐬 𝐚𝐫𝐞 𝐧𝐨𝐭 𝐭𝐡𝐞 𝐬𝐚𝐦𝐞 𝐭𝐡𝐢𝐧𝐠. Tokenised deposits remain liabilities of commercial banks and retain the features of traditional deposits, including remuneration. Stablecoins are subject to a different legal and regulatory treatment, with interest prohibited under MiCA, but may have advantages in cross-border use and portability across platforms. The two may compete in some areas and complement each other in others.
🔹 𝐈𝐧𝐭𝐞𝐫𝐨𝐩𝐞𝐫𝐚𝐛𝐢𝐥𝐢𝐭𝐲 𝐰𝐢𝐥𝐥 𝐛𝐞 𝐝𝐞𝐜𝐢𝐬𝐢𝐯𝐞. Tokenised deposits cannot develop as isolated islands. They will need to interact with deposits issued by other banks, central bank money, tokenised securities and regulated stablecoins. Public-private cooperation will be essential. Initiatives such as 𝐏𝐫𝐨𝐣𝐞𝐜𝐭 𝐀𝐠𝐨𝐫á, led by the BIS together with the IIF, and 𝐒𝐖𝐈𝐅𝐓’𝐬 𝐝𝐢𝐠𝐢𝐭𝐚𝐥 𝐥𝐞𝐝𝐠𝐞𝐫 are already exploring how to overcome these interoperability challenges.
🔹 𝐓𝐞𝐜𝐡𝐧𝐨𝐥𝐨𝐠𝐢𝐜𝐚𝐥 𝐧𝐞𝐮𝐭𝐫𝐚𝐥𝐢𝐭𝐲 𝐦𝐚𝐭𝐭𝐞𝐫𝐬. A deposit should not become a fundamentally different instrument simply because it is represented on a distributed ledger. However, questions around transferability and bearer instruments show why legal clarity may still be needed. As the EBA has just reminded the Commission in the MiCA review, the EU still lacks a harmonised definition of “deposit”.
🔹 𝐒𝐢𝐧𝐠𝐥𝐞𝐧𝐞𝐬𝐬 𝐨𝐟 𝐦𝐨𝐧𝐞𝐲. As different forms of public and private digital money coexist, users need to remain confident that one euro is still one euro.
Rather than one form of digital money replacing all the others, we may be moving towards a multi-money ecosystem in which different instruments serve different purposes but remain interoperable.
Many thanks to our panellists and Alice Orlandini and Beatriz Pozo for organising this webinar.
Stay tuned for more ECRI updates!

🚨Last chance to register for our webinar "Rethinking the architecture of money in 🇪🇺: what if your deposit was a token?"
🎙️Charles Canonne @EU_Finance
🎙️Luis Nacarino @bancosantander
🎙️Matthew Osborne @Ripple
🎙️Carl Jensfelt @Mastercard
Register here👉 tinyurl.com/ckdrxmbv

🗓️SEMINAR | 19 October at @CEPS_thinktank | Consumer Credit Directive
As the new Directive enters its final implementation phase, this event will take stock of how CCD2 is reshaping consumer credit across the 🇪🇺EU.
🔗REGISTER HERE: tinyurl.com/4mbvt9ry

European Credit Research Institute (ECRI) retweeted
⚡𝗠𝗶𝗖𝗔'𝘀 𝘁𝘄𝗼 𝘀𝘁𝗮𝗯𝗹𝗲𝗰𝗼𝗶𝗻 𝗰𝗮𝘁𝗲𝗴𝗼𝗿𝗶𝗲𝘀, 𝗘𝗠𝗧𝘀 𝗮𝗻𝗱 𝗔𝗥𝗧𝘀, 𝗯𝗼𝘁𝗵 𝗱𝗲𝘀𝗲𝗿𝘃𝗲 𝗮 𝘀𝗲𝗰𝗼𝗻𝗱 𝗹𝗼𝗼𝗸 𝗶𝗻 𝘁𝗵𝗲 𝗠𝗶𝗖𝗔 𝗿𝗲𝘃𝗶𝗲𝘄, 𝗻𝗼𝘄 𝗼𝗽𝗲𝗻 𝗳𝗼𝗿 𝗰𝗼𝗻𝘀𝘂𝗹𝘁𝗮𝘁𝗶𝗼𝗻.
Many thanks to @DigiEuro for inviting me to the DEA Summer Forum 2026 in Frankfurt, hosted by Mayer Brown Germany. I very much enjoyed participating in the panel 𝗢𝗻𝗲 𝗧𝗼𝗸𝗲𝗻, 𝗧𝘄𝗼 𝗥𝗲𝗴𝗶𝗺𝗲𝘀: 𝗖𝗮𝗻 𝗚𝗹𝗼𝗯𝗮𝗹 𝗦𝘁𝗮𝗯𝗹𝗲𝗰𝗼𝗶𝗻𝘀 𝗪𝗼𝗿𝗸 𝘂𝗻𝗱𝗲𝗿 𝗠𝗶𝗖𝗔? with Simon Seiter, Mykolas Majauskas and Stephan Mögelin, moderated by Johannes Schahn.
The main ideas I conveyed 👇
𝗢𝗻 𝗲-𝗺𝗼𝗻𝗲𝘆 𝘁𝗼𝗸𝗲𝗻𝘀 (𝗘𝗠𝗧𝘀)
🔹 𝗥𝗲𝘀𝗲𝗿𝘃𝗲 𝗿𝗲𝗾𝘂𝗶𝗿𝗲𝗺𝗲𝗻𝘁𝘀 𝗯𝘂𝗶𝗹𝘁 𝗼𝗻 𝗯𝗮𝗻𝗸 𝗱𝗲𝗽𝗼𝘀𝗶𝘁𝘀 deserve a rethink, especially for significant tokens (60% of the reserve). They increase the interconnection between stablecoins and the banking sector, and in a crisis that interconnection can act as an accelerator.
🔹 𝗔 𝘀𝘁𝗮𝗻𝗱𝗮𝗹𝗼𝗻𝗲, 𝗯𝗲𝘀𝗽𝗼𝗸𝗲 𝗿𝗲𝗴𝗶𝗺𝗲 𝗳𝗼𝗿 𝗘𝗠𝗧𝘀, as ARTs already have. Inspired by e-money law where useful, but not built by reference to it. Because EMTs are e-money, a CASP that transfers an EMT on behalf of a client, or holds it in a wallet, needs two licences and two supervisors (under MiCA and PSD2). A simpler framework with no overlaps is possible.
🔹 𝗦𝘂𝗽𝗲𝗿𝘃𝗶𝘀𝗶𝗼𝗻: lower the threshold for a token to be considered significant, and entrust the supervision of significant issuers to the ECB, given its expertise in this area of finance and in macroprudential supervision.
𝗢𝗻 𝗮𝘀𝘀𝗲𝘁-𝗿𝗲𝗳𝗲𝗿𝗲𝗻𝗰𝗲𝗱 𝘁𝗼𝗸𝗲𝗻𝘀 (𝗔𝗥𝗧𝘀)
🔹 𝗧𝗵𝗿𝗲𝗲 𝗼𝗽𝘁𝗶𝗼𝗻𝘀: remove the category; narrow it to commodity-referenced tokens; or remove it and bring multi-fiat tokens into the EMT regime.
🔹 𝗪𝗵𝘆: the concept is so broad that it creates legal uncertainty (is a given token a financial instrument under MiFID, an ART, or a Title II crypto-asset?); no other major jurisdiction has adopted it, and the UK and Hong Kong simply include multi-fiat tokens in their stablecoin concept; and the market has not taken it up: not a single ART has been authorised. The category looks like a remnant of the Libra/Diem episode, while financial markets went elsewhere.
#MiCA #stablecoins #DigitalEuro #DEASummerForum

European Credit Research Institute (ECRI) retweeted
🎉Happy to see 3️⃣ of my papers made it to the September think tank Review of the @EUCouncil 👇
1️⃣ 𝗠𝗮𝗱𝗲 𝗶𝗻 𝗲𝘂𝗿𝗼𝗽𝗲, 𝗶𝗻𝗮𝗱𝘃𝗲𝗿𝘁𝗲𝗻𝘁𝗹𝘆: 𝗼𝗿𝗶𝗴𝗶𝗻 𝗽𝗿𝗲𝗳𝗲𝗿𝗲𝗻𝗰𝗲 𝗶𝗻 𝗲𝘂 𝗽𝗿𝗼𝗰𝘂𝗿𝗲𝗺𝗲𝗻𝘁 𝗮𝗻𝗱 𝗳𝘂𝗻𝗱𝗶𝗻𝗴 for @CEPS_thinktank. Link: cdn.ceps.eu/2026/07/2026-09-…
2️⃣ 𝗦𝗵𝗮𝗿𝗶𝗻𝗴 𝗳𝗿𝗮𝘂𝗱 𝗶𝗻𝘁𝗲𝗹𝗹𝗶𝗴𝗲𝗻𝗰𝗲 𝘂𝗻𝗱𝗲𝗿 𝘁𝗵𝗲 𝗽𝗮𝘆𝗺𝗲𝗻𝘁 𝘀𝗲𝗿𝘃𝗶𝗰𝗲𝘀 𝗿𝗲𝗴𝘂𝗹𝗮𝘁𝗶𝗼𝗻: 𝗺𝗶𝗻𝗱 𝘁𝗵𝗲 𝗴𝗮𝗽 for @ECRI_CEPS. Link: cdn.ceps.eu/2026/08/ECRI-IDA…
3️⃣ ¿𝗔𝗳𝗲𝗰𝘁𝗮 𝗲𝗹 𝗿𝗶𝗲𝘀𝗴𝗼 𝗴𝗲𝗼𝗽𝗼𝗹í𝘁𝗶𝗰𝗼 𝗽𝗼𝗿 𝗶𝗴𝘂𝗮𝗹 𝗮 𝗹𝗮𝘀 𝗲𝗺𝗽𝗿𝗲𝘀𝗮𝘀 𝗲𝘂𝗿𝗼𝗽𝗲𝗮𝘀 𝘆 𝗲𝘀𝘁𝗮𝗱𝗼𝘂𝗻𝗶𝗱𝗲𝗻𝘀𝗲𝘀? 𝗨𝗻𝗮 𝗹𝗲𝗰𝘁𝘂𝗿𝗮 𝘀𝗲𝗰𝘁𝗼𝗿𝗶𝗮𝗹 𝗱𝗲 𝗹𝗮 𝗯𝗼𝗹𝘀𝗮 for @rielcano. Link: realinstitutoelcano.org/anal…
Link to list: consilium.europa.eu/en/docum…

💻Join us on 5 October for our webinar on tokenised deposits & the architecture of money in 🇪🇺!
🔵What are tokenised deposits & how do they differ from other forms of #digitalmoney?
🔵Can the EU's regulatory framework keep pace with their development?
🔗tinyurl.com/3ac2nvc4

The Payment Service Regulation is an improvement in the 🇪🇺's response to payment fraud, but leaves implementation problems unresolved.
🔍@judith_arnal argues against both fragmentation & centralisation. What the EU needs is interoperability by design.
🔗 tinyurl.com/ydadpkh3

European Credit Research Institute (ECRI) retweeted
My latest In-Depth Analysis for @ECRI_CEPS is out: 𝗦𝗵𝗮𝗿𝗶𝗻𝗴 𝗙𝗿𝗮𝘂𝗱 𝗜𝗻𝘁𝗲𝗹𝗹𝗶𝗴𝗲𝗻𝗰𝗲 𝘂𝗻𝗱𝗲𝗿 𝘁𝗵𝗲 𝗣𝗮𝘆𝗺𝗲𝗻𝘁 𝗦𝗲𝗿𝘃𝗶𝗰𝗲𝘀 𝗥𝗲𝗴𝘂𝗹𝗮𝘁𝗶𝗼𝗻: 𝗠𝗶𝗻𝗱 𝘁𝗵𝗲 𝗚𝗮𝗽
⚡ The PSR is a significant improvement in the EU's response to payment fraud. It moves beyond a model centred on identity and controls on individual PSPs, and recognises that modern fraud prevention requires shared intelligence. Even so, it leaves two major implementation problems unresolved.
🔹 𝗧𝗵𝗲 𝗳𝗶𝗿𝘀𝘁 𝗶𝘀 𝗶𝗻𝘁𝗲𝗿𝗻𝗮𝗹 𝘁𝗼 𝘁𝗵𝗲 𝗽𝗮𝘆𝗺𝗲𝗻𝘁 𝘀𝗲𝗰𝘁𝗼𝗿. The Regulation gives PSPs a clearer legal and data protection basis for sharing fraud-related information. But this legal certainty also instils rigidity: the categories of data that can be safely shared are set by statute, with no dynamic mechanism to adapt them as fraud typologies evolve. At the same time, national, sector-led, private and pan-European arrangements are emerging. If they develop different data models, taxonomies, suspicion thresholds, alert formats and governance rules, PSPs may face overlapping obligations in siloed systems.
🔹 𝗧𝗵𝗲 𝘀𝗲𝗰𝗼𝗻𝗱 𝗰𝗼𝗻𝗰𝗲𝗿𝗻𝘀 𝘁𝗵𝗲 𝘄𝗶𝗱𝗲𝗿 𝗳𝗿𝗮𝘂𝗱 𝗰𝗵𝗮𝗶𝗻. The PSR recognises that many scams originate outside the payment layer, involving platforms, hosting providers, search engines or electronic communications providers. Yet the obligation for non-PSP actors to cooperate is not as strong, systematic or complete as that imposed on PSPs. Fraud prevention cannot rely solely on PSPs or users reporting fraud after it has materialised; it also requires ex ante measures by upstream actors capable of disrupting scam infrastructure before a fraudulent payment is executed.
The analysis argues against both fragmentation and centralisation. The EU does not need a single, mandatory fraud database. It needs 𝗶𝗻𝘁𝗲𝗿𝗼𝗽𝗲𝗿𝗮𝗯𝗶𝗹𝗶𝘁𝘆 𝗯𝘆 𝗱𝗲𝘀𝗶𝗴𝗻:
✅ Common operational requirements for PSP-to-PSP information sharing.
✅ A federated FRIDA layer, led by the European Payments Council, connecting national, private and sectoral arrangements across SEPA and EPC payment schemes.
✅ Model protocols for cooperation with non-PSP actors, developed through the Commission-led platform on combating fraud.
✅ A first PSR review focused on whether the framework has produced a genuinely interoperable ecosystem of fraud intelligence.
The UK shows that a common fraud data model and a network-level view of fraud are attainable without a central operator. Australia shows that cross-sector intelligence works only when a binding duty to share is matched by an institution that actually routes it.
Link to paper in comments.

Congratulations to @judith_arnal on your new appointment as a member of the Advisory Council of the @ADBInstitute! ECRI is proud to see your expertise recognised at the international level and happy to celebrate this well-deserved achievement 👏

It will be an honour to serve as a Member to the Advisory Council of the @ADBInstitute for the term 2026-2028, starting on 11 September 2026. Thank you so much for the trust, dear President @ADBPresident Masato Kanda. I am committed to bringing my experience, engaging in open and evidence-based dialogue, and supporting ADBI’s important work in addressing the region’s most pressing economic and policy challenges.

European Credit Research Institute (ECRI) retweeted
📢 𝗡𝗲𝘄 𝗽𝗲𝗲𝗿-𝗿𝗲𝘃𝗶𝗲𝘄𝗲𝗱 𝗽𝗮𝗽𝗲𝗿 in the Capital Markets Law Journal (Oxford University Press), co-authored with @PabloZalba : "Competitiveness as a secondary regulatory objective in the European Union: a necessary complement to financial stability and investor protection".
The timing could hardly be better: it coincides with today's publication of the Commission's report on the competitiveness of the EU banking sector.
𝗪𝗵𝗮𝘁 𝘄𝗲 𝗮𝗿𝗴𝘂𝗲:
1️⃣ 𝗦𝘆𝘀𝘁𝗲𝗺𝗶𝗰, 𝗻𝗼𝘁 𝗶𝗻𝘀𝘁𝗶𝘁𝘂𝘁𝗶𝗼𝗻𝗮𝗹, 𝗰𝗼𝗺𝗽𝗲𝘁𝗶𝘁𝗶𝘃𝗲𝗻𝗲𝘀𝘀. Financial competitiveness is a system-level property: the capacity of the financial system to support long-term economic performance while maintaining resilience and consumer trust, not the profitability or market share of individual institutions.
2️⃣ 𝗙𝗿𝗼𝗺 𝗿𝗵𝗲𝘁𝗼𝗿𝗶𝗰 𝘁𝗼 𝗺𝗲𝗮𝘀𝘂𝗿𝗲𝗺𝗲𝗻𝘁. We operationalize it through4️⃣dimensions (financing capacity, profitability and value creation, resilience, and market participation and digital transformation), captured by 28 KPIs, which can be expanded or made more granular depending on the segment of the financial sector concerned.
3️⃣ 𝗔𝗱𝗱𝗿𝗲𝘀𝘀𝗶𝗻𝗴 𝘁𝗵𝗲 𝗼𝗯𝗷𝗲𝗰𝘁𝗶𝗼𝗻𝘀:
❓ Does a secondary objective inject ambiguity into supervisory judgment?
➡️ No: it bites only at the margin, once the primary objectives of safety, soundness, market integrity and investor protection are satisfied. And it is more transparent than the status quo, where competitiveness already enters deliberation informally, without structure or accountability.
❓ Is competitiveness too elastic a term?
➡️ So are financial stability and market integrity: the answer to conceptual openness is operationalization through indicators, not avoidance.
4️⃣ 𝗪𝗵𝘆 𝘁𝗵𝗲 𝗨𝗞 𝗺𝗼𝗱𝗲𝗹 𝗰𝗮𝗻𝗻𝗼𝘁 𝘀𝗶𝗺𝗽𝗹𝘆 𝗯𝗲 𝗶𝗺𝗽𝗼𝗿𝘁𝗲𝗱. The FSMA 2023 conferred the objective on the FCA and the PRA, bodies that combine rule-making and supervision within a single jurisdiction. EU governance is fragmented along two dimensions: regulation vs supervision, and EU vs national level. The ESAs lack autonomous rule-making powers, and direct supervision remains mostly national, with the ECB/SSM as the principal exception. Simply amending agency mandates would be insufficient.
5️⃣ 𝗢𝘂𝗿 𝗽𝗿𝗼𝗽𝗼𝘀𝗮𝗹. The EU legislator should anchor competitiveness in primary legislation as a formal secondary objective, cascading through the whole system: the Commission's legislative and delegated acts (with enhanced impact assessments), the ESAs' Level-3 instruments, and supervisory practice at both ECB/SSM and national level. Never a licence to relax prudential standards: a calibration principle disciplining discretion at the margin, backed by annual KPI reporting, benchmarking and independent reviews.
The article is not open access, but just drop me a message and I will share it bilaterally.
Link: academic.oup.com/cmlj/articl…

European Credit Research Institute (ECRI) retweeted
🆕 ‼️ 𝗣𝗲𝗲𝗿 𝗿𝗲𝘃𝗶𝗲𝘄𝗲𝗱 𝗽𝘂𝗯𝗹𝗶𝗰𝗮𝘁𝗶𝗼𝗻 in Journal of Financial Regulation and Compliance of Emerald.
𝗠𝘂𝗹𝘁𝗶-𝗶𝘀𝘀𝘂𝗮𝗻𝗰𝗲 𝘀𝘁𝗮𝗯𝗹𝗲𝗰𝗼𝗶𝗻𝘀 𝗮𝗻𝗱 𝗠𝗶𝗖𝗔’𝘀 𝗳𝗶𝗿𝘀𝘁 𝘀𝘁𝗿𝗲𝘀𝘀 𝘁𝗲𝘀𝘁: 𝗹𝗮𝘄, 𝗽𝗼𝗹𝗶𝗰𝘆 𝗮𝗻𝗱 𝗴𝗹𝗼𝗯𝗮𝗹 𝗰𝗼𝗺𝗽𝗲𝘁𝗶𝘁𝗶𝗼𝗻
🧵with main ideas

European Credit Research Institute (ECRI) retweeted

🙌A full room today for our CEPS-ECMI-ECRI seminar on simplifying 🇪🇺EU financial regulation & strengthening supervision, marking the conclusion of the latest CEPS-ECMI-ECRI Task Force (🔗final report here tinyurl.com/4pd35499)!
Huge thanks to our speakers and participants👏


Today, @judith_arnal will speak at @ASNEF_'s General Assembly, presenting key insights on the simplification of financial regulation👇
On 16 June at @CEPS_thinktank, we will continue the discussion presenting our latest report on the topic (🔗register: ceps.eu/ceps-events/more-fin…)!

European Credit Research Institute (ECRI) retweeted
Join us for our seminar on simplifying 🇪🇺EU financial regulation and strengthening supervision!
We'll discuss the findings of the latest CEPS-ECMI-ECRI Task Force Report (🔗tinyurl.com/4pd35499).
🗓️16 June, 13–14:30
📍@CEPS_thinktank
REGISTER HERE👉tinyurl.com/mwzpnkwp

Seven jurisdictions have legislated for #stablecoins. Rules converge on the surface, but three fixes are needed:
▶️Build mutual recognition architecture
▶️Make reserve composition politically visible
▶️Settle the yield question
READ HERE: tinyurl.com/nh9rynsu
✍️@judith_arnal

European Credit Research Institute (ECRI) retweeted
🆕My latest @ECRI_CEPS In-Depth Analysis paper is out: “𝗦𝘁𝗮𝗯𝗹𝗲𝗰𝗼𝗶𝗻𝘀: 𝗖𝗼𝗻𝘃𝗲𝗿𝗴𝗲𝗻𝘁 𝗿𝘂𝗹𝗲𝘀 𝗼𝗻 𝘁𝗵𝗲 𝘀𝘂𝗿𝗳𝗮𝗰𝗲, 𝗱𝗶𝘃𝗲𝗿𝗴𝗲𝗻𝘁 𝗿𝗲𝗴𝗶𝗺𝗲𝘀 𝗶𝗻 𝗽𝗿𝗮𝗰𝘁𝗶𝗰𝗲.”
A thread 🧵with main messages
