

Understanding Indian Stocks the Smart Way | Techno Funda Insights for Everyday Investors | Learn & Become Financially Free with Us | Disclaimer: No Buy/Sell Adv
Bangalore, India
Joined September 2024
- Tweets1.3K
- Following15
- Followers7K
- Likes258





Pinned Tweet
🪔 Diwali Special Offer!
This Diwali, we have a special gift for the investor community!
We have launched a FREE course to help investors learn and improve their understanding of the stock market.
Subscribe here:
financiallyfree.in/login/fre…
No payment. No hidden charges.
Simply subscribe to our website and start watching the course for FREE.
Happy Learning and Happy Diwali! 🪔
Happy Diwali, everyone! 🎉
This Diwali, we are sharing two CNC machine businesses that we recently covered in detail with our Financial Free community.
We did an in-depth study of these businesses together just a couple of weeks ago. Their latest quarterly results are also really good, and we believe both businesses have good potential over the next couple of quarters.
We have also shared the complete analysis videos with you for a detailed understanding of both businesses. Their financial models are also shared in the same thread.
1. Jyoti CNC Automation Ltd (CMP: 1020)
2. Macpower CNC Machines Ltd (CMP: 2299)
Disc: Info for only educational purpose and do not take buy/sell decision based on us.
#JYOTICNC
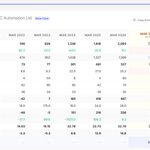
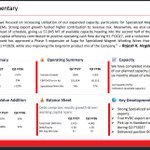
Jyoti CNC's main trigger is capacity. Its factory ran above 100% in peak months, so annual capacity rising from 6,000 to 16,000 machines by Q2 FY27 should let it work through its ₹4,848 crore order book (about 2.3 years of revenue). It also has aerospace and defence as its largest market (39% of revenue) just as FY27 defence procurement rises 24.6%, plus a doubled Huron plant in France guided to ₹300–325 crore revenue in FY27; a clean resolution of the French probe would remove the main overhang
FY27 Revenue Growth: Expects revenue to grow by 25% to 30% in FY27.
Margin Guidance: Expects to maintain a 25% consolidated EBITDA margin in FY27.
Volume Target: Targets dispatch of over 8,000 machines in FY27, with higher volumes expected in H2 (40:60 split).
This financial model is very very conservative.
Disc: No buy/sell.

#MACPOWER
Macpower's triggers are mix and volume: premium NEXA machines sell for about ₹29–32 lakh against ₹15–16 lakh for its standard range and are now ~40% of the order book, capacity is 2,500 machines a year with a new ₹50 crore, 13-acre site due within 12 months, and roughly ₹958 crore of bids (₹319 crore in defence) could convert into orders.
FY27 Guidance Upgrade: Management increased its revenue growth guidance from 30% to 35% for FY27.
Long-Term Growth: Expects to maintain 25% to 30% annual growth over the next three years.
This financial model is very very conservative
Disc: No buy/sell

We have launched a FREE course covering our PEAD strategy, supported by 3 best case studies.
We hope this course provides valuable insights and helps you better understand and apply the strategy.
Just subscribe and proceed with below link 👇
financiallyfree.in/login/fre…

🪔 Diwali Special Offer!
This Diwali, we have a special gift for the investor community!
We have launched a FREE course to help investors learn and improve their understanding of the stock market.
Subscribe here:
financiallyfree.in/login/fre…
No payment. No hidden charges.
Simply subscribe to our website and start watching the course for FREE.
Happy Learning and Happy Diwali! 🪔
Optiemus Infracom Ltd
#optiemus
The BIS compliance mandate creates a significant import-substitution opportunity for Optiemus, supported by a favourable regulatory environment.
Management has outlined ambitious expansion and revenue targets, with the expectation of improving margins as higher-margin businesses scale. Double-digit EBITDA margins could be achievable from FY28 onwards, subject to successful execution, capacity utilization and product mix.
Margins have started recovering sequentially, although they remain below historical levels.
An interesting emerging growth story worth tracking closely!
Disc: Only for edu.

Wishing you a very Happy and Prosperous Diwali! May this festive season bring immense light, growth, and success to your financial journey.🪔
Best Diwali Offer from Financially Free!
pages.razorpay.com/pl_TqSuED…

Last Diwali, we shared a detailed note on "Syrma SGS Technology Ltd at 780 levels". Since then, the stock has performed really well. We have also studied the company in depth with our community over this period.
#SYRMA is one of the best performers in the EMS sector.
Thank you so much for following us and being part of this journey!
Disc: No buy/sell recomm.
Syrma SGS Technology Ltd
Happy Diwali, everyone! 🎉 This Diwali, we’re sharing one of the businesses we recently covered in detail with our community. Here’s our Deep Research Note for you.
Syrma SGS Technology Ltd., a leading Indian EMS player since 2004, provides end-to-end solutions from design to large-scale manufacturing across automotive, consumer electronics, industrial automation, healthcare and railways, giving it a diversified revenue base.
Geography-Revenue : India ~77%; Exports ~23%.

KSH International Ltd
#KSHINTL | Q2 FY27 Concall Highlights
1. Capacity Expansion
• Phase 2 expansion at Supa is 96% complete.
• Total installed capacity has reached 57,845 MT.
• Board approved Phase 3 expansion with a capex of up to ₹185 Cr.
2. Volume Growth & EBITDA Guidance
• Management believes 26% volume growth is sustainable.
• Long-term sustainable EBITDA/tonne guidance increased from ₹75,000 to around ₹85,000 after Phase 3.
3. HVDC Opportunity & POWERGRID Approval
• Secured a trial order for specialised wires for two overseas HVDC transformers.
• Received POWERGRID approval for the Supa facility to supply wires for transformers up to 765 kV.
4. Export Growth Opportunity
• Aims to take exports back to their historical contribution of around 40% of revenue.
• Exports offer 3–4% higher margins.
• Focus on high-value products across T&D, EV and exports, while expanding international presence.
5. Improving EBITDA Per Tonne
Key drivers:
• Higher CTC product contribution.
• Increased export volumes.
• Rupee depreciation.
• Improved operational efficiencies.
6. International Business Outlook
• No slowdown observed among US customers despite discussions around AI data centre capex.
• Middle East business remains stable.
Overall View: A bullish concall, supported by improved long-term EBITDA/tonne guidance, capacity expansion, HVDC opportunities and a clear focus on exports and high-value products.
Disc: Info for edu.
KSH International Ltd
Q2 FY27 delivered a strong QoQ and YoY uptick across all key parameters, achieving the highest-ever performance.
EBITDA per Ton: Achieved a new high of approximately ₹1,01,454 per metric ton, up from ₹65,515 YoY, driven by a favorable product mix and higher exports.
EBITDA per Ton 55% YOY unbelievable.
#KSHINTL no buy/sell recomm, Info for edu.

Marine Electricals (India) Ltd
#MARINE has not conducted a concall yet. It has a substantial order book, entirely from the domestic market. Also, its data center orders are not directly linked to the AI/DC theme.


KSH International Ltd
Q2 FY27 delivered a strong QoQ and YoY uptick across all key parameters, achieving the highest-ever performance.
EBITDA per Ton: Achieved a new high of approximately ₹1,01,454 per metric ton, up from ₹65,515 YoY, driven by a favorable product mix and higher exports.
EBITDA per Ton 55% YOY unbelievable.
#KSHINTL no buy/sell recomm, Info for edu.
Ind-Swift Laboratories Ltd
#INDSWFTLAB
Concall Key takes.
1. Growth Guidance Reaffirmed, With Upside: Management reiterated >50% revenue growth for FY27 and hinted that FY28 guidance "might be revised and numbers might increase" — a rare bullish forward signal.
2. Margin Trajectory is Steep: Blended EBITDA target of 19-20% by Q4 FY27, with an internal team target of 22% next quarter — the company is firmly on track for 20%+ margins by year-end.
3. Long-Term Vision: ₹1,500+ Crore by FY30: The company is targeting a 20-25% revenue CAGR, aiming for ₹1,500+ crore topline by FY30, along with an additional 200-300 bps EBITDA expansion.
4. Capacity Headroom is HUGE: The Jammu plant is currently operating at only 70-75% capacity utilisation, allowing significant incremental revenue without major fresh capex. Strong operating leverage ahead.
5. CDMO: The New Growth Engine: CDMO revenue reached ₹65 crore in Q2 (versus ₹50-60 crore earlier). The company is targeting ₹100-130 crore incremental revenue in FY27 and ₹200-220 crore cumulative over two years from Viatris, Mannex and Aerotex deals.
6. Atorvastatin: The Breakout Molecule: Atorvastatin revenue more than doubled from ₹25 crore in Q1 to ₹58 crore in Q2. Ibuprofen is expected to contribute another ₹20 crore in Q3 and ₹20-25 crore in Q4. A significant CDMO ramp-up is underway.
7. New Business Segments & Geographic Expansion: Expanding into Peru, Mexico, Brazil, Rwanda, Congo, Cambodia, Ivory Coast and Benin through product registrations. Clarithromycin dry suspension is awaiting EU variation approval ahead of its expected launch.
8. ₹250 Crore CapEx + EU Unlock: The full ₹250 crore gross capex programme is on track, covering the Samba EU-GMP upgrade, Dera Wasi warehouse and R&D. The ₹45 crore Samba upgrade for EU-GMP/PIC-S is expected to unlock lucrative regulated-market exports from FY28.
9. Debt-Free + Hidden Synthemin Treasure: The company remains completely debt-free with robust cash reserves and holds a 7.80% equity stake in Synthemin Labs (API business internally valued at ₹7,000-8,000 crore). Potential partial monetisation could be an additional trigger in the coming quarters.
Management's conviction quote:
"We don't foresee any risk... orders are in hand, raw materials are in place, production facility is equipped — we just need to manufacture and deliver."
Disc: No buy/sell.
Ind-Swift Laboratories Ltd
#INDSWFTLAB great set of number beat the expectations.
Blockbuster numbers.
Disc: No buy/sell


Some companies have delivered results that came as a positive surprise to the market. Here are a few examples worth highlighting.
No buy or sell recommendations. However, it is worth noting that several textile companies have also reported strong numbers, exceeding market expectations.

The market has performed well over the last three trading days in November and has seen a strong recovery. The broader market has bounced back with significant improvement in market breadth. Hope all your portfolios are shining today!

Ramkrishna Forgings Ltd
An interesting conversation regarding #RKFORGE entry into the aerospace sector.

Ramkrishna Forgings Ltd
#RKFORGE
Excellent set of numbers! The presentation highlights strong volumes, capacity utilisation and order wins. An all-round performance across key parameters. Fantastic results! The concall is currently underway.
Disc: No buy/sell


$AMD double beat 👍

$AMD Q3’26 EARNINGS HIGHLIGHTS
🔹 Revenue: $13.40B (Est. $13.09B) 🟢; +45% YoY
🔹 Adj. EPS: $2.09 (Est. $1.95) 🟢; +74% YoY
Q4 Guide:
🔹 Revenue: ~$17B +/- 3% (Est. $16.23B) 🟢
🔹 Non-GAAP Gross Margin: ~55%
Segment Net Revenue:
🔹 Data Center: $8.55B; +97% YoY (Est. $8.27B) 🟢
🔹 Client and Gaming: $3.70B; -8% YoY
🔹 Client: $2.95B; +7% YoY (Est. $3.03B) 🔴
🔹 Gaming: $773M; -40% YoY (Est. $634M) 🟢
🔹 Embedded: $1.11B; +29% YoY (Est. $1.07B) 🟢
Announcements:
🔹 Helios: Anthropic, Meta, Microsoft, OpenAI and Oracle Cloud Infrastructure are running models on first AMD Helios rackscale solutions powered by MI450 GPUs and 6(th) Gen EPYC CPUs
🔹 HPE: Vultr will deploy first AMD Helios by HPE systems in a $12B deal
🔹 Versal AI Core XQRVC1902: space-grade SoC designed for missions lasting up to 15 years
Other Q3 Metrics:
🔹 Non-GAAP Gross Margin: 56%; +200 bps YoY
🔹 Non-GAAP Oper Income: $3.92B (Est. $3.67B) 🟢; +75% YoY
🔹 Adj. EBITDA: $4.16B (Est. $4.02B) 🟢; +71% YoY
🔹 FCF: $554M (Est. $1.05B) 🔴; -64% YoY
Comments:
🔸 “Demand for our Instinct and EPYC products continued to strengthen, and we expect growth to accelerate further in the fourth quarter as we scale Helios and ‘Venice’ production.”
🔸 “Our fourth-quarter outlook reflects accelerating revenue and earnings growth, driven by strong demand across our Data Center portfolio.”
