

British investor 🇬🇧 32 years old, father of 1 Net worth: £142k (At 30th September) ‘Playing Monopoly without buying investments is a guaranteed way to lose’
England, United Kingdom
Joined June 2022
- Tweets4.7K
- Following949
- Followers2.3K
- Likes8.1K




Pinned Tweet
I lost my dad in 2024.
That changed everything.
I’m George, 32, an accountant from the UK 🇬🇧.
After years of watching friends and family live paycheck to paycheck with no emergency fund, I decided I didn’t want that life for my family — especially now with my 1-year-old son.
My current net worth is £115k. I started investing in 2017, and my goal is simple: grow it every year while still enjoying life — not just grinding.
Money isn’t the end goal. Freedom, time with family, and peace of mind are. I want to set my son up for a stronger future.
Inflation is quietly stealing our wealth, houses are getting further out of reach, and wages aren’t keeping up.
‘Playing Monopoly without investing is a guaranteed way to lose.’
I’m resetting my page to document my real journey to financial freedom — practical investments, useful tech, and lessons learned along the way.
If you’re also trying to build a better future without sacrificing today, drop a 🔥 or comment “Let’s go” below.
Welcome to the journey.

Budget Week.
With the Budget coming this week, here is why a £50,000 salary in 2026 feels nothing like £50,000 used to, and the numbers to explain it.
My salary is £50,483.
Since I started as a trainee accountant on £20k in 2017:
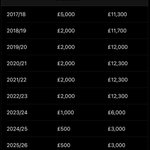
Personal Allowance frozen at £12,570 since 2021.
Dividend allowance cut from £5,000 to £500.
Capital Gains allowance cut from £11,300 to £3,000.
Employee NI was actually cut from 12% to 8% in 2024. While this seems to be positive for the employees, it was a backhanded change. The rise was on the employer side in April 2025, and the threshold where it starts cut from £9,100 to £5,000. On my salary it’s roughly 2% extra my employer has to cough up. That’s money that could have gone into pay rises
Plan 2 Student Loan takes £139pm each month while adding £225pm in interest
Our household bills jumped from £1,241pm in 2020 to £1,695pm in 2026
Our remortgage is jumping from 4.49% (£1,170pm) to 5.52% (£1,321pm) from March 2027
Every pound I earn above £50,270 is already taxed at 51% before it touches VAT, Council Tax, or fuel.
Which allowance do you think gets raided next in the Budget: Pensions, ISAs, or CGT?
The replies opened my eyes to how broken the ‘30 free hours’ scheme is across the UK.
Parents with 2+ funded days still pay £350–£450 a month due to mandatory consumables and meal charges (£10–£25 a day) and term-time stretching (30 hours become 22 across 51 weeks).
Nurseries say council funding doesn’t cover minimum wage or business rates.
My partner works at our son’s nursery, which isn’t at capacity, so blocking us from using 5 of our 20 unused funded hours helps no one.
If your child is in nursery, how many days do they attend and what’s your actual monthly bill after funded hours?

Funded Nursery Hours.
My son is at nursery 2 days a week, for 10 hours.
We get 30 funded hours a week.
These hours can only be used as blocks of 8am-1pm, or 1pm-6pm.
If we wanted him to do 8am-2pm then we would have to pay for the extra hour, even though we have 20 funded hours left.
Why do they make these systems so annoying to use?
BoE rates could increase, but Fixed Rate Mortgage rates decrease.
How?
UK interest rates are based on the swap rate.
The swap rate is essentially the market’s view of the average base rate expected over the fixed period, plus a margin for risk and lender costs.
If rates do not go up as much as market’s expect then we could be in a perverse scenario.
What does this mean?
Base rates go up, but because they don’t go up as much as expected, fixed rates get a little bit cheaper.

Funded Nursery Hours.
My son is at nursery 2 days a week, for 10 hours.
We get 30 funded hours a week.
These hours can only be used as blocks of 8am-1pm, or 1pm-6pm.
If we wanted him to do 8am-2pm then we would have to pay for the extra hour, even though we have 20 funded hours left.
Why do they make these systems so annoying to use?

AI is revolutionising accounting and Data entry/analysis.
Bookkeepers are becoming irrelevant.
Part time bookkeepers are even less efficient.
AI is always available.
If you want to streamline your bookkeeping process and leverage AI, let’s have a chat.
The government needs to scrap the standing charge on utility bills.
When prices are through the roof, people should pay for usage only.
It’s not a huge difference, I think £22 a month to us.
But across millions of homes it makes a huge difference.
What do you think?

🚨 NEW: Andy Burnham says he's looking at removing standing charges from gas bills after the approval of Jackdaw gas field
#PMQs
Modelling the tracker vs fixed rate options.
Four rises = the tracker wins
(Assuming BOE Rate rises in 0.25% steps, spaced evenly over the next two years.)
Total cost over the period:
£28.8k - Tracker
£30.7k - 5-year fix
£31.7k - 2-year fix
It takes roughly eight to nine 0.25% rises over the two years before the tracker’s total payments exceed the 5-year fixed.
It takes roughly ten to eleven 0.25% rises over the next two years before it exceeds the 2-year fixed.
Even then the early lower rates leave a slightly lower balance.
Why are people so interested in fixing rates?
My mortgage is due for remortgage in the next 6 months so we are exploring options now.
Here are the options:
Mortgage: £225,787
Term: 28 years
Fixed Rates
Nationwide - 5.52% 2 year Fixed £1,321pm
Nationwide - 5.23% 5 year Fixed £1,281pm
Trackers
Nationwide - 4.23% (+0.49%) £1,152pm
(2 year tracker)
What would you go for?
We have locked in the 2 year fixed rate at 5.52% for now.
I still suspect we will consider the tracker but atleast we have the peace of mind knowing the maximum repayments will be from April 27 onwards.
My mortgage is due for remortgage in the next 6 months so we are exploring options now.
Here are the options:
Mortgage: £225,787
Term: 28 years
Fixed Rates
Nationwide - 5.52% 2 year Fixed £1,321pm
Nationwide - 5.23% 5 year Fixed £1,281pm
Trackers
Nationwide - 4.23% (+0.49%) £1,152pm
(2 year tracker)
What would you go for?
I bet he’s getting these ideas from Copilot.
Such a terrible idea could only have come from there.
🚨 NEW: John Healey is considering introducing income tax on parents who pass their business down to their children in the Budget
[@Telegraph]
Last week was brutal for the portfolio, with losses of around £5k.
But putting into perspective, still way up over the last 3 months.
Volatility is part of the model for crazy gains.
Wills.
So many people in the UK die without a Will.
Dying without a valid will means you die intestate.
The government then decides who inherits your estate according to fixed rules.
October is free Will month, where you can get a professionally drafted Will for free (for optional Charitable donation)
Everyone with children should have something in place.
You work your whole life, make sure the money you are leaving behind goes where YOU decide.
Don’t rely on the government.
Do you have a Will?
Yesterday was a brutal day in the markets, hope everyone is holding up ok.
Bitcoin Treasuries took the biggest hit
$MSTR down 9.5%
$ASST down 6%
SWC unmoved at 0%
$STRC $97.72
$SATA $96.88
MORE £94.50
None have missed any dividends.
I won’t be concerned until the dividends from the Digital Credit Instruments aren’t being paid.
My mortgage is due for remortgage in the next 6 months so we are exploring options now.
Here are the options:
Mortgage: £225,787
Term: 28 years
Fixed Rates
Nationwide - 5.52% 2 year Fixed £1,321pm
Nationwide - 5.23% 5 year Fixed £1,281pm
Trackers
Nationwide - 4.23% (+0.49%) £1,152pm
(2 year tracker)
What would you go for?
‘Vehicle seized and driver reported.’
They committed fraud.
A slap on the wrist at best.
I bet they don’t get any money back from this either.
The person using it for business probably made loads of money and will keep it all.

The driver of this Motability vehicle was found not to be the intended user and was using it for a business purpose! vehicle seized for no insurance and driver reported. @MotabilityOps


Congratulations to all the tradespeople and their spouses if the personal allowance raises above £12,570.
They will all be getting pay rises.
Do you think the personal allowance should be raised?
What would you raise it to?

Recently I’ve seen US accounts complaining about their ‘Gas’ prices.
Let’s breakdown how cheap US Gas is compared with Petrol in the UK:
• US: $1.15 per litre or £0.87 per litre
• UK: $2.31 per litre or £1.74 per litre
UK petrol is roughly twice as expensive as the US average (about 2.0× in USD terms).
(Using an approximate exchange rate of 1 GBP ≈ 1.324 USD)
Today I had the most unusual interaction with someone.
I was walking past a cash machine holding my son in one arm and some shopping in the other hand.
A person asked if I can help so I stopped, he asked if I could check his balance for him as he was blind.
He then handed me his card and gave me his PIN number.
I put the card in the machine and pressed to see the balance.
£32,000.63
I told him the balance.
He asked if I could print the balance so he could give it to his wife.
Of course I printed it and handed it to him with his bank card.
He then walked away towards Tesco (no cane but he had an empty trolley)
Was he just lucky that he didn’t ask the wrong person?