

🌏A Global Equity Research & Asset Management Firm | Educating Investors through our Intelligent Research
Global
Joined June 2023
- Tweets8.7K
- Following24
- Followers9.1K
- Likes6.8K



Pinned Tweet
Mega Rare Earth Element Thematic Report
We at Global Consilient Research are proud & humbled to announce the release of our 3rd thematic report on REEs
This report will not only give you a macro to micro view, but will also teach you about the different companies involved in India, USA and China in REE space
Here’s a quick snapshot of the report👇🏻

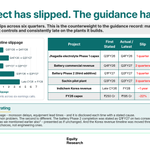
GCR’s view: assess financial delivery and project execution separately from now onwards
For new projects, track commissioning, validation and commercial revenue as distinct milestones
Repeated slippage warrants more conservative timing assumptions
Source: GCR research
1
1
77
Why does this matter if financial guidance holds?
It's because existing operations may sustain near-term performance while new projects contribute later than expected
Meeting financial guidance does not, by itself, validate the commissioning assumptions embedded in longer-term forecasts
1
1
34
Two issues deserve separate treatment
Monsoons, equipment delays and longer validation cycles are operating risks
Presenting a revised deadline as unchanged is a communication concern
Investors should assess both execution reliability and the clarity of management’s updates
1
1
32
The slippage also appears in capital spending
FY26 capex was ₹195 crore against ₹250 crore initially indicated - a 22% shortfall
The explanation was spillover into FY27
Lower capex therefore needs context: deferred spending does not establish better capital efficiency
1
1
36
Indichem Korea’s revenue timeline became harder to underwrite
Our review tracks the expectation from late CY26 towards FY28, with repeated revisions before the timeline was eventually withdrawn
That makes the timing of its revenue contribution materially less certain
1
1
41
Battery Phase 2 raises a different concern
Completion was indicated for Q1FY27 on two consecutive calls, then shifted to Q2FY27 and presented as consistent with earlier communication
The issue extends beyond the delay to how clearly the revised commitment was acknowledged
1
1
47
The Sachin pilot plant timeline shifted from Q3FY26 to Q2FY27
Three quarters of slippage, with equipment lead times cited twice
One delayed milestone can be incidental. Repeated delays warrant more conservative assumptions about when new capacity becomes productive
1
1
57
Battery commercial revenue moved from Q4FY26 to Q2FY27
A two-quarter delay, attributed to extended trials and validation
For investors, the distinction matters: a completed plant still needs product validation and commercial acceptance before it contributes revenue
1
1
65
First off, start with Jhagadia electrolyte Phase 1
The capex timeline shifted from Q3FY26 to Q4FY26 - a one-quarter delay
The stated reason: an extended rainy season
An understandable industrial setback. But completing construction is only the first step towards earning revenue
1
1
120
The short answer for that it because in investing financial guidance can hold while project timelines may keep slipping
Now the question is how much confidence to place in the next commissioning date🧵
1
3
154
Acutaas Chemicals' timing for every project has slipped, yet the stock keeps going up! Why?
We read the last 6 quarter's guidance and their execution, so here's GCR’s review of them👇

A detailed video coming soon!
Till then, join our Telegram channel
t.me/gcralphadesk
110
GCR’s view: Milky Mist deserves analysis as a branded, value-added food business.
The decisive test is whether higher utilisation translates into free cash flow and better returns on capital.
Business quality still needs the right entry valuation.
Source: GCR Global Investment Research
1
83
The IPO helped reset the balance sheet, with ₹497 crore of debt repaid
But debt repayment alone doesn’t establish a self-funding business
After spending 15% – 29% of revenue on capex annually for four years, the test is whether growth can now outpace fresh investment
1
22
The catch: growth has consumed cash
FY26 operating cash flow: ₹302 crore
Capex: ₹470 crore
That left a ₹168 crore gap - the third consecutive year of negative free cash flow
Debt reached ₹1,672 crore against ₹463 crore of equity
Expansion came at a financial cost
1
24
And the distribution network already has scale:
• 394,000+ retail touchpoints
• 4,200+ distributors
• 41,000+ coolers
• Presence across 22 states
E-commerce’s revenue share rose from 7.5% to 13.7% in two years, adding another route to customers beyond its southern base
1
24
And the integration extends beyond the factory
Milky Mist procures directly from 83,000+ farmers and operates its own logistics fleet
Our research cites 18–20% logistics savings from using return journeys to carry loads
In dairy, distribution efficiency matters
1
31
The next growth phase may need less construction
Management says the existing Perundurai facility can support 3–3.5x FY26 revenue before another facility is needed
Most categories operated below 50% utilisation in FY25
Capacity exists. Demand must now catch up
1
32