

Full-service embedded banking: instant funding, payouts, and issuing solutions on a bank-grade, compliant platform.
Alpharetta, GA
Joined March 2009
- Tweets3.8K
- Following826
- Followers3K
- Likes1.2K


Pinned Tweet
The Ingo difference: Making payments and embedded finance work, without the complexity.
Our team of experts believe real innovation isn’t just about technology—it’s about trust.
That’s why our clients don’t just choose us for our platform. They choose us because they trust us to help them succeed.
🟩 We don’t just integrate—we guide. From legal and compliance to bank onboarding and technical setup, we roll up our sleeves and make sure every client is set up for success.
🟩 We don’t just solve problems—we simplify. Every use case is different, and we take on the hardest challenges in payments so our clients don’t have to.
🟩 We don’t just deliver solutions—we build partnerships. Payments are critical to every customer experience, and we take that responsibility seriously—helping some of America's largest brands move money faster, safer, and smarter.
At the end of the day, our job is simple: Take care of the complexity so our clients can focus on growth.
It’s old-school partnership, built for a modern payments ecosystem.
#IngoPayments #EmbeddedFinance #Trust
A family's car is totaled on Tuesday morning. The kids still need to get to school. The parents still need to get to work. Life doesn't pause because of an accident.
Now imagine waiting 10 days for a check to arrive in the mail. This is the reality for too many policyholders. And it's costing insurers more than they realize.
Our new Money Mobility Tracker with PYMNTS Intelligence examined what insurance customers really want and need when disaster strikes. 46% of all insurance claimants rated speed of payment as the single most important factor in their experience. Not security. Not convenience. Not choice.
Speed.
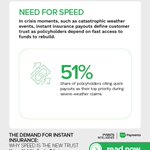
During severe weather events, that number climbs even higher. 51% of policyholders cite quick payouts as their top priority when filing catastrophic claims.
Additionally, when policyholders can decide whether their funds go to a bank account, debit card, credit card, or digital wallet, satisfaction spikes. They feel respected. They feel heard. They feel like partners rather than policy numbers.
The demand is real in this area too, opening up new lines of revenue potential. For example: 23% of consumers receiving insurance disbursements between $500 and $1,000 said they would pay a fee for instant access to their funds. They value speed and control enough to invest in it themselves.
For banks and fintechs partnering with insurance carriers, this represents both a warning and an opportunity. Insurers stuck on legacy disbursement systems are bleeding customer trust with every delayed payment. Those who modernize will own the relationship, and create new durable businesses.
At Ingo, we help carriers embed instant disbursement capabilities directly into their claims workflows. Because when someone's life is disrupted, the last thing they should worry about is when their money will arrive.
Speed is the new trust.


Happy Holidays from the Ingo team 🎄
Every instant payment we power represents someone getting paid faster — a gig worker covering rent, an insurance policyholder rebuilding after a loss, an employee accessing their earned wages when they need them.
None of that happens without our incredible team, partners, and clients who trust us to power their payments.
Wishing everyone a restful holiday season. See you in 2026.
A server finishes her shift at 11 PM. She's worked a double. Her rent is due tomorrow, and she's $47 short.
In most restaurants, she'd wait days for her tips to clear. Maybe longer for her paycheck. But tonight, she opens her phone and watches the money hit her account before she reaches her car.
That 60-second moment changes everything.
Today, the restaurant industry is facing a staffing crisis that shows no signs of abating. According to our latest Money Mobility Tracker with PYMNTS Intelligence, 77% of restaurant operators say worker recruitment and retention pose significant challenges to their businesses. Their solution to recruit and retain talent isn't only higher wages.
It's faster access to the wages already earned.
Restaurants offering instant tip and wage payouts are seeing up to 36% improvement in employee retention. That's not a marginal gain, either. It's the difference between a fully staffed Saturday night and scrambling to cover tables.
For banks and fintechs building solutions for the hospitality sector, this data tells a clear story. The operators who can offer instant payouts will attract and keep talent. Those who can't will keep cycling through costly hiring and training loops.
The Ingo team is helping power operators in this space with instant payout capabilities that help POS platforms, payroll providers, and hospitality fintechs deliver this experience quickly and compliantly. When someone works hard, they shouldn't have to wait to get paid.
The future of restaurant staffing runs through faster money movement.

90% vs. 58%. That's the stickiness gap when instant payouts are free versus fee-based for gig workers and freelancers.
New research from Ingo Payments and PYMNTS Intelligence reveals something important about pricing strategy:
One-size-fits-all doesn't work.
We surveyed 2,237 disbursement recipients and segmented them by how much they rely on payouts for income.
> For people who depend on disbursements as their primary cash flow, removing fees makes instant payments 54% stickier.
> For occasional recipients, fees barely move the needle.
The business case is clear. When you're paying contractors, gig workers, or freelancers who count on that income, subsidizing instant fees drives engagement and loyalty.
Get the full breakdown ↓


57% of people who try instant payments once make it their go-to way to get paid. That's up from 39% in 2020 📈
The shift is real.
Our latest research surveyed over 4,000 consumers to understand what turns first-time instant payment recipients into repeat users. Our findings challenge some assumptions. Speed matters, yes. But reliability and cost matter just as much.
‣ When recipients need funds immediately, stickiness jumps to 68%
‣When instant is free for people who depend on disbursements as primary income, it hits 90%
The takeaway for platforms and payers: instant payments isn't just a feature anymore. It's becoming the expectation.

A 0.81% wage drop doesn't sound like much. Until you realize it just wiped $14 billion from consumer spending.
That's what happened in October when hourly wages for 60 million American workers slipped from $19.55 to $19.39.
Ingo's new Wage to Wallet Index with @PYMNTS Intelligence reveals how small wage changes create massive economic shockwaves:
📊 The October Reality Check:
‣ -$8.2B absorbed by millennials alone
‣- $2.6B in lost Gen Z spending power
‣ Job security sentiment fell 6.7 points to 75.2
‣ Overall Labor Economy™ sentiment rose slightly to 49.2
But, there's an important divide to understand that continues to grow:
→ 33.8% of these workers revolve credit balances
→ Average annual income sits 22%+ below average balance levels
→ Credit scores: 677 vs. 722 for non-Labor Economy™ workers
@PK_DREW, Ingo's CEO, sees these patterns in real-time payment data from our company:
"About 1% wage changes translate to $17 billion in GDP impact. When you're operating real-time payment infrastructure like we do, you see these patterns in transaction volumes before they show up in quarterly reports."
The concerning part for the broader economy is that workers feel less certain about steady hours and pay even as overall sentiment ticks up. That gap between Labor Economy and everyone else (56.2 points) tells the real story.
When 36.5% of America's workforce operates on these margins, their financial strain becomes everyone's economic headwind.
Read the full blog from Drew and download the index:

Thankful for those who move money forward 🍂🧡
This Thanksgiving, we're reflecting on what powers our mission - the incredible people who make money mobility possible.
To our team: Your expertise and dedication transform complex challenges into elegant solutions every single day for our customers. Thank you for making the impossible routine.
To our partners and clients: Your trust drives us forward. Together, we're creating opportunities for millions to access their funds when they need them most.
From all of us at Ingo, wishing you and your families a wonderful Thanksgiving 🦃

"I have family that lives this reality every day. Smart folks, working hard, and usually entrepreneurs. But their income is a patchwork of 1099s, project payments, and gig work that hits their account whenever it feels like it."
Ingo's CEO @PK_DREW gets personal in the company's latest piece with @PYMNTS Intelligence about the 60 million Americans powering our economy.
These workers - earning $25/hour or less - represent 36.5% of the workforce. Yet their average liquid savings is $5,737 versus the typical American's $9,869.
Here's what many fail to understand: The "Labor Economy" drives $1.7 TRILLION in annual consumer spending. For context, that's 15% of everything bought and sold in America.
Our new Wage to Wallet Index reveals critical insights:
→ 55% opt for instant pay, even with fees
→ Instant pay fee = $1.50 vs. NSF fee = $35
→ 1% wage change creates $17 billion GDP impact
→ Transaction spikes signal recessions before quarterly reports
Our team sees these patterns in real-time payment data before they show up anywhere else. The spike started in March and hasn't slowed.
When these 60 million workers thrive, we all do better.
Read Drew's full analysis on what this means for banks, employers, and policymakers ↓

Today, we pause to honor those who served.
At Ingo Money, we recognize that the freedoms enabling American innovation and enterprise exist because of the veterans who defended them. Your service made possible the opportunities we pursue every day.
To every veteran on our team, among our partners, and throughout our community: Thank you for your sacrifice, dedication, and the example you continue to set in civilian life. The commitment you bring from military service strengthens every organization fortunate enough to have you.
Your contribution to our nation's security created the foundation for economic prosperity and advancement of tools like ours to help people.
We're grateful not just today, but every day.

Every broken faucet and cleaned unit means another vendor who needs to get paid. But checks are slow, and ACH can take days.
So @AppFolio integrated Ingo’s push-to-debit rails to help property managers pay vendors instantly.
Now, when a job wraps up, payment doesn’t lag behind. Vendors get their money in seconds instead of days later.
The impact?
• No payments delays
• No phone calls chasing checks
• No disruption to operations
It’s faster. It’s frictionless. And for vendors, that speed builds trust.
Curious how this tech could work for your fintech idea? Schedule time with our team at the link to learn more ↓
ingomoney.com/contact-us/

What if small changes in hourly wages could swing U.S. GDP by $30-40 billion? Our new Wage to Wallet™ Index with @PYMNTS Intelligence and @WorkWhileAI just proved it.
And starting in 2025, we're tracking it monthly in real-time. To summarize what we've got so far ↓
We analyzed America's Labor Economy - 60 million workers who keep commerce moving. The findings are illuminating:
‣ A 1% wage change = $17 billion GDP impact
‣ Recent wage volatility created swings from +$23B to -$43B (annualized)
‣ These workers drive $1.7 trillion in annual spending
‣ Average savings: just $5,737 vs. $9,869 for typical consumers
‣ 55% choose instant pay when offered, even paying fees for it
Why are small percentage changes driving such massive impact? Because there's no buffers or lag time for this economic group. When a warehouse worker misses a shift or their paycheck delays by even a day, spending stops immediately. Bills go unpaid. Purchases get deferred.
The drag ripples outward on the broader economy, instantly.
This is why our team at Ingo believes instant pay is more than a perk to help with customer acquistion. The reality is that instant pay economic infrastructure.
We've spent nearly 25 years perfecting money mobility for hundreds of banks, fintechs, and Fortune 500s because we understand: when earned wages become available cash immediately, it stabilizes the entire ecosystem.
Starting today, this Index delivers monthly intelligence on wage dynamics and their economic ripple effects. Real-time data, not rear-view mirror reports. How can you use this report?
– For business leaders: See consumer demand shifts before they hit your P&L.
– For policymakers: Get early warnings on Main Street economic health.
– For financial institutions: Understand when your customers need support most.
We're done waiting months for economic data that tells us what already happened. The Labor Economy moves too fast for that. These workers turn wages into rent, groceries, and gas within days. Their financial reality is our economic reality.
The path forward is clear: Fair wages. Predictable schedules. Instant access to earned pay.
Now we can measure what matters, when it matters. Monthly. Learn more ↓
Check out the new site, here: pymnts.com/study/wage-to-wal…

Every morning at 4am, long before you see this post, millions of Americans are already at work. They're moving packages in warehouses, preparing deliveries, stocking shelves, and keeping the real economy running.
This is the Labor Economy: 60 million workers who make up 36.5% of U.S. employment. And new research in our report reveals something critical: these workers aren't just essential.
They're economically powerful.
Today, we're proud to announce the launch of the Wage to Wallet™ Index in partnership with @PYMNTS Intelligence and @WorkWhileAI. Here's an important datapoint our team discovered to call out:
💰 A 1% wage change in this segment translates to $17 billion in GDP impact. That's not a typo.
When these workers get paid faster, when their hours are predictable, when their wages keep pace, the entire economy feels it immediately.
Unlike higher earners who might save or invest, Labor Economy workers spend nearly every dollar on essentials. Their money flows directly back into local economies within days, sometimes hours. They have just $5,737 in liquid savings compared to $9,869 for the average consumer. There's no buffer. There's no delay.
There's immediate economic impact.
Our Index also revealed something we've long believed at Ingo: instant wage access is economic infrastructure. 55% of these workers choose instant pay when offered, even paying fees for the privilege. Because getting paid today means avoiding a $35 overdraft fee tomorrow. It means making rent on time. It means keeping the lights on.
As many navigate economic uncertainty, for experts in fintech and banking understanding this segment is as essential as understanding their role in society. The Labor Economy is where monetary policy meets Main Street; where wage growth becomes consumer spending; where financial innovation becomes economic resilience.
Read the full report to understand why the strength of the U.S. economy isn't just reflected in corporate earnings or stock markets, but in the ability of hourly workers to turn wages into spending that sustains growth. Download directly from LinkedIn now, or, grab the report via the link in the next post ↓
