

Nasdaq-100 first. AI infrastructure — compute, power, substrates, packaging. The numbers only. No buy or sell calls.. No buy or sell calls.
Jscc
Joined August 2024
- Tweets16.2K
- Following4.1K
- Followers2.2K
- Likes11.2K





엔비디아 협력사 SPIL이 CPO 광엔진 생산능력을 2027년 중반까지 15배로 늘린다고 합니다. 앰코 인터포저도 2028년 말까지 300% 넘게 증설.
광연결이 AI 데이터센터의 다음 병목이라는 신호로 보이고, 수혜 범위가 생각보다 넓어질 수 있겠네요.
(출처: NVIDIA 뉴스룸 · 투자 권유 아님)
15x optical-engine capacity Nvidia targets for co-packaged optics by mid-2027.
Substrate capacity with Ibiden, Unimicron and Samsung Electro-Mechanics is set for 2.5x over three years, while test capacity is planned to double in 2027.
Nvidia is pre-committing the package, optics and test multipliers so the next AI factory ramp does not stall on capacity.
Nvidia Newsroom
(Public figures compiled. Not a buy or sell recommendation.)

테슬라 3분기 잉여현금흐름 +15.3억 달러. 시장은 49억 달러 유출을 예상했는데 정반대로 나왔어요. 설비투자를 예상보다 덜 쓴 게 컸습니다.
제 생각엔 투자를 늦춘 효과라, 설비투자가 다시 늘어날 때도 현금이 버티는지가 진짜 시험대예요.
33% of HBM revenue went to Samsung in Q2 2026.
That rose from 21% in Q1 while SK hynix fell from 58% to 50%.
UBS sees Samsung passing SK hynix in HBM bit shipments in 2027.
A second source at volume changes who controls allocation timing on AI accelerators.
Source: Counterpoint Research, UBS.
(Public figures compiled. Not a buy or sell recommendation.)

SK하이닉스 3분기 영업이익 컨센서스가 76.964조원이에요. 발표는 10월 28일 오전 9시, HBM4 출하는 기대보다 약하다는 평가도 나옵니다.
개인적으로는 이번엔 숫자 자체보다 HBM4 가이던스가 흐름을 더 좌우할 것 같아요. (투자 권유 아님)
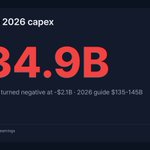
34.9B Meta spent on third-quarter capital expenditures including finance leases.
That outlay rose 80 percent from a year earlier and turned free cash flow negative at 2.1 billion.
Full-year 2026 guidance narrowed to 135-145 billion after roughly 86 billion already spent through September.
The remaining range still implies tens of billions more for servers and data centers in the fourth quarter alone.
Meta
(Public figures compiled. Not a buy or sell recommendation.)

222.5%.
South Korea chip exports rose in the first 20 days of October.
They hit 27.5 billion dollars and took 44.7 percent of the total.
AI memory demand is still driving the residual on the books.
Reuters
(Public figures compiled. Not a buy or sell recommendation.)
🤖 Made with AI

4.73B Tesla spent on Q3 capex, more than double the year-ago total.
Free cash flow stayed positive at 1.53B while revenue held flat at 28.05B and gross margin rose to 19.6 percent.
The spending continues to fund AI compute, Cybercab and Optimus lines even as vehicle volumes stayed soft.
Electrek
(Public figures compiled. Not a buy or sell recommendation.)
🤖 Made with AI

1 trillion.
SpaceX annual revenue in 2028 is no longer impossible, Musk said.
Nearly 15 billion dollars in the latest quarter, up 161 percent year over year.
The figure implies roughly 53-fold growth from 2025 levels in three years.
Business Insider
(Public figures compiled. Not a buy or sell recommendation.)
🤖 Made with AI

30%. more bandwidth claimed on Nvidia NVHBM versus standard HBM4E.
Samsung, SK hynix and Micron are directed onto TSMC 3nm for the base die.
Volume production targets 2027.
The residual that still has to clear is consistent yield across three suppliers.
Seoul Economic Daily
(Public figures compiled. Not a buy or sell recommendation.)
🤖 Made with AI

3 billion just locked into Amkor multi-year packaging agreements with Nvidia.
A new 1.3 billion commitment covers further expansion in South Korea.
The prepayment residual is on the books.
The residual that still has to clear against actual package volume is not.
Business Wire
How do you read the 3 billion once the Korea residual still sits open?
(Public figures compiled. Not a buy or sell recommendation.)
🤖 Made with AI

Four twenty-six still marks the national average today.
A few cents of weekly relief leave the year-over-year gap open inside the remaining inflation residual.
AAA recorded 4.2644 on 21 October 2026.
That sits below the 4.33 level of a week earlier and the 4.48 level of a month earlier, yet remains 1.22 above the 3.05 print from one year ago.
Bureau of Labor Statistics showed gasoline up 34.2 percent for the twelve months ended September 2026 while the all-items index advanced 3.7 percent.
EIA placed the weekly regular average at 4.284 for the week ending 19 October.
The autumn level has eased from its September high, yet the gap versus last year has not closed.
How does that gap read at your own pump?
(Public figures compiled. Not a buy or sell recommendation.)

4.4 billion in net income just printed at SpaceX while the AI line alone cleared 7.56 billion.
The compute segment is now the size that forces the capital line to show up on the same page.
SpaceX (SPCX) on October 20 2026 reported third-quarter revenue of 14.6 billion dollars, up 161 percent from the prior year, with net income of 4.4 billion dollars versus a 1.1 billion dollar loss a year earlier.
The Super Intelligence segment contributed 7.56 billion dollars, an 830 percent rise, and became the largest revenue line.
Nameplate compute reached 1.7 gigawatts and capital expenditure totaled 19.6 billion dollars, the majority directed at AI infrastructure.
The profit is on the books.
The capacity that still has to clear against actual delivery and utilization is not.
How do you read the 4.4 once the 19.6 still sits on the spend side?
(Public figures compiled. Not a buy or sell recommendation.)
🤖 Made with AI

The 10-year just printed 5.13 percent while the Nasdaq-100 closed down only 0.13 percent.
The yield residual is pricing a higher financing cost than the index residual is admitting.
Trading Economics on October 21 2026 put the US 10-year note yield at 5.13 percent, up 0.01 points from the prior session.
MarketScreener and Yahoo Finance showed the Nasdaq-100 finishing the October 20 session at 29,490.28, down 39.06 points or 0.13 percent.
The long-end residual is on the books.
The residual that still has to clear against actual equity multiples and deployment cost is not.
How do you read the 5.13 once the index residual still sits near flat?
(Public figures compiled. Not a buy or sell recommendation.)
🤖 Made with AI

Samsung Electro-Mechanics just locked its first package-substrate LTA for memory into the 2027 calendar.
The contract runs the full year.
A 360.5 billion won deal with an unnamed major global customer covers high-performance package substrates for memory chips from 1 January through 31 December 2027.
The same filing expands the company’s long-term agreements into substrates after prior component contracts, bringing the total disclosed LTAs since May to seven with cumulative value near 4.3 trillion won.
Deliveries have not started.
How do you read the 4.3 trillion once the customer name still sits unnamed?
(Public figures compiled. Not a buy or sell recommendation.)
🤖 Made with AI

Apple dropped Lightning on every market because one region wrote a hard deadline.
The EU’s Common Charger Directive forced a single port onto phones sold inside the bloc, and Apple chose not to split production.
Directive 2022/2380 required USB-C receptacles on phones and similar devices from 28 December 2024.
Apple moved first, putting USB-C on the iPhone 15 in September 2023 and shipping the same design everywhere rather than maintaining a Lightning SKU for non-EU markets.
The European Commission put the annual e-waste from unused chargers at roughly 11,000 tonnes and estimated consumer savings near €250 million a year once devices could share one cable.
After the cutoff, Apple removed the remaining Lightning iPhones (14 series and SE) from EU shelves.
The connector is now uniform.
The wattage and cable ratings still are not.
How do you read the 11,000-tonne number?
(Public figures compiled. Not a buy or sell recommendation.)
🤖 Made with AI

Forty-five billion already sits on the second building before the first 460 MW is energized.
The residual is on the books.
The residual that still has to clear against actual delivery and power-up is not.
Bloomberg on October 19 2026 reported Anthropic and Nscale in talks for a second facility at the Monarch campus in West Virginia worth about 45 billion dollars for 460 megawatts running on Nvidia Vera Rubin chips.
The same coverage noted a prior August agreement of roughly 44.6 billion dollars covering another 460 megawatts at the same site, with systems expected online late 2027 and the first campus phase targeted for the first half of 2028.
Talks remain open and terms can still move.
How do you read the second 45 billion once the first 460 MW still sits on the delivery clock?
(Public figures compiled. Not a buy or sell recommendation.)
🤖 Made with AI

JSCC | Nasdaq retweeted

제가 지난 1년동안 AI 데이터 센터, 반도체, 메모리 관련 리스크라고 짚어드렸던 주제들입니다.
1. 빅테크 capex 증가 속도가 현금 창출 속도 추월, 치킨게임
2. capex가 영업현금흐름의 100%에 근접, FCF 적자 전환
3. 하이퍼스케일러 외부 차입 의존 확대
4. 메모리 가격 급등으로 빅테크 capex 부담 증가
5. 메모리발 인플레이션, 전자기기 수요 위축
6. 메모리 슈퍼사이클 정점론
7. 중국 CXMT 디램 점유율 10% 돌파, 추격 가속
8. 엔비디아 1,000억 달러대 보증, AI 순환금융 논란
9. 오라클/코어위브/네비우스 빚투, 신용 리스크 확대
10. 오라클 FCF 대규모 적자, 신용등급 강등
11. 오라클 Project Jupiter 불가항력 통지, AI 데이터센터 금융 경색
12. SPV/정크본드/사모신용 기반 AI 레버리지 확대
13. AI 인프라 채권 발행 5,000억 달러 육박
14. take-or-pay 계약의 신뢰성 의문
15. 토큰 가격 하락으로 AI 투자금 회수 위협, 네오클라우드부터 타격
16. 코어위브 SPV 금융 구조의 취약성
17. 아마존 데이터센터 리스크를 SPV로 외부 이전
18. 데이터센터 전력 부족, 구글 1,228억 달러 자산 가동 전
지금부터는 아래 주제들을 주목하셔야 합니다.
1. AI 데이터 센터 CAPEX 속도조절로 가느냐, 정말 치킨 게임으로 가느냐
2. 속도조절로 갈 경우, 제일 위험한 기업들은 네오 클라우드. 그 이유는 이들 기업들의 주고객이 빅테크 하이퍼 스케일러들
3. 빅테크는 확실히 자체 칩에 힘을 실을 것임. 거기에 속도 조절까지 하면서 수직계열화에 집중할 경우 엔비디아의 행보는
4. 메모리 본격적인 공급 증가는 2028년이 아닌 반 년 빠른 2027년 하반기부터
5. 그리고 이번엔 메모리 3강이 쉽게 공급 조절, 투자 조절이 쉽지 않을 것. 그 이유는 중국 메모리 견제 때문
AI 시대, AI 수요는 계속될 것입니다. 그럼에도 위에 리스크들에 의해 진폭이 생길 것입니다. 클수도 작을 수도 있습니다. 그리고 기업마다 생태계 레이어마다 영향도가 다를 수 있습니다. 그러나, 알고 있으면 이슈가 불거졌을 때 대응할 수 있습니다.
Capital already names the binding residual before any wafer residual clears.
Order books keep printing while financing terms do not.
Reuters on October 12 2026 reported Broadcom CEO Hock Tan stating that capital will be the biggest constraint as AI development continues, after wafer and memory shortages are overcome, and likened portions of the investment flow to casino gambling.
Through the week ended October 16 the Nasdaq-100 fell roughly five percent, its largest weekly loss in a year, with technology and semiconductor names leading while equal-weight and defensive sectors advanced.
The capital residual is on the books. The residual that still has to clear against actual cost of capital, financing close, and deployment into energized capacity is not.
How do you read the constraint once the weekly residual still sits open?
(Public figures compiled. Not a buy or sell recommendation.)
🤖 Made with AI
