

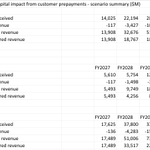
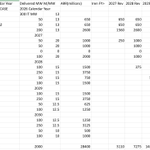
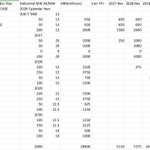


NEW UPDATED $IREN PROJECTIONS, EXPLANATION, AND ANALYSIS
Bear Case 3x, BASE CASE 3OX, BULL CASE 70X
I go fully in depth in the X SPACE BELOW @BitcoinAIGuy
I run through all of the revenue, the margins, the depreciation, the capex, the prepayments, and where I have the price of compute going over the next few years.


Going live with @BitcoinAIGuy to discuss $IREN projections and analysis.
What new catalysts they have coming, when they will turn eps positive, free cash flow positive, and more
xitter.cf/i/spaces/1AxRnZDlrraxl
Live with @StockAnalystPro discussing $SOFI earnings and their future
xitter.cf/i/spaces/1XxygwWBbEnGM


$SOFI Earnings recap in X space with @StockAnalystPro at 6:30
Triple beats on revenue, eps, as well as raising both guidances
On top of that raising 2027 EPS guidance by 10%.
Anthony Noto sees an opportunity for them to grow products by 3-4x by 2030 leading to 3-4x earnings growth.
$SOFI is trading at an 18 forward PE based off of 2027 earnings and we know that $0.90 eps is sandbagged.


Did he just say a 40% CAGR from 2025-2030 now?
3-4x in the amount of products by 2030!!
He said a 3-4x in for earnings for growth
$SOFI has done $0.55 EPS in the Last 12 Months
A 4x would mean $2.20 EPS by EOY 2029
2028 Projections:
2.20*40 Forward PE in 2028 = $88 Share price (4.83x)
2.20*30 Forward PE in 2028 = $66 Share price (3.40x)
2.20*20 Forward PE in 2028 = $44 Share price (1.93x)

$SOFI JUST RAISED GUIDANCE TO $0.90 OF EPS IN 2027
Realistically they probably put up closer to $1.00 EPS in 2026 than $0.90.
They would have beat by .01 eps more in Q1 this year but they had extra SBC
Q2 they would have beat by 0.02 eps more but they had a higher tax rate than expected
Q3 they just beat by 0.02 eps in a rate hike environment
Working off a bigger base of eps the same percentage beat in 2026 could be a 0.03 eps beat in 2027.
What also happens if we get cuts the back half of 2027.
What if they get close to hitting 2028 numbers a year early? How much will they chase up and move price target ratings?


BEST $SOFI EARNINGS I HAVE SEEN RECAP:
Why were you BEARISH on a company at a 18 forward pe growing at 35%+ rev and 40%+ eps?
1. $SOFI Q3 beat
Revenue $1.37B, up 44%, Street $1.25B
EPS $0.18, Street $0.17
Net income $241M, up 73%
Members 17.1M, up 35%
Products 26.7M, up 44%
2. Guidance raised on everything
Revenue $5.04B, up from $4.75B to $4.85B
EBITDA $1.66B, up from $1.6B
Net income $840M, up from $825M
EPS $0.61, up from $0.60
Net income margin guidance up to 20% margins
3. Rate hikes
Original guidance assumed 2 rate cuts
One hike already, positioned for 2 more this year
Guidance still went up
4. Credit got better
Personal loan charge off rate 2.26%, down from 2.62% last quarter and 2.60% last year
Total loan charge off rate 1.62%, down from 1.81% last quarter and 1.90% last year
Personal loan 90 day delinquency 0.42%, in line with last year
5. Technology Platform
Q3 revenue $87M, up 18% excluding Chime leaving
2027 guidance has Technology Platform back to 25% growth
6. No dilution
7. Super intelligence
Management sees super intelligence as a tailwind becuase they have best long term customer value
8. Revenue growth 44%, Rule of 40 score 79, 20th straight quarter
Best metrics of the banks
9. SoFi Plus
273K subscribers
Q4 is re accelerating
Target 1M members by the end of next year, on pace for 1.2 billion+ with 35% growth
10. Book value
Shareholder Equity $11.30B, book value per share $8.71
Price $15.93 is 1.80 book value
Tangible book value $9.7B, $7.48 per share
Price $15.93 is 2.10 tangible book
11. 2027 outlook
Revenue about $6.4B, up 27%
EPS $0.90
These are likely huge sandbags that $SOFI will smash
Congratulations on the great quarter $SOFI and @anthonynoto


$SOFI is saying no more dilution

We are now at the point of financial scale (revenue and profit) where our current capital position, in addition to our organic capital generation, is sufficient to fund our business and our planned growth in 2027.
Our guidance does not require raising additional capital and we are confident we can execute that plan organically given the balance sheet we have built, the capital we will generate organically from the business and the position we are in today.
Joseph Invests retweeted

These are strong results in any environment, but they're even more remarkable when considering how the macro environment in 2026 has unfolded. Nine months into the year, the environment looks different than what we expected.
Our original 2026 guidance assumed two rate cuts. Instead: one rate hike and today we are positioned for two more this year.
The good news is @SoFi is executing as well as we ever have. I now have as much confidence in our ability to drive durable growth in a high rate environment as I do in a low rate environment.

Q3 was a powerful reminder of how far we’ve come in less than a decade. But equally clear of the massive opportunity still in front of us
In 2018, we had 650,000 members and one primary business. Now, 17.1 million @SoFi members use 26.7 million products. We delivered record adjusted net revenue of $1.4B, record adjusted EBITDA of $470M and raised our outlook through 2027 for $6.4 billion in revenue $2.24 billion of adjusted EBITDA, $1.28 billion in Net Income a 20% margin and $0.90 in EPS
Our conviction has never been greater. We’re still early in SoFi’s journey, and our ambitions for the future remain as bold as ever.
Thank you to our members and clients for trusting us to help you get your money right.
investors.sofi.com/news/news…

$SOFI products growth have their fastest yoy growth rate in the last 4 quarters at 44%

