

Latest venture: https://xitter.cf/t.co/cTbM6dKyH7 • Sold DepositAccounts to LendingTree • Former LendingTree Senior Analyst • Interests: banks, saving, investing & walking pup
Orlando, FL
Joined January 2019
- Tweets12.5K
- Following3.8K
- Followers4.5K
- Likes70.4K





Pinned Tweet
Top 5 online savings accounts by APY as of 10/19/2026
& thread on online savings account (OSA) yields and how OSA & money market fund (MMF) yields have changed since the first Fed rate cut (9/18/2024):
Top 5 Status: No change from last week.
Big 5 Status: AMEX APY up 10 bps to 3.20%

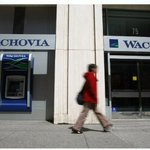
18 years ago, on Oct 22, 2008 during the financial crisis, Wachovia posted a $23.7 billion net quarterly loss, the largest ever reported by a U.S. bank. Much of the loss was the result of write-downs tied to the mortgage lender Golden West Financial which Wachovia had purchased in 2006.
Before the report of this loss, Wells Fargo had already agreed to acquire Wachovia, and this news did not change Wells Fargo’s plans. The acquisition officially completed on December 31, 2008.
#OnThisDay
Sources:
washingtonpost.com/wp-dyn/co…
web.archive.org/web/20201109…
latimes.com/archives/la-xpm-…
federalreserve.gov/newsevent…

Although technically Wachovia didn't fail, it essentially ended on Sep 29th:
xitter.cf/KenTumin/status/210485…

18 years ago, on Sep 29, 2008, marked the end of Wachovia. At the time, Wachovia was the fourth largest bank in the nation with assets of $812 billion. The FDIC announced that Citigroup would acquire the banking operations of Wachovia. In its press release, the FDIC stated that “Wachovia did not fail; rather, it is to be acquired by Citigroup Inc. on an open bank basis with assistance from the FDIC.”
On October 3, 2008, the FDIC announced a change. Wells Fargo would acquire Wachovia instead of Citigroup. The Wells Fargo acquisition did not require FDIC assistance. Citigroup filed suit.
#OnThisDay, #OTD
Sources:
archive.fdic.gov/view/fdic/3…
archive.fdic.gov/view/fdic/3…
federalreserve.gov/newsevent…
2-year non-callable brokered CD rates reached 5.00% today at Fidelity, Vanguard and Schwab.
Higher rates were available on longer terms (5.10% for 3-years, 5.15% for 4-years and 5.20% for 5-years).
A month ago, the highest 5-, 4-, 3- and 2-year rates were 4.85%, 4.80%, 4.70% and 4.60%.
Coincidentally, Capital One, which just reported its earnings yesterday, was one of the banks that had issued these 5% rates for the 2- to 5-year terms.
Brokered CD rates have been following Treasury yields, but they generally lag. So we may soon see declines of brokered CD rates if Treasury yields continue to fall. At yesterday’s close, 5-, 3- and 2-year Treasury yields were estimated to be 4.94%, 4.86% and 4.79% (per Daily Treasury Par Yield Curve Rates).


A wave of new banks is about to shake up a normally staid industry | @AmerBanker
"New regulatory attitudes seem to have coincided with the maturation of many nonbanks to the point where the benefits of controlling a bank outweigh the costs and burdens."

A wave of new banks is about to shake up a normally staid industry americanbanker.com/opinion/a…

Pibank has retaken the top spot as the highest-rate savings account (non-promo rate, directly from an FDIC-insured bank and a low min balance.) Pibank increased its savings account rate by 15 bps to 4.40% APY. This is its second rate increase since the Fed’s Sep 16th rate hike (On Sep 30th, it increased its rate by 15 bps.)
For much of 2025 and 2026, the Pibank savings account was a rate leader with a 4.60% APY. Its peak APY was 5.50% APY when it launched in Aug 2024.
I reviewed Pibank savings and the parent bank, Intercredit Bank, in this February thread:
xitter.cf/KenTumin/status/202134…


Another credit union offers a 5% APY CD.
The online-only credit union Quorum recently introduced two certificates with a 5.00% APY (4- and 5-year terms, $100 min).
Other noteworthy CDs include a 3-year (4.90% APY) and 1-year (4.50% APY).
With assets of $1.4 billion, Quorum is the second largest of the online-only credit unions. According to NCUA records, its last branch closed in 2020. Its corporate headquarters is in Purchase, NY, a suburb of NYC. It originally served Kraft Foods employees. Quorum has long offered nationwide membership via the American Consumer Council.
In addition to competitive online CDs, Quorum has been offering an online high-yield savings account (HighQ Savings) that has competed well with the HYSAs of the major online banks for more than a decade.
Refer to the following thread to learn about other online-only credit unions:
xitter.cf/KenTumin/status/197668…

Online-Only Credit Unions
Online-only banks like Ally and AMEX are well known, but online-only credit unions are relatively new. The NCUA identifies 37 CUs as “Operating Exclusively Online”. Most are small, but there are 4 with assets over $100 million.
🧵 1/7

Capital One increased the rate of its 360 Performance Savings Account today by 10 bps to 3.20% APY. It’s CapOne’s second 10-bp rate hike since the September Fed rate hike.
The savings account reached its peak rate of 4.35% APY in late 2023. The rate started to fall in May 2024, about four months before the first Fed rate cut. It reached its recent bottom of 3.00% APY last June.
Below are the recent savings account APY hikes from major online banks since the Sep 16th Fed rate hike:
AMEX: 3.00% → 3.10% (Sep 23) → 3.20% (Oct 15)
Ally: 3.00% → 3.10% (Sep 25)
CapOne: 3.00% → 3.10% (Sep 25) → 3.20% (Oct 21)
Marcus: 3.40% → 3.50% (Sep 18)
Synchrony: 3.30% → 3.55% (Sep 30)
Note, CapOne released its Q3 earnings yesterday. A few noteworthy deposit stats:
* Total deposits declined 1% to $480.7 billion (QoQ)
* Consumer Banking deposits declined 1% to $431.1 billion (QoQ)
* Average deposits interest rate of 2.78% (up from 2.76% in Q2)

Two years ago, on Oct 21, 2024, Santander launched the digital bank Openbank in the U.S. as a division of Santander Bank, N.A.
Santander is a Spanish multinational financial company with banks in several countries in Europe and the Americas. Under its Openbank brand, Santander operates digital banks in several of these countries. Many of these Openbanks are further along in product offerings than the U.S. Openbank. For example, in September, Santander announced the launch of a cryptocurrency trading service for Openbank customers in Germany.
The U.S. Openbank has been offering a high-yield savings account since its 2024 launch. Last year on Openbank’s one-year anniversary, Santander announced that Openbank had reached $6 billion in deposits. Also last year, Santander announced the opening of a physical location in Miami, FL. According to Santander, this was the third Openbank-branded physical location in the world.
Santander Bank N.A. has recently acquired another digital bank. In August, Santander completed its acquisition of Webster which operates the digital bank BrioDirect. It’s not yet known if BrioDirect will be merged into Openbank. Coincidentally, both BrioDirect and Openbank currently offer only one product, a high-yield savings account. In Santander’s Openbank one-year anniversary press release, it did state that “Openbank will continue to expand its product offerings, including plans to launch Certificates of Deposit (CDs) and introduce new daily-use transaction products.”
#OnThisDay
Sources:
santander.com/en/press-room/…
businesswire.com/news/home/2…
santander.com/en/press-room/…
santander.com/en/press-room/…
santander.com/en/press-room/…

Ken Tumin retweeted

Capital One Will Step Up Marketing to Take On Rivals, CEO Says trib.al/9Yarrcd

Ken Tumin retweeted

Capital One Logs Higher Profit, Revenue as Discover Integration Continues on.wsj.com/4hYizmB

No-penalty CDs have much of the liquidity of savings accounts, but they have the advantage of a rate lock that lasts until the CDs mature. When their rates are higher than savings accounts, they can be a great deal.
The best no-penalty CD deals are now at Climate First Bank. It just increased the rate of its 12-mo Penalty-Free CD by 31 bps to 4.46% APY.
In the last five years, Climate First Bank’s assets have grown from $53 million to $1.94 billion. In the last 18 months, its assets have more than doubled. Climate First is on track to become a major online bank. This June article describes this growth and the history of Climate First Bank and its founder: reasonstobecheerful.world/cl…
Check out @DepositQuestKCJ for the latest survey of top No-Penalty CD rates:
depositquest.substack.com/p/…


Sallie Mae Bank is the latest online bank to increase the rate of its high-yield savings account (HYSA) to 4.00% APY.
It might not be as well known as Ally or Marcus, but I consider it a major online bank. It has assets of over $28B, and it has been offering online HYSA and CDs since 2010. It also has a money market account which offers paper checks. Its deposit rates have a long history of being competitive. Not only is its HYSA competitive today, but also its CDs.
Today’s noteworthy APY increases:
HYSA: 3.85% → 4.00%
12mo CD: 4.40% → 4.50%
36mo CD: 4.45% → 4.60%
60mo CD: 4.50% → 4.75%

The Michigan-based credit union DFCU is expanding into Florida. Its assets have grown by 16% in the last year to $8 billion.
In addition to buying banks, DFCU expanded its product line in 2026 to include a high-yield reward checking account (Cash Back Checking) which offers 7% APY on balances up to $10,000 with typical reward-checking monthly requirements.

DFCU Financial to acquire Florida bank crainsdetroit.com/banking-fi…

My Take on Ally’s Q3 2026 Earnings as an Ally Deposit Customer:
Ally continues to benefit from its status as the “largest, all-digital, direct U.S. bank.” It allows Ally to keep gaining more customers and maintaining deposits even when its rates are subpar as compared to its major competitors (AMEX, Marcus & Synchrony).
The growth in Ally’s brokered deposits and the corresponding decline of retail deposits in Q3 is disappointing. Ally has often been issuing brokered CDs with rates that have been much higher than the rates on its direct online CDs.
Ally’s subpar deposit rates likely contributed to the decline in its retail deposit balance and in the average customer balance.
Deposit related stats from Q3 earnings:
From Q2 to Q3:
* Retail deposit balance fell from $144B to $142B.
* Average customer balance fell from $40k to $39k
* Deposit Mix:
* brokered deposits increased from 6% to 9%
* Retail CD fell from 22% to 21
* MMA/OSA/Checking fell from 72% to 70%
Tip for Ally deposit customers:
There are many online banks offering higher yields than Ally on savings accounts and CDs. Ally customers who don’t want to open another bank account may want to consider this easy and safe way to earn a higher yield on their cash. If you have an Ally Invest account, you have free access to many mutual funds, including the Vanguard Treasury Money Market Fund (VUSXX). It's easy for Ally customers to use VUSXX instead of the Ally savings account for their cash savings. VUSXX’s current compound yield is 3.97% (vs 3.10% APY for Ally’s savings account.) Since VUSXX holds mostly Treasuries, the interest can generally be exempt from state and local income tax. A small downside with this strategy is that it takes one business day to sell VUSXX and transfer it to your Ally checking/savings account where it can be used for payments.

Good overview of Ally’s Q3 earnings by @CHItrader
“Ally Bank:
🔹 Retail deposits $142B | 92% FDIC insured | 86% core deposit funded
🔹 70th straight quarter of deposit customer growth | 3.6M customers”

ALLY FINANCIAL $ALLY Q3'26 EARNINGS HIGHLIGHTS
🟢 Adj. EPS $1.34 vs $1.33 est | +16% YoY from $1.15
🟢 Adj. Total Net Revenue $2.35B vs ~$2.30B est | +9% YoY from $2.16B
🟢 Core Pre-Tax Income $581M | +16% YoY from $502M
🟢 Core ROTCE 13.1% | +80 bps YoY
🔴 Provision $529M | +$114M YoY | CECL build on asset growth
Dealer Financial Services:
🔹 Pre-tax income $417M vs $500M LY
🔹 Automotive Finance pre-tax $337M vs $421M LY
▪️ Consumer auto originations $12.9B | +10% YoY
▪️ Record 4.8M applications | +20% YoY
▪️ Est. retail auto originated yield 9.44% | 44% of volume in the highest credit tier
▪️ Retail auto NCOs 189 bps | +1 bp YoY
🔹 Insurance pre-tax $80M vs $79M LY | written premiums $388M, +1% | 36% ROE
Corporate Finance:
🔹 Pre-tax income $98M vs $95M LY
🔹 HFI portfolio $15.8B | NPLs <1% | 22% ROE
Ally Bank:
🔹 Retail deposits $142B | 92% FDIC insured | 86% core deposit funded
🔹 70th straight quarter of deposit customer growth | 3.6M customers
🔹 Launched "Loyally" fee-free rewards
Other Metrics:
🔹 GAAP EPS $1.30 | +10% YoY from $1.18
🔹 Net financing revenue $1.75B | +$164M YoY
🔹 NIM ex. OID 3.66% | +11 bps YoY, +3 bps QoQ | reported NIM 3.62%
🔹 Adj. other revenue $579M | +$22M YoY | Insurance, SmartAuction, passthrough
🔹 Noninterest expense $1.236B | (4M) YoY
🔹 Corporate and Other pre-tax $52M vs $(82)M LY
Financials:
🔹 Net income to common $401M vs $371M LY
🔹 ROE 12.1% | +20 bps YoY
🔹 CET1 10.2% | +10 bps YoY
🔹 Adj. TBVPS $41.00 | +5% YoY | (3%) QoQ
Capital Return:
🔹 Buybacks $178M
🔹 Q4 dividend $0.35
CEO Commentary:
Michael Rhodes: "Third quarter results provide another clear signal that our focused strategy is delivering results. We are growing our core franchises, improving returns, maintaining risk discipline, and demonstrating our ability to both strengthen capital and return it to shareholders."
He said record application volume lets Ally "be selective while providing the scale to optimize risk-adjusted returns against a fluid backdrop," and called Corporate Finance's 22% ROE "another strong quarter."
$ALLY beat EPS by a penny, but provisions jumped $114M because the loan book keeps growing. That's the price of record auto apps when everyone is still financing $50K pickups. 🏦

The Big 5 online savings account APYs from Sep 18, 2024 to Sep 16, 2026 to Oct 19, 2026:
Ally: 4.20% → 3.00% → 3.10% (-110 bps)
Amex: 4.25% → 3.00% → 3.20% (-105 bps)
CapOne: 4.20% → 3.00% → 3.10% (-110 bps)
Synchrony: 4.50% → 3.30% → 3.55% (-95 bps)
Marcus: 4.40% → 3.40% → 3.50% (-90 bps)
Big 5 Average: 4.31% → 3.14% → 3.29% (-102 bps)
Rate hikes since the Sep 16th Fed rate hike:
+10 bps at Marcus (Sep 18)
+10 bps at AMEX (Sep 23)
+10 bps at Ally (Sep 25)
+10 bps at CapOne (Sep 25)
+25 bps at Synchrony (Sep 30)
+10 bps at AMEX (Oct 15)
Odds that there’ll be at least one rate hike by the end of 2026 are 93.6% (up from 87.7% last week.)
Odds that there’ll be at least 50 bps of rate hikes by the end of 2026 are 15.8% (down from 17.7% last week.)
Current fed funds rate = 3.75%-4.00%
With significant odds of at least one more rate hike, we may see a few online savings accounts with rates above 4.50% as 2027 nears.
Odds are from CME FedWatch.
