

We don’t chase multibaggers. We build conviction before they’re called multibaggers. SEBI registered RA : INH000012953
Kolkata, India
Joined September 2021
- Tweets21.9K
- Following63
- Followers39.8K
- Likes9.6K





Pinned Tweet
Limited Offer🔥🔥🔥🔥
SME MASTER CLUB
Standalone price: Rs. 4,999/-
lnprcapital.akamai.net.in/qu…
Research coverage of SEBI-listed SME platform companies. Promoter conviction signals, filing intelligence, entry-exit framework.
SMALL & MICRO CAP CLUB
Standalone price: Rs. 4,999/-
lnprcapital.akamai.net.in/qu…
Coverage of BSE/NSE-listed small and micro-cap equities. Currently 24 active calls in tracker.
Both subscriptions individual :
Standalone value: Rs. 11,999/-
Limited offer : Rs. 4,999/-
You save: Rs. 7,000/-
Each subscription remains independent. Full year access on both.
Coupon code: LNPR4999
Past calls available on the public timeline
include Titagarh Rail, HBL Engineering, Veefin Solutions, Ceinsys Tech, Avantel, Danish Power, Marsons, and Ashapura Minechem.
Subscribe at lnprcapital.com
LNPR Capital. SEBI Registered Research Analyst.
RA No: INH000012953. Investments in securities market are subject to market risks. Read all related documents carefully before investing.
LNPR Capital retweeted
Limited Offer🔥🔥🔥🔥
SME MASTER CLUB
Standalone price: Rs. 4,999/-
lnprcapital.akamai.net.in/qu…
Research coverage of SEBI-listed SME platform companies. Promoter conviction signals, filing intelligence, entry-exit framework.
SMALL & MICRO CAP CLUB
Standalone price: Rs. 4,999/-
lnprcapital.akamai.net.in/qu…
Coverage of BSE/NSE-listed small and micro-cap equities. Currently 24 active calls in tracker.
Both subscriptions individual :
Standalone value: Rs. 11,999/-
Limited offer : Rs. 4,999/-
You save: Rs. 7,000/-
Each subscription remains independent. Full year access on both.
Coupon code: LNPR4999
Past calls available on the public timeline
include Titagarh Rail, HBL Engineering, Veefin Solutions, Ceinsys Tech, Avantel, Danish Power, Marsons, and Ashapura Minechem.
Subscribe at lnprcapital.com
LNPR Capital. SEBI Registered Research Analyst.
RA No: INH000012953. Investments in securities market are subject to market risks. Read all related documents carefully before investing.
LNPR Capital retweeted
𝗘𝗦𝗗𝗦 𝗦𝗼𝗳𝘁𝘄𝗮𝗿𝗲 𝗦𝗼𝗹𝘂𝘁𝗶𝗼𝗻
A Nashik born cloud company with ₹272 crore of H1 revenue has entered a GPU contract worth USD 1,250 million. First results after its September 2026 listing are out.
𝗧𝗵𝗲 𝗯𝘂𝘀𝗶𝗻𝗲𝘀𝘀
Started in 2005 as a web hosting firm, ESDS now sells three things:
▪ IaaS (47.4% of Q2 revenue): colocation, public, private and hybrid cloud, community clouds and GPU-as-a-Service
▪ Managed Services (31.0%): 24/7 support, backup and disaster recovery, SAP administration, security operations centre
▪ SaaS (21.6%): data centre monitoring suite, vulnerability scanners, web firewalls, VPN, plus government projects in smart metering, e-governance and smart farming (Famrut)
How it earns: pay-per-consumption, per-branch and per-transaction billing. Around 81% of H1 revenue came from existing customers, with revenue retention of 86.7%. Customer mix in H1: Enterprise 46.4%, BFSI 27.6%, Government 26.0%.
𝗧𝗵𝗲 𝗻𝘂𝗺𝗯𝗲𝗿𝘀 (Q2 FY27, consolidated)
▪ Revenue: ₹138.3 crore, up 47.5% YoY
▪ EBITDA: ₹57.8 crore, up 18.3% YoY. Margin 41.8% vs 52.0%
▪ PAT: ₹31.1 crore, up 40.7% YoY
▪ H1 revenue ₹272.0 crore (up 24.6%), H1 PAT ₹60.4 crore (up 26.3%)
▪ Debt to equity: 0.0x post IPO
𝗧𝗵𝗲 𝗚𝗣𝗨 𝗽𝗶𝘃𝗼𝘁
▪ AI infrastructure agreement with an Australian neocloud: USD 1,250 million (around ₹11,831 crore), 8,208 NVIDIA B300 GPUs, 5 years plus a 2-year option. Revenue expected from Q3 FY27
▪ Subsidiary SPOCHUB has received an advance of around ₹1,177 crore from an overseas customer for a new GPUaaS project
▪ ₹576 crore of the ₹720 crore IPO fresh issue is earmarked for cloud and data centre equipment, undeployed as of 30 September
𝗖𝗮𝗽𝗮𝗯𝗶𝗹𝗶𝘁𝗶𝗲𝘀
▪ 5 data centres: Nashik, Navi Mumbai, Mohali, Bengaluru, Noida (three with STPI)
▪ SWARAJ Cloud with patented vertical auto-scaling (US 2015, India 2022)
▪ 115 BFSI institutions across 1,045 branches, 104 government clients, 113 SAP HANA organisations
▪ MeitY empanelled. Mudra Yojana runs on its government cloud
𝗪𝗵𝗮𝘁 𝘄𝗲 𝗮𝗿𝗲 𝘁𝗿𝗮𝗰𝗸𝗶𝗻𝗴
▪ Other expenses rose to ₹50.8 crore from ₹18.0 crore YoY
▪ Managed Services revenue fell around 10% in H1
▪ H1 DSO at 81 days vs 69
▪ The contract value is over 20 times annualised H1 revenue. Execution will decide the outcome
𝗗𝗶𝘀𝗰𝗹𝗮𝗶𝗺𝗲𝗿: LNPR Capital is a SEBI Registered Research Analyst (RA No. INH000012953, BSE Enlistment No. 5843). For educational and informational purposes only. Not a buy, sell or hold recommendation.


LNPR Capital retweeted
How Vijay Kedia Picks Multibagger Stocks 🔥🔥
youtube.com/shorts/RzrsRyaQp…

𝗘𝗦𝗗𝗦 𝗦𝗼𝗳𝘁𝘄𝗮𝗿𝗲 𝗦𝗼𝗹𝘂𝘁𝗶𝗼𝗻
A Nashik born cloud company with ₹272 crore of H1 revenue has entered a GPU contract worth USD 1,250 million. First results after its September 2026 listing are out.
𝗧𝗵𝗲 𝗯𝘂𝘀𝗶𝗻𝗲𝘀𝘀
Started in 2005 as a web hosting firm, ESDS now sells three things:
▪ IaaS (47.4% of Q2 revenue): colocation, public, private and hybrid cloud, community clouds and GPU-as-a-Service
▪ Managed Services (31.0%): 24/7 support, backup and disaster recovery, SAP administration, security operations centre
▪ SaaS (21.6%): data centre monitoring suite, vulnerability scanners, web firewalls, VPN, plus government projects in smart metering, e-governance and smart farming (Famrut)
How it earns: pay-per-consumption, per-branch and per-transaction billing. Around 81% of H1 revenue came from existing customers, with revenue retention of 86.7%. Customer mix in H1: Enterprise 46.4%, BFSI 27.6%, Government 26.0%.
𝗧𝗵𝗲 𝗻𝘂𝗺𝗯𝗲𝗿𝘀 (Q2 FY27, consolidated)
▪ Revenue: ₹138.3 crore, up 47.5% YoY
▪ EBITDA: ₹57.8 crore, up 18.3% YoY. Margin 41.8% vs 52.0%
▪ PAT: ₹31.1 crore, up 40.7% YoY
▪ H1 revenue ₹272.0 crore (up 24.6%), H1 PAT ₹60.4 crore (up 26.3%)
▪ Debt to equity: 0.0x post IPO
𝗧𝗵𝗲 𝗚𝗣𝗨 𝗽𝗶𝘃𝗼𝘁
▪ AI infrastructure agreement with an Australian neocloud: USD 1,250 million (around ₹11,831 crore), 8,208 NVIDIA B300 GPUs, 5 years plus a 2-year option. Revenue expected from Q3 FY27
▪ Subsidiary SPOCHUB has received an advance of around ₹1,177 crore from an overseas customer for a new GPUaaS project
▪ ₹576 crore of the ₹720 crore IPO fresh issue is earmarked for cloud and data centre equipment, undeployed as of 30 September
𝗖𝗮𝗽𝗮𝗯𝗶𝗹𝗶𝘁𝗶𝗲𝘀
▪ 5 data centres: Nashik, Navi Mumbai, Mohali, Bengaluru, Noida (three with STPI)
▪ SWARAJ Cloud with patented vertical auto-scaling (US 2015, India 2022)
▪ 115 BFSI institutions across 1,045 branches, 104 government clients, 113 SAP HANA organisations
▪ MeitY empanelled. Mudra Yojana runs on its government cloud
𝗪𝗵𝗮𝘁 𝘄𝗲 𝗮𝗿𝗲 𝘁𝗿𝗮𝗰𝗸𝗶𝗻𝗴
▪ Other expenses rose to ₹50.8 crore from ₹18.0 crore YoY
▪ Managed Services revenue fell around 10% in H1
▪ H1 DSO at 81 days vs 69
▪ The contract value is over 20 times annualised H1 revenue. Execution will decide the outcome
𝗗𝗶𝘀𝗰𝗹𝗮𝗶𝗺𝗲𝗿: LNPR Capital is a SEBI Registered Research Analyst (RA No. INH000012953, BSE Enlistment No. 5843). For educational and informational purposes only. Not a buy, sell or hold recommendation.
How Vijay Kedia Picks Multibagger Stocks 🔥🔥
youtube.com/shorts/RzrsRyaQp…
LNPR Capital retweeted

Bear markets are where serious small & microcap investors are tested.
A 40–60% correction doesn’t automatically make a stock cheap. But it can create exceptional opportunities in quality businesses.
Focus on balance sheets, cash flows, management integrity & earnings visibility.
The next multibaggers may be hiding in today’s pessimism.
The real edge is not predicting the bottom. It’s identifying businesses that can emerge stronger from the downturn.
Patience creates opportunities. Conviction must come from research.
#LNPR #Investing
LNPR Capital retweeted

Nurture Well Industries H1 FY27 Update
Key highlights:
• H1 FY27 Revenue: ₹320.54 Cr
• H1 EBITDA: ₹31.14 Cr
• EBITDA Margin: 9.71%
• H1 Net Profit: ₹26.65 Cr
• Q2 Revenue: ₹167.73 Cr
What's driving growth?
• Expanded distribution into Maharashtra.
• Madhya Pradesh entry planned for December 2026.
• New biscuit variants: Dark Crunch & Fruit Crunch.
• African exports resumed, with a healthy export order pipeline.
• Expanding brand visibility through digital and celebrity-led campaigns.
With a 3,400 MT/month manufacturing capacity at Neemrana, the company is focusing on product innovation, distribution expansion and export growth.
Key monitorables: Revenue growth, margin sustainability, export execution and distribution-led scalability.
#NurtureWell
LNPR Capital retweeted
5 Indian Defence Stocks with Substantial Order Books
India’s defence manufacturing ecosystem is building strong multi year revenue visibility.
Here are 5 companies worth tracking:
GRSE – ₹45,000+ Cr
Cochin Shipyard – ₹21,900 Cr
Mazagon Dock – ₹16,400–20,500 Cr
Bharat Dynamics – ₹26,000+ Cr
Solar Industries – ₹20,000–21,350 Cr
The investment thesis: Rising defence indigenisation, export opportunities and long term government procurement.
But a large order book alone doesn’t guarantee superior returns. Execution, margins, cash flows and valuations remain critical.
For research purposes only.
🤖 Made with AI

5 Indian Defence Stocks with Substantial Order Books
India’s defence manufacturing ecosystem is building strong multi year revenue visibility.
Here are 5 companies worth tracking:
GRSE – ₹45,000+ Cr
Cochin Shipyard – ₹21,900 Cr
Mazagon Dock – ₹16,400–20,500 Cr
Bharat Dynamics – ₹26,000+ Cr
Solar Industries – ₹20,000–21,350 Cr
The investment thesis: Rising defence indigenisation, export opportunities and long term government procurement.
But a large order book alone doesn’t guarantee superior returns. Execution, margins, cash flows and valuations remain critical.
For research purposes only.
🤖 Made with AI
LNPR Capital retweeted
Guys kindly subscribe our YouTube channel 👇🏼

Rakesh Jhunjhunwala on the Power of Dreams 🔥🔥
youtube.com/shorts/2ZGiLlU3u…

Guys kindly subscribe our YouTube channel 👇🏼
Rakesh Jhunjhunwala on the Power of Dreams 🔥🔥
youtube.com/shorts/2ZGiLlU3u…
LNPR Capital retweeted
Rakesh Jhunjhunwala on the Power of Dreams 🔥🔥
youtube.com/shorts/2ZGiLlU3u…
Rakesh Jhunjhunwala on the Power of Dreams 🔥🔥
youtube.com/shorts/2ZGiLlU3u…
LNPR Capital retweeted
𝗖𝗿𝗲𝗱𝗲𝗻𝘁 𝗖𝗼𝗻𝗻𝗲𝗰𝘁 𝗡 𝗖𝗮𝗿𝗲
𝗧𝗵𝗲 𝗯𝘂𝘀𝗶𝗻𝗲𝘀𝘀
Credent (C3) handles home sample collection, intracity and intercity sample movement, cold chain and corporate health check ups for diagnostics chains, hospitals and healthcare enterprises.
The network, as per the company:
• 14+ years of operations
• 2,500+ laboratories associated
• 6,000+ field force, including 2,200+ phlebotomists
• 19,000+ pincodes covered
• 280+ domestic customers
• 35+ air routes with delivery within 10 to 12 hours
Why this is not ordinary logistics: time sensitivity, temperature integrity, chain of custody and compliance. A delayed parcel is an inconvenience. A delayed sample is a failed test.
𝗧𝗵𝗲 𝗻𝘂𝗺𝗯𝗲𝗿𝘀 (H1 FY27 vs H1 FY26, consolidated)
• Revenue: ₹138.1 crore vs ₹90.0 crore, up 53%
• EBITDA: ₹18.2 crore vs ₹11.9 crore, up 53%
• EBITDA margin: steady at around 13%
• PBT: ₹15.0 crore vs ₹9.8 crore, up 53%
• PAT: ₹14.7 crore vs ₹7.5 crore, up 95%
One nuance. PAT includes a one-time tax credit of ₹1.78 crore. The 53% PBT growth is the cleaner read of underlying performance.
FY26 ROE stood at 42% and ROCE at 50%.
𝗕𝗮𝗹𝗮𝗻𝗰𝗲 𝘀𝗵𝗲𝗲𝘁
• Cash and bank: ₹74.2 crore vs ₹2.2 crore
• Debt to equity: 0.2x vs 0.5x
𝗠𝗮𝗻𝗮𝗴𝗲𝗺𝗲𝗻𝘁 𝗴𝘂𝗶𝗱𝗮𝗻𝗰𝗲
Around 45% revenue CAGR targeted through FY30, with revenue, EBITDA and PAT projected at around 5x of FY26 levels.
The Alltrak Technologies acquisition brings route optimisation and tracking IP in house.
𝗪𝗵𝗮𝘁 𝘁𝗼 𝘁𝗿𝗮𝗰𝗸
• Operating cash flow was negative: ₹6.6 crore outflow in FY26 and ₹3.9 crore in H1 FY27, despite reported profits
• Trade receivables rose to ₹78.8 crore from ₹58.8 crore in March 2026 and ₹17.9 crore in March 2025
• Employee cost is around 39% of revenue. This is a people heavy model
• FY26 revenue of ₹214.2 crore vs ₹81.8 crore in FY25 is not like for like. FY25 is standalone, FY26 onwards is consolidated after acquisitions
Growth is visible. Profit converting into cash is the next thing to prove.
Disclaimer: LNPR Capital is a SEBI Registered Research Analyst (RA No. INH000012953, BSE Enlistment No. 5843). This post is for educational and informational purposes only and is not investment advice or a recommendation to buy or sell.


𝗖𝗿𝗲𝗱𝗲𝗻𝘁 𝗖𝗼𝗻𝗻𝗲𝗰𝘁 𝗡 𝗖𝗮𝗿𝗲
𝗧𝗵𝗲 𝗯𝘂𝘀𝗶𝗻𝗲𝘀𝘀
Credent (C3) handles home sample collection, intracity and intercity sample movement, cold chain and corporate health check ups for diagnostics chains, hospitals and healthcare enterprises.
The network, as per the company:
• 14+ years of operations
• 2,500+ laboratories associated
• 6,000+ field force, including 2,200+ phlebotomists
• 19,000+ pincodes covered
• 280+ domestic customers
• 35+ air routes with delivery within 10 to 12 hours
Why this is not ordinary logistics: time sensitivity, temperature integrity, chain of custody and compliance. A delayed parcel is an inconvenience. A delayed sample is a failed test.
𝗧𝗵𝗲 𝗻𝘂𝗺𝗯𝗲𝗿𝘀 (H1 FY27 vs H1 FY26, consolidated)
• Revenue: ₹138.1 crore vs ₹90.0 crore, up 53%
• EBITDA: ₹18.2 crore vs ₹11.9 crore, up 53%
• EBITDA margin: steady at around 13%
• PBT: ₹15.0 crore vs ₹9.8 crore, up 53%
• PAT: ₹14.7 crore vs ₹7.5 crore, up 95%
One nuance. PAT includes a one-time tax credit of ₹1.78 crore. The 53% PBT growth is the cleaner read of underlying performance.
FY26 ROE stood at 42% and ROCE at 50%.
𝗕𝗮𝗹𝗮𝗻𝗰𝗲 𝘀𝗵𝗲𝗲𝘁
• Cash and bank: ₹74.2 crore vs ₹2.2 crore
• Debt to equity: 0.2x vs 0.5x
𝗠𝗮𝗻𝗮𝗴𝗲𝗺𝗲𝗻𝘁 𝗴𝘂𝗶𝗱𝗮𝗻𝗰𝗲
Around 45% revenue CAGR targeted through FY30, with revenue, EBITDA and PAT projected at around 5x of FY26 levels.
The Alltrak Technologies acquisition brings route optimisation and tracking IP in house.
𝗪𝗵𝗮𝘁 𝘁𝗼 𝘁𝗿𝗮𝗰𝗸
• Operating cash flow was negative: ₹6.6 crore outflow in FY26 and ₹3.9 crore in H1 FY27, despite reported profits
• Trade receivables rose to ₹78.8 crore from ₹58.8 crore in March 2026 and ₹17.9 crore in March 2025
• Employee cost is around 39% of revenue. This is a people heavy model
• FY26 revenue of ₹214.2 crore vs ₹81.8 crore in FY25 is not like for like. FY25 is standalone, FY26 onwards is consolidated after acquisitions
Growth is visible. Profit converting into cash is the next thing to prove.
Disclaimer: LNPR Capital is a SEBI Registered Research Analyst (RA No. INH000012953, BSE Enlistment No. 5843). This post is for educational and informational purposes only and is not investment advice or a recommendation to buy or sell.
LNPR Capital retweeted
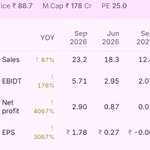
Market Cap: ₹178 Cr | P/E: 25x
Q2 FY27 Results (YoY):
Revenue: ₹23.2 Cr, up 87%
EBITDA: ₹5.71 Cr, up 176%
Net Profit: ₹2.90 Cr vs ₹0.01 Cr
EBITDA Margin: 16.7% → 24.6%
Revenue growing fast, but profitability is growing even faster.
The real question: Is this the beginning of a sustained earnings transformation?
One quarter isn’t enough to establish conviction, but this microcap deserves a closer look.
Can you guess the stock?
#Microcap #EarningsGrowth #LNPRCapital

Market Cap: ₹178 Cr | P/E: 25x
Q2 FY27 Results (YoY):
Revenue: ₹23.2 Cr, up 87%
EBITDA: ₹5.71 Cr, up 176%
Net Profit: ₹2.90 Cr vs ₹0.01 Cr
EBITDA Margin: 16.7% → 24.6%
Revenue growing fast, but profitability is growing even faster.
The real question: Is this the beginning of a sustained earnings transformation?
One quarter isn’t enough to establish conviction, but this microcap deserves a closer look.
Can you guess the stock?
#Microcap #EarningsGrowth #LNPRCapital
LNPR Capital retweeted
Don’t chase the next 10X multibagger.
Find businesses with the potential to grow 10X.. invest at sensible valuations & let earnings drive your returns.
#LNPR
LNPR Capital retweeted
Ramesh Damani: The Secret to Making Big Money in Stocks 🔥🔥
youtube.com/shorts/sjgN5Jgu4…
