

Stockbroker for 40+ years. Founder of @Marcus_Today. Telling it like it is since 1998.
Australia
Joined May 2017
- Tweets938
- Following100
- Followers1.6K
- Likes344



Marcus Padley retweeted

The market goes up slow and comes down fast, and there's no rush to buy when the herd turns.
@MarcusPadley on what a 3% fall in the US market really tells you.
marcustoday.com.au/2026/11/t…

A raid at $9.50 is not a bid. It does set a floor for one.
marcustoday.com.au/2026/11/a…

It's not every day you see a big good day followed by a big bad day. Last night's move is right up there with some of the biggest market moments of the last few years.

Marcus Padley retweeted
Why do miners tend to hedge at the wrong time?
@henryj007 puts the question to Sean Russo of Noah's Rule, recorded live at @IMARC_Mining 2026.
buzzsprout.com/1852332/episo…

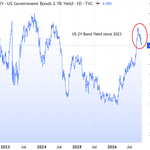
We've decided to let the overnight reaction mature before believing this pivot point. Quite often, after a big good day, there is a reversal the next day, before the trends develop. At first sight this is shaping up as a significant pivot point if bond yields top out, inflation fears peak and the US dollar drops.
If these themes can hold for more than a day, we will be looking to buy something. There is a good chance this is a one-day wonder.

Income investors should be pretty comfortable with the boringly good results and unsurprising "expensive" research opinions.
We're all wondering what UBS is doing with a target price 20% above the current $WBC.AX share price. Attracting attention or ahead of the pack on cost-cutting potential for banks (thanks to AI)?

Marcus Padley retweeted
Anthropic's amended S-1 is out, and the numbers are tougher than they looked a week ago.
@MarcusPadley walks through what changed and why he now calls it overpriced.
marcustoday.com.au/2026/11/t…

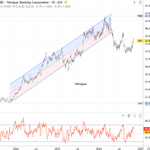
$WBC.AX has reported a full-year statutory profit of $6.8bn, down 1%. Cash profit excluding notable items was $6.99bn, flat on last year and very close to what the market expected. The final dividend is 77c fully franked.
Impairment charges were up 104% from $424m to $864m. At least the total impairment charge was less than the consensus expected. Stressed exposures were down 11bp to 1.17% of committed exposures, so the higher charge is about caution more than actual losses. Net interest margin was down 7bp to 1.87% (small miss).
Broker target prices are firmly below the current share price on almost all the banks, including Westpac. The average target price is 7.8% below the current share price before the results today. UBS stands out from the rest of the brokers with a target price 22% above the current share price. They have a $45 target price. Most broker target prices are grouped around $30.
Let's see what they are saying tomorrow.

The graph comparing Q2 to Q3 shows the trend is getting worse. For now, the market is treating Hyperscaler CapEx levels as unsustainable.

Big Tech earning a fortune but spending an even greater fortune.
For every dollar of operating profit Amazon made in the quarter it put $2.75 into data centres. Meta put in $1.48, Alphabet $1.27 and Microsoft $0.86.
Share prices aren't going to rise until that spending slows.

Priced for miracles. Anthropic's growth has slowed to about 45% a quarter, and there is US$245bn of compute payments behind it.
marcustoday.com.au/2026/10/c…

Marcus Padley retweeted
Anthropic IPO talk has dropped about US$500bn in a week.
@MarcusPadley explains why that hasn't made it cheap.
marcustoday.com.au/2026/10/c…
Mag7 is currently trading on a PE of 24x vs the 10-year average of 29x and 33x last year. Amazon is under 20x for the first time since 2008.
Valuations have been compressed due to AI spending yet earnings expectations remain sky-high. Mag7 profits are expected to rise 34% YoY, and growth forecasts for next year have risen from 19% to 27% in less than two months.
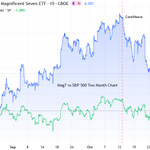
It explains why the MAGS ETF had been on such a tear vs the rest of the market until CoreWeave kicked off the latest round of debt concerns.
Last quarter, Microsoft and Amazon were rewarded for their capital discipline while Alphabet was punished. Let's see what we get this time.

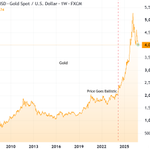
Gold hasn't been a safe-haven trade since its huge bull run kicked off in 2024. Stable store of value and a hedge against inflation turned into a speculative, crowded trade.

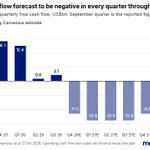
$META free cash flow was +$2.12bn against an expected -$9.22bn, after capex came in at $33.94bn against $40.95bn. Don't read that as fiscal discipline.
Meta raised the bottom of its full-year capex range to $135–145bn and has spent only ~$86bn through nine months.
That leaves $49–59bn to spend in the December quarter alone, against September quarter operating cash flow of $32.79bn. The negative free cash flow everyone was worried about arrives in three months rather than now.

Selling overdone or justified?
marcustoday.com.au/2026/10/n…

Marcus Padley retweeted
$NXT.AX has lost ~$2.6bn because one power line can't be finished.
Oliver Matthew explains why the stock still isn't as cheap as it looks.
marcustoday.com.au/2026/10/n…
On @ausbiztv this morning.
ausbiz.com.au/media/the-open…

Signs of the Big Tech peak. The Anthropic IPO looks like being repriced from $2 trillion to $1.5 trillion. $CRWV debt is at 78 cents in the dollar only 4 months after being issued, with the yield almost doubling to over 15%.
$ORCL CDS prices are at a record 343bps and $META at a record 114.8bps. The Firmus Technologies IPO has been pulled. The Korean market is down 40%.
5% risk-free in the bank is looking good. For the moment.
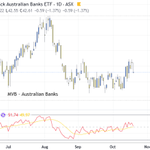
Searching outside the Big Tech AI space for opportunities. The only area of interest is the Australian bank sector. NAB's 2500 job cuts and the CBA's AGM comment that they cannot guarantee no loss of jobs because of AI – there is just a chance the banks turn out to be one of the biggest beneficiaries of AI adoption.
Too early? Results are around the corner. And the dividends. Hmmm.
