

Nothing you can compare to your neighbourhood nutjob https://xitter.cf/t.co/YBAn6pyphH
Belgium
Joined December 2020
- Tweets2K
- Following1.4K
- Followers920
- Likes12K




Long $PURR


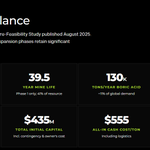
80% payout ratio
7x 2028 ev/ebitda. Low capex intensity
$AMC.L


$AMC.L unfortunate IPO timing. I have it here at 8.7x ebitda which is rather cheap given no mcx high tam busines. Growth cagr of rev has 20%-25% and will probably grow at this rate going forward. FX risk big, i dont see multiple going double digits
NS Investments retweeted

Honestly, this looks very suspicious. @elonmusk is trying to crush his competition outside the boxing ring. $SPCX is competing for the same AI-compute business, yet he keeps posting about how doomed $CRWV, $NBIS and the other neoclouds are.
Then @chamath and the rest of the cheerleading squad echo the same message. That’s Soros-style reflexivity: the narrative hits the stocks, funding gets harder, and the prediction starts creating itself.

Pretty much.
As of the past few weeks, debt markets have almost entirely shut off access to money for any company that doesn’t have substantial revenue independent of AI data centers.
SpaceX closed $40B of debt for GPUs, but we’re investment grade and have Starlink & launch revenue.
That means the 200+ neoclouds are going to see guppy-level death and consolidation. Some will make it through, but not many.
Flowtraders $FLOW.AS small premium to NTBV/ share - €21/sh
A good 'long vol' name. Resurrection of crypto is a tailwind on forward earnings 8x ttm earnings. Structural beneficiary of ETF-ization. Ive figured EU names are more backwardslooking. R/R deff not bad here


$BAK proposal and counter from creditors
Looks like creditors will get what they want
Rights offering will be interesting


Adj for SBC 300M-ish runrate SBC more like 5.2x on 2028 Ebitda for an APAC superapp where it dominates mobility, and deliveries. Underbanked gives tailwind for fin serv. Growing network effects. Stepping up buybacks.
Growing economies, young populations. Reminds me of $KSPI
$GRAB


$FEAM
$24M just covered by liquidity (20M +10M bridge, due june 2027). But assume corp overhead not incl. Given working capital financing, do not expect material dilution
CEO & chair came in at 3.5/3.6 in open market.
40M '28 runrate increases borrowing capacity Fort Cady


$TGA.L fighting for its september peak. Expect to take it this afternoon when the US wakes up.
As this is a momentum favourite/ gambling vehicle, it could rally (even more) when it breaks out
Coal/ gas spread wide and 🇮🇳 is running out of coal when shoulder season ends.
$AMC.L unfortunate IPO timing. I have it here at 8.7x ebitda which is rather cheap given no mcx high tam busines. Growth cagr of rev has 20%-25% and will probably grow at this rate going forward. FX risk big, i dont see multiple going double digits
Reminds me of Dereck Pilecki buying $hood in 2023 when it was trading at book. Unfortunately no meme stock + market has to really bottom in retail names for brokerages to work imho. No reason to believe $TIGR and $FUTU cant go lower nt, but they should do well if nrmlz from her
$TIGR at 15% discount to book is crazy cheap. Normalization ex china bizz should lift the stock. Wealthier client profile than other retail brokerages and increasingly institutionally focused.
Bagholding this thing hard. Probably doesnt work in a retail sell off
$Grab Q2 annualized ev ebitda ex financial services is 10.4 (threw it out here cause unprofitable but it is inflecting with loan book growing 100% organically w npl stable. BE of segment expected in H2)
CEO bought $30M of stock at current level in september