





200+ neoclouds? I didn't even know there were 200…
What I am confident in: those able to secure hyperscaler contracts like $MSFT and investment-grade debt on favourable terms will be absolutely fine...
$IREN and $NBIS pass both checks.

Pretty much.
As of the past few weeks, debt markets have almost entirely shut off access to money for any company that doesn’t have substantial revenue independent of AI data centers.
SpaceX closed $40B of debt for GPUs, but we’re investment grade and have Starlink & launch revenue.
That means the 200+ neoclouds are going to see guppy-level death and consolidation. Some will make it through, but not many.


Oli retweeted
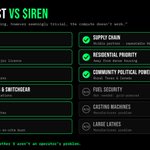
Stranded compute = GPUs with no power to run them.
The winners have a repeatable build-out design and secured grid connections.
Am I the only one who sees this as bullish for $IREN?

Oli retweeted
Chamath: "Neoclouds are disorganized and poorly capitalized. Some are definitely better than others however."
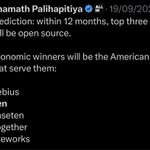
A month ago, he named $IREN and $NBIS among the economic winners of the next 12 months.
I wonder which neoclouds he is referring to?


As someone with a portfolio of energized land assets here is what I am seeing:
1. Neoclouds are disorganized and poorly capitalized. Some are definitely better than others however.
2. Hyperscalers are intractable, bureaucratic organizations that take 3 months to do an NDA and want 18mo escrow periods. We built our portfolio by competing against these terms because of our speed and simplicity. The more future assets orgs like ours win, the bigger the problem for the hyperscalers downstream (see 3).
3. There are delays in the existing pipeline that will catch people off guard in 2027. Hyperacalers will (obviously) react by focusing on their own internal compute needs over any third party. If the third party is a model company, they will tell them to go through their model router where they will also take a non-trivial vig. Them telling Ant they have no compute for them (rumored in Ant’s S-1) if true is a huge tell that this is already happening.
All of this is to say that it does look like there will be a lot of partially stranded compute and compute sitting in inventory in 2027 than is currently forecasted. This is bought and paid for but effectively underearning (below total cost of capital) or collecting dust. We see this as true for everyone - model companies, hyperscalers, neoclouds except ONE (you can guess which one).
This dislocation will benefit two kinds of orgs: the non-bureaucratic big scalers who can build industrial scale quickly and the nimble, well capitalized players feeding them.
2027 will be a turbulent year because it will clear out a bunch of wrong/bad bets. It will also be a consolidation year for a few.
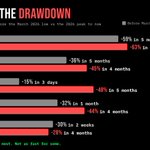
What this doesn't show: the capacity $IREN has secured since 2021.
Revenue run-rate: ~$1B today, ~$4B within months (@danroberts0101 on CNBC).
Hey @grok, how much GW has IREN secured since 2021, how much of it is contracted, and what would the uncontracted capacity be worth if monetised as AI cloud at current market pricing?

