

Searching for uncommon returns in small-caps and mid-caps.
Research →
Joined August 2022
- Tweets4.2K
- Following488
- Followers4.4K
- Likes1.3K






Great results yesterday from Hardide Plc.
Revenue up 124% to £13.5m and EBITDA up from £1m to £5.8m, a 43% margin.
The company uses a process called chemical vapour deposition (CVD) to apply extremely hard tungsten carbide coatings to metal components.
Much of the growth is being driven by a North American energy customer but management is now highlighting potential new customers in the Middle East and in Semiconductors. That could be material.
Main risk is customer concentration and whether the recent strength in demand and margins is sustainable. Hard to assess the technical aspect but there is a lot to like here.
$HDD.L


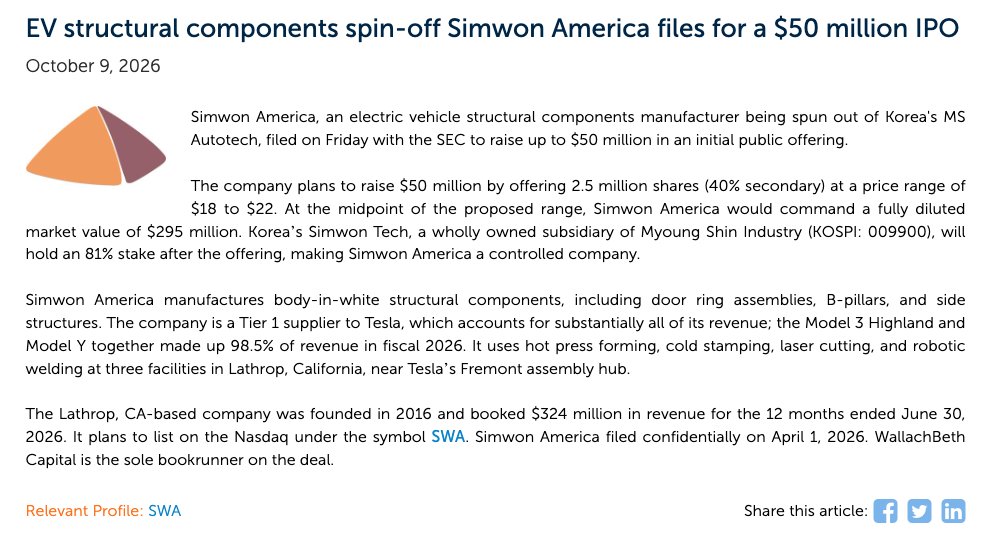
New IPO Simwon America plans to list on Nasdaq.
Extraordinary revenue concentration. Tesla Model 3 Highland and Model Y made up 98.5% of revenue in fiscal 2026

Quadient $QDT is a French communications company made up of 3 parts; a shrinking but profitable mail equipment business, a growing software portfolio and a parcel-locker business.
At first glance, Quadient doesn’t look attractive. Mail is in structural decline, group revenue fell 5% last year and net debt has increased to €683 million euros against a market cap of just €500 million.
However, Quadient’s reported debt is overstated by leases and a customer financing business that should actually unlock cash flow as the mail business shrinks.
And last month, Quadient announced plans to exit its parcel locker business entirely, including an agreed €65 million sale of its UK operation. These disposals should release more cash and simplify the business.
Meanwhile, Quadient’s software business is growing steadily, hitting $264 million ARR in the first half. So if you value the software business at 2x ARR, that already covers the company’s current market cap.
A very conservative SOTP puts upside around 40%. If management hit their targets the upside is much larger at least 100%+


Wise has announced that Barak Eilam, former CEO of NICE Ltd., will become its new chair in April 2027.
Eilam spent 25 years at NICE during which he helped transform the company into a global enterprise software leader, roughly tripling revenue and building a substantial cloud business.
But there's another interesting angle. NICE also owns NICE Actimize, a major provider of software that helps banks detect fraud, money laundering and other financial crimes.
This is relevant to Wise, which has run into regulatory problems over weaknesses in its anti-money-laundering controls and the rejection of its US banking charter application.
It's possible that Eilam's experience in this area played a part in his appointment. Either way, Wise is getting someone with an excellent track record and a strong understanding of the compliance challenges facing financial institutions. I like it 👍 $WISE $WSE


Does all of this work and then buys Uber, Amazon and Visa. Yeah ok

Bill Ackman on the investment process at Pershing Square
"We typically have two members of the team do a deep dive on the company. They will start with the SEC filings, 10Ks, 10Qs, and conference call transcripts. Then, we will assemble the key issues we are trying to understand.
We spend a fair amount of time on expert networks. We will talk to former employees, other industry experts, and competitors to get to the underlying issues.
Then we build a model of the business. We get an assessment of how this pencils and what kind of return does it generate at the price we can buy it for today.
Then that team will put together a deck and present it to the group. That two-person team is usually not Ryan [Pershing Chief Investment Officer] or myself. We do our independent assessment to be dangerous enough to ask the right questions. Then we have the balance of the team, another five people, who have not done work on the name.
That group comes together to discuss an investment. Out of that meeting, we can make a decision to invest in the company. Or maybe we can say there are still some open issues. Then they will go back and do the work, and come back to the team"

IG Group looks interesting after Friday’s 23% share-price collapse.
Headline numbers were weak, with revenue down sharply and guidance cut, but underneath that the customer franchise still looks healthy: active customers rose 17%, first trades increased 25% and customer income grew 8%.
The real issue was that IG only converted around 70% of customer income into revenue, versus roughly 80% prior, likely because of weaker hedging/trading outcomes under its new risk-management approach.
If that retention rate normalises, the selloff could prove excessive; if 70% is the new normal, earnings need to be reset lower.
Plus500 may be the cleaner opportunity because its shares were dragged down by IG’s warning even though management immediately reiterated full-year expectations and said its risk-management framework continues to perform well.
The key question is whether IG’s problem is company-specific or a warning for the whole CFD sector.
$IGG.L $PLUS.L

Innoscripta fell 56% yesterday after German authorities searched group offices as part of a criminal tax investigation into R&D tax-credit applications. And shares continue to slide this morning.
The concern is material because helping clients access these incentives is central to the business model, although the company says the issue may relate to misconduct by individual employees on certain engagements. No major statement has been made as the company investigates the case.
What makes this more interesting is that insider ownership in Innoscripta is extremely high: CEO Michael Hohenester owns roughly 55% while CFO Alexander Meyer owns around 13%; Hohenester was also buying meaningful amounts of stock only weeks before the investigation became public.
Liquidity is another important factor: only around 16% of the company is in free float and normal daily trading volume is very low, so the selloff was likely amplified by the limited supply of tradable shares.
The key question is whether this proves to be an isolated or immaterial compliance issue or something that damages the economics and credibility of Innoscripta’s core business. $1INN

For all those saying AI will take jobs, better to get a job as a plumber, well I just replaced my bathroom taps with chatgpt
Interparfums has signed an exclusive worldwide license with PUMA to develop and distribute PUMA-branded fragrances.
The agreement runs through 31 December 2037, with the first new signature lifestyle fragrance scheduled for 2027.
This is effectively a relaunch of PUMA's fragrance business. Previous PUMA fragrances were handled by companies including L'Oréal and P&G, but no new PUMA scent has been recorded since 2019.
Financial terms and forecasts have not been disclosed but this could be an interesting development.
We closed our recommendation of IPAR earlier this year but I’d be open to another entry if the stock continues to dip. $IPAR

Billington Holdings offers a relatively overlooked way to participate in the UK data-centre buildout without paying a technology multiple.
Yesterday’s H1 results show a 29% increase in sales to £54 million and a 39% increase in EBITDA to £3.7 million.
And 12 days ago Billington announced £42m of new data-centre contracts, the first phase of a substantially larger development.
That's an enormous contract award relative to a ~£58 million market cap and a business that generated only £96m revenue last year. NP
$BILN.L

New idea just dropped.
• 25% revenue growth (5% organic)
• 22% founder-led
• 30% adjusted margins
11x FCF is simply too cheap for this business. 👇
overlookedalpha.com/p/a-30-m…

As shown in Michael Mauboussin’s recent paper, market estimates for Alphabet have free cash flow hitting $305 billion in 2031.
That’s roughly a 4x increase from 2025.
How likely do you think that is? $GOOG


UK small cap Diaceutics Plc is starting to look interesting.
The company helps pharma companies identify and reach patients who need specific diagnostic tests before they can receive precision medicines, using its DXRX platform and network of diagnostic labs.
H1 results yesterday were strong. Revenue rose 22% to £17.5m, ARR jumped 79% to £29.4m, net revenue retention reached 149%, churn fell to 6%, and the order book grew 38% to £43.7m. Gross margins are now 85% and free cash flow turned positive. This is against an enterprise value around £152m.
The key question is whether Diaceutics is genuinely becoming a scalable healthcare data/software platform or if it is still a services-heavy consultancy. That distinction will decide whether the stock can make a much larger move. $DXRX.L
