

Quantitative research platform for systematic trading strategies. Build & test ideas with point-in-time discipline. https://xitter.cf/t.co/SzQTazuXoc
Joined July 2026
- Tweets133
- Following508
- Followers107
- Likes33



Unhinged Momentum Against Timed Momentum: The Rate of Change, Applied to Time It and to Tame It. Every six months from 2006 to 2025, we took the S&P 500's ten steepest trends and ran them twice. Once as is, once with rate-of-change indicator.
quanterlab.com/research/unhi…

We built one S&P 500 stock portfolio that picks its stocks by value, quality and momentum, weighted by the market's regime. Then we ran it twice from 2006 to 2025: once with a hidden Markov model deciding the regime, once with the VIX.
quanterlab.com/research/hidd…

Clenow’s Stocks on the Move, Tested Apart Ten Years After the Book quanterlab.substack.com/p/cl…

Andreas Clenow's book "Stocks on the Move" In short: buy the stocks that rose fastest and most smoothly over the last three months, and stop buying new stocks while the whole market is falling. The book's promise is to beat the market. We tested it apart.
quanterlab.com/research/clen…

QuanterLab is now listed in Anthropic's own directory.
Describe your rule in a Claude chat and QuanterLab tests it for you:
"Would the 200-day line have beaten simply holding Tesla?"
Free runs every day.
claude.ai/directory/quanterl…

Two Kinds of Crash, Two Kinds of Protection: the 200-Day Line and Volatility Targeting, 2000 to 2025
youtube.com/watch?v=a_Msuxnk…
Two Kinds of Crash, Two Kinds of Protection: the 200-Day Line and Volatility Targeting, 2000 to 2025
Two famous crash rules, tested on SPY over a quarter century and on 13 other funds.
quanterlab.com/research/two-…

In Search of the Market's Payday. We slid a window across the month and the strongest days come a few days earlier, so the famous four days start on a day that lost money on average.
quanterlab.com/research/in-s…

A Stochastic Model Against a Geometric Rule: the Kalman Filter and the 200-Day Line
quanterlab.com/research/a-st…

QuanterLab is now in ChatGPT's plugin directory.
Add it and ask ChatGPT about any of our walk-forward studies: it reads the paper and answers with the numbers and a link to the page.
Works with a free QuanterLab account.
chatgpt.com/plugins/plugin_a…

A Stochastic Model Against a Geometric Rule: The Kalman Filter and the 200-Day Moving Average @SSRN papers.ssrn.com/sol3/papers.…
Mean reversion is the idea that a price pushed too far in a few days tends to come part of the way back. The research explains it as a trade, discusses the mechabism.
quanterlab.com/research/navi…

Thirty Years of the Technology Industry, From Dot-Com to ChatGPT: Its Strong Stories and Their Relation to Capital Expenditure
(September 22, 2026). Available at SSRN: ssrn.com/abstract=7507181 or dx.doi.org/10.2139/ssrn.7507…

Post-Earnings Drift in the Point-in-Time S&P500 universe across different sector constituents, different holding periods, different entry points.
xitter.cf/QuanterLab/status/2102…


papers.ssrn.com/sol3/papers.…
Post-Earnings Drift in the Point-in-Time S&P500 universe across different sector constituents, different holding periods, different entry points.

papers.ssrn.com/sol3/papers.…
Post-Earnings Drift in the Point-in-Time S&P500 universe across different sector constituents, different holding periods, different entry points.
QuanterLab
Rebuilding The Fama-French Factor Construction Inside the Point-in-Time S&P 500 Available at SSRN: ssrn.com/abstract=7465182 or dx.doi.org/10.2139/ssrn.7465…

QuanterLab
Rebuilding The Fama-French Factor Construction Inside the Point-in-Time S&P 500 Available at SSRN: ssrn.com/abstract=7465182 or dx.doi.org/10.2139/ssrn.7465…
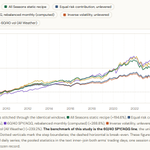
Rebuilding the Fama-French factor construction inside the point-in-time S&P 500: value, dividend yield, profitability and net issuance, 2006 to 2025
quanterlab.com/research/the-…

QuanterLab retweeted

Fama-French factors inside the S&P 500: walk-forward 2006 to 2025 [@QuanterLab] dlvr.it/TVWQYt