

Stock Market + Conservation, Wild Life. Have no stock specific advice to give. I have NO group. Not on any SM other than Twitter
Joined February 2022
- Tweets14.1K
- Following388
- Followers26.6K
- Likes29.1K




Pinned Tweet
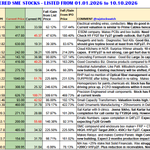
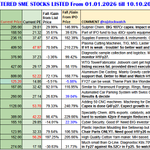
🌟🌟LIST OF GOOD SME IPOs LISTED FROM 01 Jan 2026 (Sheet 1, Sheet 2 & Sheet 3)
🗒️Data Covers: IPO Price, IPO P/E, List Price, Current Price, Current P/E, % Gain with respect to IPO Price. For most recent stocks, Capex Completion target time is given in Comments.
🩷LIKE, SAVE in 🔖BookMarks for Detailed Study
Some stocks start discounting future earnings , very early, considering capex. But not all. If price is still at lower valuation, BUT major capex is ongoing, it's an opportunity to track and enter, when price action starts. 👍
Suggest not to take Promoter's every word in Investor presentations, as Ved Vakya. Lot of fluff and inaccurate stuff will be there in their talks. 👎
Please go through recent NSE order announcements / capex status / business updates too before investing.👍
Do note , even some of these stocks could fail, 👎since we are yet to see First Post-Listing Financials. And there can be cooked up 👎revenue and extra high margins which could disappear with H1 result. So one has to track results closely. No blind bets.
SHEET 1
ACME INDIA INDUSTRIES
TNA SOLUTIONS
EVERESTIMS TECHNOLOGIES
SJP ULTRASONICS
VANS ELECTROENGINEERING
ACME UNIVERSAL SAFEZONE 9
ROOPA SCREEN
POOJA LOGISTICS
FX MULTITECH
ROBOKIDZ EDUVENTURES
SPECTRAA TECHNOLOGY SOLUTIONS
RAKSAN TRANSFORMERS
MAHARAJA & SPEEDEX INDIA
AMTECH ESTERS
QUALIANCE INTERNATIONAL
ASHUTOSH FIBRE
🩷LIKE, SAVE in 🔖BookMarks for Detailed Study
Sheet 2 and Sheet 3 in Thread below 1/3


ONLY GOOD SME STOCKS, LISTED FROM 01 Jan 2026 - (After filtering out Cockroaches 🪳)
🌟By tomorrow. we will look at list of these stocks with IPO Price, IPO P/E, List Price, Current Price, Current P/E, % Gain with respect to IPO Price as well as List Price with Comments
This will help to quickly figure out stocks, where there could be further opportunity.
Hope to release on Monday Morning! Should help in your research and probably spot ones which have not gone up much 👍
🫱Avana Electrosystems FY27 H1 RESULTS. H1FY27 RESULTS. Rs.142 was at 27p/e. Now 26x👍
Overall : Flat 🫱
Existing units will be shut down and machinery shifted to IPO funded new Unit . Expected to start in Dec 2026. Overall, expect 2months production loss due to shifting of machinery. (No new machinery in capex. Only Civil and electrification works)
50% revenue fro Control Panels (Highly competitive segment)
50% Revenue from relays where big players wont give breathing space on margin .
Not expecting any fireworks even after capex in this biz. Especially since no new machinery added. Only shifting of existing ones.
H1 FY27 Vs.H2 FY26
REV:Rs. 43.5Cr Rs. Vs Rs. 48Cr👎
PAT:Rs. 6.4Cr Vs Rs. 6.1Cr👍
(May Compare with H1FY26 Rev=Rs. 37Cr & PAT=Rs. 5.6Cr ) GOOD 👍
TTM Vs FY26
REV:Rs.91.5Cr Vs Rs. 85Cr 👍
PAT: Rs. 12.5Cr Vs Rs. 11.7Cr👍
SME IPO was in JAN 2026 at Rs.59


👎🔻VISHNUSURYA PROJECTS FY27 H1 RESULTS. H1FY27 RESULTS. Rs. 152 was at 10p/e. Now 17.5x👎
Gone case!👎👎
H1 FY27 Vs.H2 FY26
REV:Rs. 132Cr Rs. Vs Rs. 190Cr 👎
PAT:Rs.9.2 Cr Vs Rs. 13Cr 👎
(May Compare with H1FY26 Rev=Rs. 168Cr & PAT=Rs. 23Cr ) BAD 👎
TTM Vs FY26
REV:Rs.322Cr Vs Rs. 358Cr 👎
PAT: Rs. 21.2Cr Vs Rs. 36Cr 👎
SME IPO was in OCT23 at Rs68
📌 Vishnusurya Projects and Infra Limited informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #VISHNUINFR 📄🧾


😡MOPSHOP - Basically trades brooms, mops and floor / toilet cleaning items. People are crazy to invet in such business . Shows 3.6Cr Pre IPO profit tosell the IPO
And after IPO, for the first 6 months profit is down to, DOWN TO, DOWN TO Rs.49 Lakhs!
850 people decided selling brooms is good business 🤣


👎SILVERSTORM PARKS FY27 H1 RESULTS. H1FY27 RESULTS. Rs.123 was at 14.6p/e. Now 13x 👍
Being in Western Ghats no amount of new rides or other paraphernalia can give boost in Monsoon season (H1).
There will be severe pressure on H2. It has to bill Rs.35 to 40Cr with 15Cr to 20Cr PAT for stock to survive after a potential beating, with this Results.👎
H1 FY27 Vs.H2 FY26
REV:Rs. 22.1Cr Rs. Vs Rs. 31.3Cr👎
PAT:Rs. 6Cr Vs Rs. 15Cr 👎👎
(May Compare with H1FY26 Rev=Rs. 13.5Cr & PAT=Rs.4 Cr ) GOOD 👍
TTM Vs FY26
REV:Rs.53.4Cr Vs Rs. 44Cr👍
PAT: Rs. 21Cr Vs Rs. 19Cr👍
SME IPO was in July 2026 at Rs.133


❓LAKSHYA POWERTECH FY27 H1 RESULTS. H1FY27 RESULTS. Rs.102 was at 10p/e. Now 14x 👎
Low valuation because the original core business is as DG set erection agent of POWERICA. Company has been trying hard to get into other segments
THERE IS NO INDICATION OF ANY BILLING FROM VEDANTA O&M ORDER (Rs.642Cr – 4 years Rajasthan) first announced in APRIl 2026. Obviously, has not taken-off, in 5 months. 👎
While that is stuck, Company announced another Rs.276Cr order (AP) From Vedanta in Sept 26
Market has IGNORED these so far. Balance sheet does not indicate any significant activity to service these huge contracts.
🟢If execution of these contracts REALLY commence, ~100Cr should get added to topline ! May be some delay. To Monitor announcements.👍
H1 FY27 Vs.H2 FY26
REV:Rs. 83Cr Rs. Vs Rs. 91Cr 👎
PAT:Rs. 4.4Cr Vs Rs. 3Cr 👍 (margin improved)
(May Compare with H1FY26 Rev=Rs. 90Cr & PAT=Rs. 7Cr ) 👎
TTM Vs FY26
REV:Rs.174Cr Vs Rs.181 Cr 👎
PAT: Rs. 7.4Cr Vs Rs. 10Cr 👎
SME IPO was in OCT2024 at Rs.180


👍DIVINE POWER ENERGY FY27 H1 RESULTS. H1FY27 RESULTS. Rs. 681 was at 63p/e. Now 56x👍
Lot of activity on corporate side with mergers, new units and expansion which has driven up valuation. 👍Understand still more to come.
H1 FY27 Vs.H2 FY26
REV:Rs. 359Cr Rs. Vs Rs. 347Cr 👍
PAT:Rs. 11Cr Vs Rs. 19Cr 👎 (margin 🔻)
(May Compare with H1FY26 Rev=Rs. 279Cr & PAT=Rs. 8Cr ) V GOOD 👍
TTM Vs FY26
REV:Rs.706Cr Vs Rs. 628Cr 👍
PAT: Rs. 30Cr Vs Rs. 27Cr 👍
SME IPO was in Feb 2024 at Rs.40


🚨ASHWINI CONTAINER MOVERS. Rs.152 was at 16p/e NOW 45x. 🔴
This had appeared like a good niche business. BUT there is severe Pre IPO margin collapse. (Topline is maintained at around 75Cr like in H2Fy26.)
TTM Pat is down from Rs.14Cr to just 5Cr🔴


👍APSIS AEROCOM FY27 H1 RESULTS. H1FY27 RESULTS. Rs.478 was at 75p/e. Now 69x 👍
FY27 target is ~48Cr. Pre IPO margin was too high to sustain. It has come down to 30%.
Assume, new Unit has actually commenced commercial operation. (Utilization report to be checked)
IPO NOTE: IPO funded (Rs.27Cr) 20,000sft new unit in North Yelahanka. This Unit will have a capacity of 3Lakh components against 1.5Lakh components in Unit1.
H1 FY27 Vs.H2 FY26
REV:Rs. 21Cr Rs. Vs Rs. 17Cr 👍
PAT:Rs. 4Cr Vs Rs. 4.2Cr 🫱 (margin)
(May Compare with H1FY26 Rev=Rs. 13.7Cr & PAT=Rs. 3.3Cr ) GOOD 👍
TTM Vs FY26
REV:Rs.38Cr Vs Rs. 30.7Cr 👍
PAT: Rs. 8.2Cr Vs Rs. 7.5Cr 👍
SME IPO was in March 26 at Rs.110
📌 Apsis Aerocom Limited informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #APSISAERO 📄🧾


🫱 BEEZAASAN EXPLOTECH FY27 H1 RESULTS. H1FY27 RESULTS. Rs. 775 was at 87.6p/e. Now SAME 🫱
Valuation is purely on expectation of capex completion which is delayed. Out of around 30Cr only 12Cr is spent. And there can be further delay since approvals are not fast for explosive segment. Take good care of some part profit!
H1 FY27 Vs.H2 FY26
REV:Rs. 128Cr Rs. Vs Rs. 112Cr 👍
PAT:Rs. 8.4Cr Vs Rs. 5Cr 👍
(May Compare with H1FY26 Rev=Rs. 101Cr & PAT=Rs. 8.4Cr ) OKAY 🫱
TTM Vs FY26
REV:Rs.240Cr Vs Rs. 213Cr 👍
PAT: Rs. 13.4Cr Vs Rs. 13.4Cr🫱
SME IPO was in March 2025 at Rs.175
📌 Beezaasan Explotech Ltd informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #BEEZAASAN 📄🧾


🍏👍BLUEWATER LOGISTICS FY27 H1 RESULTS. H1FY27 RESULTS. Rs.513 was at 23 p/e. Now 12x 👍
Growth is commendable. Superb. 👍
But there are challenges too: CF is at –ive Rs.106Cr . Receivables at Rs.224Cr. Debt has ballooned to almost 10 times w. r. to March end. Now above 320Cr. Naturally, this year servicing costs will spike. Asset heavy operation.
H1 FY27 Vs.H2 FY26
REV:Rs. 484Cr Rs. Vs Rs.248 Cr 👍
PAT:Rs. 30Cr Vs Rs. 16.5Cr 👍👍
(May Compare with H1FY26 Rev=Rs.138 Cr & PAT=Rs. 8.6Cr ) VERY GOOD 👍👍
TTM Vs FY26
REV:Rs.732Cr Vs Rs. 386Cr 👍
PAT: Rs. 46.5Cr Vs Rs. 25Cr 👍👍
SME IPO was in June 2025 at Rs.135
📌 Blue Water Logistics Limited informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #BLUEWATER 📄🧾


👍GRE RENEW ENERTECH FY27 H1 RESULTS. H1FY27 RESULTS. Rs. 237 was at 25 p/e. Now 18x👍
Should not get carried away by post IPO price move. Solar stocks valuation is below 10p/e in most cases. Also margin has dropped from 16% in H2 Fy26 to below 10% in H1. Take care.🔻
H1 FY27 Vs.H2 FY26
REV:Rs. 139Cr Rs. Vs Rs. 82Cr 👍
PAT:Rs. 9Cr Vs Rs. 9.6Cr 🫱 (margin drop)
(May Compare with H1FY26 Rev=Rs. 44Cr & PAT=Rs. 4Cr ) GOOD 👍
TTM Vs FY26
REV:Rs.221Cr Vs Rs. 126Cr 👍
PAT: Rs. 18.6Cr Vs Rs. 13.6Cr 👍
SME IPO was in Jan 2026 at Rs.105


👍SHRI AHIMSA NATURAL FY27 H1 RESULTS. H1FY27 RESULTS. Rs. 397 was at 32p/e. Now 30.5x👍
The Capex is still ongoing with likely completion by April –May 2027. (Delayed. Should have been completed in this Q2). Better to wait out for capex driven growth in revenue. 👍
Notes from IPO Review: Total of Rs.70Cr capex out of which IPO amount is Rs.27.7Cr. Caffeine Anhydrous Natural 270MTPA to 970MTPA, Coffee Bean Extract 300MTPA to 500MTPA and Crude Caffeine from Nil to 63MTPA. Total Capacity will go up from 570MTPA to 1533MTPA (~3X) by addition of 963MTPA Capacity. RM is fully imported from Mexico and Vietnam. 70% Exports goes to US and EU👍
Utilization: Out of Rs.27.7Cr capex, Rs.6.5Cr is pending. That looks okay with April 2027 target.
H1 FY27 Vs.H2 FY26
REV:Rs. 82Cr Rs. Vs Rs. 66Cr 👍
PAT:Rs. 15.8Cr Vs Rs. 14.6Cr 👍
(May Compare with H1FY26 Rev=Rs. 63.4Cr & PAT=Rs. 14.5Cr ) GOOD 👍
TTM Vs FY26
REV:Rs.148Cr Vs Rs. 130Cr👍
PAT: Rs. 30.4Cr Vs Rs. 29.1Cr👍
SME IPO was in April 2025 at Rs.119
📌 Shri Ahimsa Naturals Limited informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #SHRIAHIMSA 📄🧾


🫱TBI CORN FY27 H1 RESULTS. H1FY27 RESULTS. Rs.70 was at 6.9p/e. Now 6.3 x 🫱
The long delay from 2024 June IPO time for capex completion really took market's interest, away. As per RHP capex period was just 7 months.
Everyone waited for revenue uptick from H1 FY26 (Sept 25). Then March 26. Just marginal growth with substantial margin reduction is what investors got. (15% pre IPO to 10% and now in H1FY27 11%)
AK had taken Pre IPO stake (4.5%) and that drove post listing craziness with price shooting to around Rs.400. NOW back on hard surface at Rs.70. (Holding long has destroyed potential profit for many investors)
H1 FY27 Vs.H2 FY26
REV:Rs. 197Cr Rs. Vs Rs. 167Cr 👍
PAT:Rs. 11.7Cr Vs Rs. 8.4Cr 👍
(May Compare with H1FY26 Rev=Rs. 138Cr & PAT=Rs. 10.3Cr ) GOOD 👍
The long delay from 2024 June IPO time for capex completion really took markets interest away. As per RHP capex period was just 7 months.
TTM Vs FY26
REV:Rs.364Cr Vs Rs. 303Cr 👍
PAT: Rs.20.1Cr Vs Rs. 18.6Cr 👍
SME IPO was in JUNE 2024 at Rs.94


👍VASA DENTICITY FY27 H1 RESULTS. H1FY27 RESULTS. Rs.447 was at 65p/e.(after Q1) Now SAME 🫱
There was severe margin issue in Fy26 H2. That problem seem to be fully resolved. So, for the year can expect Rs.18 to 20Cr PAT against 12Cr (TTM)👍
H1 FY27 Vs.H2 FY26
REV:Rs. 172Cr Rs. Vs Rs.148 Cr👍
PAT:Rs. 9.3Cr Vs Rs. 2.7Cr👍
(May Compare with H1FY26 Rev=Rs. 135Cr & PAT=Rs. 7.5Cr ) GOOD 👍
TTM Vs FY26
REV:Rs.320Cr Vs Rs. 279Cr 👍
PAT: Rs. 12Cr Vs Rs. 11Cr 👍
SME IPO was in June 2023 at Rs.128
📌 Vasa Denticity Limited informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #DENTALKART 📄🧾


SHANTI INORGANICS FY27 H1 RESULTS. H1FY27 RESULTS. Rs.183 was at 30p/e. Now xxxxx?
There is nothing to report / compare except that Fy27 H1 margin is at 19% against 22% of Fy26 whole year.
No relative data has been provided by the company unlike 99.99% companies which report financials in standard format, first time after IPO.
Even Valuation can not be computed, since there is no H2Fy26 data. As per strict rules this may be fine, but that is not what everyone else does!
H1 FY27 Vs.H2 FY26
REV:Rs. 54Cr Rs. Vs Rs. xxxx Cr
PAT:Rs. 7.3Cr Vs Rs. xxxxCr
(May Compare with H1FY26 Rev=Rs. xxxCr & PAT=Rs. xxxxCr )
TTM Vs FY26
REV:Rs.xxxCr Vs Rs.73Cr
PAT: Rs. xxxxCr Vs Rs.10.25Cr
SME IPO was in SEPt 2026 at Rs.83
@SEBI_updates is this okay?😂
📌 Shanti Inorganics Limited informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #SHANTIINOR 📄🧾


👎ANAWIL WIRE. The sky high margin was simply not sustainable as discussed earlier. It has skidded down to 16% in H1 from 45% to 50% reported in pre ipo period. Valuation was based on the huge margin. That will be impacted.


👍PARMESHWAR METAL FY27 H1 RESULTS. H1FY27 RESULTS. Rs. 270 was at 13 p/e. Now 8.8x 👍
Topline growth is good like SUNLITE. Overall, in copper recycling, top players are doing well 👍
H1 FY27 Vs.H2 FY26
REV:Rs. 1427Cr Rs. Vs Rs. 1130Cr 👍
PAT:Rs.23.5 Cr Vs Rs. 23.5Cr 🫱(margin bit lower)
(May Compare with H1FY26 Rev=Rs.846Cr & PAT=Rs. 9Cr ) VERY GOOD 👍
TTM Vs FY26
REV:Rs.2557Cr Vs Rs. 1976Cr 👍
PAT: Rs. 47Cr Vs Rs. 32.5Cr 👍
SME IPO was in Jan 2025 at Rs.61
📌 Parmeshwar Metal Ltd informed the exchange about its approval for the financial results for the period ended September 30, 2026. #SME #PARMESHWAR 📄🧾


👎JAY BEE LAMINATIONS FY27 H1 RESULTS. H1FY27 RESULTS. Rs.87 was at 10.8p/e. Now 9.7x 👍
When VILAS underperformed, everyone believed JAY BEE will perform well. The Transformer Lamination segment is down the drain. There was so much expectation from this segment. Gone for a toss.
Lamination Segment Revenue is down from 219Cr in H1FY26 to 180Cr now. Receivables are crushing at Rs.174Cr 👎
H1 FY27 Vs.H2 FY26
REV:Rs.214.6Cr Rs. Vs Rs. 330Cr 👎
PAT:Rs. 5.6Cr Vs Rs.14.6 Cr 👎
(May Compare with H1FY26 Rev=Rs. 220Cr & PAT=Rs. 3.7Cr ) 👍
TTM Vs FY26
REV:Rs.544.6Cr Vs Rs.550 Cr 👍
PAT: Rs. 20.2Cr Vs Rs. 18.3Cr 👍
SME IPO was in SEPT 2024 at Rs.146


👍E FACTOR EXPERIENCES FY27 H1 RESULTS. H1FY27 RESULTS. Rs. 189 was at 12.5p/e. Now 11 x 👍
This is a proven case of H2 heavy business . Overall OKAY👍
H1 FY27 Vs.H2 FY26
REV:Rs. 72.5Cr Rs. Vs Rs. 140Cr 👎
PAT:Rs. 7.3Cr Vs Rs. 15Cr👎
(May Compare with H1FY26 Rev=Rs. 53Cr & PAT=Rs. 5Cr ) GOOD 👍
TTM Vs FY26
REV:Rs.212.5Cr Vs Rs. 192Cr 👍
PAT: Rs. 22.5Cr Vs Rs. 20Cr 👍
SME IPO was in OCT 2023 at Rs.75


