

IA; Economía; Energía; Derechos Trans; she/her
Chile
Joined August 2018
- Tweets109K
- Following7.1K
- Followers4.3K
- Likes537K





Pinned Tweet
Este paso que estoy dando debería haberlo dado hace mucho y puede que sea uno de los más importantes, quizá el más, desde hoy la persona que era José Joaquín ha terminado, ahora soy María Josefa.


Se pasaba las medias películas esta TERF


María Josefa GK 🏳️⚧️ retweeted

Ya se sabe que las terfs son ignorantes, pero nunca me va a dejar de sorprender su capacidad para hablar con tanta soltura de weás que no tienen idea. Butch y femme son identidades sociopolíticas/de género para muchas personas, no son una estética y no se basan en roles sexuales.

María Josefa GK 🏳️⚧️ retweeted

una mujer trans jamas sera un hombre
un hombre trans jamas sera una mujer


María Josefa GK 🏳️⚧️ retweeted

They don't know $72B of Anthropic's $80B loss is non-cash accounting. It's just Amazon's convertible notes getting repriced because the company got more valuable and those notes convert at IPO anyway.

María Josefa GK 🏳️⚧️ retweeted

so anthropic is basically breakeven, revenue growing 10x per year and the headline about $80B losses is just bc they owe investors stock (and their stock has gone up so much it is a like short position from an accounting perspective)
and they are sitting on fable 5.5
María Josefa GK 🏳️⚧️ retweeted

i can't wait for people to unironically say Anthropic is cooking the books on the most scrutinized IPO of our lifetimes
faking the numbers on this would get your ass sent to the secret blacksite underneath Guantanamo
Dario Amodei sabe cómo jugar sus cartas.

Anthropic already has $132bn of cash.
Add a ~$140bn IPO, $77bn of committed funding from Google, Amazon and Broadcom and cash from a business growing 14x a year and it could be sitting on roughly $400bn by the end of 2027.
That's more firepower than almost any company on earth, aimed at one thing and one thing only: compute.
In a race where the winner is whoever can build the most, Anthropic is about to have the deepest pockets in AI outside of Big Tech itself.

María Josefa GK 🏳️⚧️ retweeted

People seem to forget how unprecedented this is


Anthropic has filed an S-1 registration statement with the SEC related to its proposed IPO.
Read more: anthropic.com/news/s1-sec
Legal disclaimer: A registration statement relating to these securities has been filed with the SEC but has not yet become effective. These securities may not be sold, nor may offers to buy be accepted, prior to the time the registration statement becomes effective. This post does not constitute an offer to sell or the solicitation of an offer to buy these securities, nor shall there be any sale of these securities in any state or jurisdiction in which such offer, solicitation or sale would be unlawful prior to registration or qualification under the securities laws of any such state or jurisdiction.

María Josefa GK 🏳️⚧️ retweeted

Anthropic $ANT quarterly revenue and operating income:

ALT Bar chart of Anthropic’s quarterly revenue and operating income from Q1 2025 to Q2 2026. Revenue rises from $0.4B to $11.6B. Operating income goes from losses of $0.9B, $1.2B, $3.1B, $2.8B and $1.7B to a $1.0B profit in Q2 2026.


María Josefa GK 🏳️⚧️ retweeted

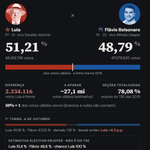
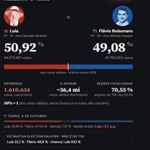
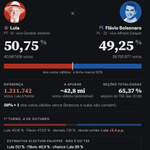
The fact that Brazilian markets panicked and crashed the three times Lula was previously elected (and are doing so a fourth time now), only to boom during his terms in office, poses a real challenge to the efficient market hypothesis.


María Josefa GK 🏳️⚧️ retweeted

CINE, si me preguntan.


🚨 COMUNICADO: Desde @EleccionesDatos tomamos la decisión de SUSPENDER la publicación y cobertura de los resultados de las elecciones en Brasil 🇧🇷.
No vamos a ser cómplices de números adulterados ni de manipulaciones flagrantes🚨❌
María Josefa GK 🏳️⚧️ retweeted

1/Anthropic’s S-1 is out.
2/ Revenue, quarter by quarter ($M)
Q1'25: 376
Q2'25: 787
Q3'25: 1,382
Q4'25: 2,040
Q1'26: 4,731
Q2'26: 11,555
Q2'26 revenue was up 1,368% YoY. Compute & infra costs were up 300% over the same period.
Q2'26 was the first quarter with positive GAAP operating income: $974M.
3/ How “Run-Rate Revenue” is defined
Trailing-28-day consumption fees × 13
+ monthly subscription fees × 12
Three caveats from the S-1:
-It includes customers later found to be violating the usage policy
-It is seasonal: usage dips in summer and winter holidays
4/ Revenue is recognized gross
When Claude is sold through the AWS, GCP or Azure marketplaces, Anthropic is the principal. It books the full amount as revenue, and the cloud provider’s fee goes into Sales, marketing & partnerships.
The marketplace share of revenue has climbed fast:
11% (2023) → 32% (2024) → 47% (2025) → 48% (H1'26)
Adjust for this before comparing multiples with companies that report net.
5/ Distillation
The S-1 puts a number on it:
“we estimate that revenue from such customers represented approximately 5% to 7% of our revenue for the nine months ended September 30, 2026”
These are customers violating the usage policy or commercial terms. Applied to ~$33B of 9M revenue, that’s roughly $1.7–2.3B.
Enforcement was stepped up in Aug–Sep, and the company expects the share to decline. The S-1 says the estimate “requires judgment and may change.”
6/ Visibility is low
RPO at 6/30/26: $10.8B
~75% of that is recognized in the next 12 months, so cRPO ≈ $8.1B
Deferred revenue: $1.65B
Q2 annualized revenue is ~$46B, so cRPO covers less than 20% of it.
80% of revenue is consumption-based, and next year’s revenue depends almost entirely on usage.
7/ The compute bill
Disclosed commitments:
Broadcom TPU leases: ~$161B
SpaceXAI (NVIDIA GPUs): up to $121B, ~$3.1B a month from Dec’26
Google: ≥$115B, plus $125–150B more of TPU capacity in 2028–31
Amazon: ≥$110B
Microsoft: ≥$45B
Nscale: ~$45B
Lambda: ~$41B
AMD: >$20B
That adds up to roughly $780–810B.
8/ The mismatch to watch
Revenue is variable and consumption-driven. Compute costs are fixed, multi-year and take-or-pay.
On top of that, the Broadcom leases, the credit agreement and the convertible notes include cross-default provisions.
This is the single most important risk in the filing.
9/ Demand is real
NRR ~900% (ex-Pro/Max)
Customers paying more than $100K / $1M / $10M a year: 11,900+ / 1,900+ / ~250
No single customer was >10% of 9M’26 revenue
Top 5 customers ≈ 25% of 9M revenue
Q3: 79% of revenue came from outside the top 5, up from 64% in Q1
Claude Enterprise users who also use Claude Code spend ~20x more than those who don’t
10/ Dilution
$77B of convertible capacity: Google $20B, Amazon $15B, Broadcom $42B, settled in shares at a trailing VWAP
Google can buy up to $10B more stock at the IPO price
A Public Benefit Fund already holds 5% of fully diluted shares, and can get up to +2% more for every 50% rise in the share price
