

I post about: AI and Founder stuff | ex-Startup Founder |Pod host @fs_brew| Newsletter on AI: https://teapaw.org/t.co/Fu2lWFMhdN / work: https://teapaw.org/t.co/G9oxc3LU7p
Dubai, United Arab Emirates
Joined September 2010
- Tweets4.7K
- Following1.8K
- Followers712
- Likes1.5K




Pinned Tweet
Is OpenAI raising $30 billion at a valuation of $1.25 trillion? onemorethinginai.com/p/is-op…

Please look at this and tell me why you are shying away from spending on AI in your company?

This just in: Menlo Ventures’ 2026 The State of Enterprise AI report is live.
In 2026, enterprise AI spend skyrocketed 5.4x from $33B to $177B in a single year.
The full report covers how AI became an economy-scale force this year, and shows where the dollars are going, which markets are working, and which models buyers choose.
More from @timt, @mejoff, @deedydas, and @derekgxiao: mnlo.vc/enterprise-ai-26

Masayoshi Son made one of the greatest investments in venture capital history after meeting Jack Ma for just a few minutes.
The year was 2000. Jack Ma was building a small internet company in China called Alibaba.
The company was barely a year old. It had an ambitious founder, a small team and a plan to help Chinese businesses sell their products online.
But it needed money.
Ma met Masayoshi Son, the founder of SoftBank, who was investing heavily in internet companies.
The meeting was short.
Son later said he was impressed by Ma's confidence, passion and understanding of what he wanted to build.
There was something unusual about the decision.
Alibaba was still an early-stage business. China had a relatively small internet population, and online commerce was far from established.
Son wasn't investing in a proven business model. He was betting on the founder and the opportunity.
SoftBank invested approximately $20 million in Alibaba.
Over the following two decades, Alibaba became one of the world's largest e-commerce companies.
At its peak, SoftBank's stake was worth well over $100 billion.
Lionel Barber discusses the investment in Gambling Man, his biography of Son and it is a rollicking read!
What makes this story interesting is how little conventional financial analysis could have told Son at the time.
Alibaba didn't have years of profitable operations or a long record of customer growth.
The investment depended on Son's judgment about Ma and the future of China's internet economy.
Of course, Son made many other bets that didn't work out.
That's what makes the Alibaba investment worth examining.
Was Son exceptionally good at spotting founders, or was he simply willing to take risks that most investors would avoid?
Perhaps the real skill was knowing when to trust conviction, even when the numbers couldn't yet support it.

In 2017, Sequoia Capital faced a problem it couldn't solve by being a better investor.
The problem was Masayoshi Son.
In September 2017, Michael Moritz, one of Sequoia's senior partners, sent an email to his colleagues.
He was worried about SoftBank's new $100 billion Vision Fund.
Sequoia had built its reputation by investing early in promising technology companies.
Its investments included Apple, Google and many other successful businesses.
The approach was straightforward. Find good founders, invest early and help them build valuable companies.
SoftBank was doing something different. It was offering startups hundreds of millions, sometimes billions, of dollars.
For founders, the choice was becoming difficult. They could raise a smaller amount from a traditional venture capital firm. Or they could accept a much larger investment from SoftBank.
Moritz was concerned that Sequoia could lose access to attractive investments.
He suggested that the firm consider raising $20 billion to compete.
Lionel Barber describes the episode in his book, Gambling Man that I have been reading and posting stories that caught my attention.
What followed was interesting. SoftBank's large investments helped some startups grow quickly.
But they also encouraged companies to spend heavily in pursuit of market share (WeWork / Uber are examples).
In several cases, the underlying businesses struggled to justify their valuations.
The same question is relevant to AI today.
Technology companies are raising extraordinary amounts of capital to build models, infrastructure and applications.
Some will create enormous value. Others may discover that funding alone is not a competitive advantage.
When capital becomes almost unlimited, it doesn't eliminate business risk.
It can simply postpone the moment when everyone has to confront it.

Masayoshi Son spent $17 billion on a promise from Steve Jobs. There was no written contract.
In 2005, Masayoshi Son met Steve Jobs. Apple had not launched the iPhone. In fact, nobody outside Apple knew exactly what the company was developing.
But Son believed Apple was working on a mobile phone. He had even prepared a rough drawing of what he thought the device might look like. When Son showed Jobs the drawing, Jobs wasn't particularly impressed (we have heard of his penchant for design).
But according to Son, Jobs indicated that Apple was working on something similar. Son immediately asked whether he could sell the device exclusively in Japan. There was one small problem.
Son didn't own a mobile phone company. Jobs pointed this out. Son said he would buy one!!
According to Son, Jobs agreed in principle to work with him. Nothing was signed.
In 2006, SoftBank acquired Vodafone's Japanese mobile business in a transaction valued at around $17 billion.
It was a major acquisition, particularly for a company that had previously focused on internet and technology investments.
The iPhone launched in 2007. SoftBank became its exclusive Japanese carrier when the device entered the market in 2008. The partnership helped SoftBank compete against larger, established telecom operators.
Lionel Barber recounts the story in Gambling Man, which I have been reading and sharing stories from (btw it is a must read for those interested in Masa's story).
What makes this interesting is the sequence of decisions.
Son didn't buy a telecom company and then look for ways to compete. He first identified a product that he believed could change the market.
Then he acquired the business needed to distribute it.
The real gamble wasn't buying a telecom company.
It was betting billions that an unreleased product, and Steve Jobs's word, would change the economics of that acquisition.


Masayoshi Son spent $17 billion on a promise from Steve Jobs. There was no written contract.
In 2005, Masayoshi Son met Steve Jobs. Apple had not launched the iPhone. In fact, nobody outside Apple knew exactly what the company was developing.
But Son believed Apple was working on a mobile phone. He had even prepared a rough drawing of what he thought the device might look like. When Son showed Jobs the drawing, Jobs wasn't particularly impressed (we have heard of his penchant for design).
But according to Son, Jobs indicated that Apple was working on something similar. Son immediately asked whether he could sell the device exclusively in Japan. There was one small problem.
Son didn't own a mobile phone company. Jobs pointed this out. Son said he would buy one!!
According to Son, Jobs agreed in principle to work with him. Nothing was signed.
In 2006, SoftBank acquired Vodafone's Japanese mobile business in a transaction valued at around $17 billion.
It was a major acquisition, particularly for a company that had previously focused on internet and technology investments.
The iPhone launched in 2007. SoftBank became its exclusive Japanese carrier when the device entered the market in 2008. The partnership helped SoftBank compete against larger, established telecom operators.
Lionel Barber recounts the story in Gambling Man, which I have been reading and sharing stories from (btw it is a must read for those interested in Masa's story).
What makes this interesting is the sequence of decisions.
Son didn't buy a telecom company and then look for ways to compete. He first identified a product that he believed could change the market.
Then he acquired the business needed to distribute it.
The real gamble wasn't buying a telecom company.
It was betting billions that an unreleased product, and Steve Jobs's word, would change the economics of that acquisition.

Adam Neumann had built a $20 billion company. His biggest investor told him he wasn't crazy enough.
In 2017, Masayoshi Son visited WeWork's headquarters in New York.
Adam Neumann, WeWork's founder, had prepared a detailed presentation.
He expected to spend two hours explaining the business.
Instead, Son arrived late and said he had only 12 minutes.
Neumann gave him a quick tour of the office. Son liked what he saw.
He invited Neumann into his car, where they continued talking about the company.
During the conversation, Son reportedly took out an iPad and began discussing the terms of an investment (that's pretty quick).
SoftBank went on to invest billions in WeWork. But Son wanted Neumann to think much bigger.
He encouraged him to expand more aggressively and build a global business. Neumann followed that approach and we all know what happened next.
WeWork opened offices around the world, signed expensive long-term leases and spent heavily on expansion.
Revenue grew quickly. Unfortunately, so did the losses.
By 2019, WeWork had reached a private valuation of $47 billion.
Then the company tried to go public.
Its IPO documents revealed serious concerns about its financial performance, governance and business model. The IPO collapsed. Neumann stepped down as CEO.
Four years later, WeWork filed for bankruptcy.
Lionel Barber explores this relationship in his book, The Gambling Man and I have been reading it and sharing stories from it that caught my attention.
The story is interesting because both Son and Neumann believed strongly in the opportunity.
Son wanted faster growth. Neumann was happy to pursue it.
But the company was taking on long-term financial commitments without building a sufficiently strong business.
The interesting thing is that Neumann is at it again- having raised hundreds of millions for his new startup- some investors never learn?
Sometimes the most dangerous investor isn't the one who doubts your vision.
It's the one who believes in it so completely that nobody asks the difficult questions anymore.

Repeat after me: “No pain no gain”… thanks to @georgephilip48 for drilling it while growing up.
Masayoshi Son raised $45 billion in 45 minutes. That's $1 billion a minute!
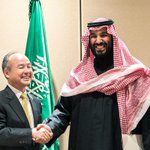
In 2016, Masayoshi Son met Mohammed bin Salman, then Saudi Arabia's deputy crown prince.
Son had a big idea. He wanted to create a $100 billion fund to invest in technology companies around the world.
At the time, even the largest venture capital funds were much smaller.
Son believed technology would change almost every industry. He wanted to invest in the companies leading that change.
But he needed a lot of money. A lot...
Saudi Arabia was looking to reduce its dependence on oil. Son's proposal offered a way to invest in the technology sector.
According to Son, the meeting lasted 45 minutes. He walked away with a commitment of $45 billion. That is a billion for every minute!
The Saudi Public Investment Fund became the main investor in SoftBank's Vision Fund.
Over the next few years, SoftBank invested billions in companies including Uber, WeWork and several other startups.
Some investments worked well. Others lost enormous amounts of money.
WeWork became the most famous example. We know that story only too well...
Son had convinced investors to back his vision. But investing that money successfully turned out to be much harder.
Lionel Barber tells this story in Gambling Man, his biography of Son and I read it this year...decided to share interesting stories from it over the next couple of weeks.
The episode raises an interesting question about fundraising. Does having more money necessarily make a business more successful?
In SoftBank's case, access to enormous amounts of capital sometimes encouraged companies to expand faster than their businesses could support.
Raising money and creating value are two very different skills.
And sometimes, raising too much money makes the second job considerably harder.

Every senior executive needs to try vibe coding with Fable / Astra. It’s the personal trainer / personal chef type of power move
Open AI engineer arrested for corporate espionage onemorethinginai.com/p/open-…

Till after I graduated from my MBA, I didn’t understand the difference between sales and marketing. Sure I got it was to do with getting customers but I mixed it both. I never really respected sales people till I met the really good ones later in my career. Now I am a bit wiser and I know that sales is the only thing that matters in a company. Rest of the functions better be working to enable sales or they are not adding value. Prove me wrong
Laziness, fear and anger- these are three evils that I fight against in my own life. What are yours?
Let AI models trade stocks autonomously with $1k each agentusecases.ai/use-case/le… via @AlexFinn

Google launched Gemini agents and we found a repo to clone any software using AI! onemorethinginai.com/p/googl…

Patrick Collison (the CEO of Stripe) is thinking about how AI “personal agents”, like a smart assistant that works only for you (Hermes / instinct)…could change how people and companies deal with each other. Here’s a simpler version of what he’s saying for people like me:
Big companies are already very good at figuring out how to make money from people who are busy, tired, or not paying close attention. For example, when you book a flight, they often offer expensive extra insurance at the last second because most people just click “yes” without thinking. An AI agent that researches for you and spots bad deals would make people harder to trick, so companies would have less success with those kinds of tactics.
Because agents would carefully compare prices, look for the best coupons, and cancel unused subscriptions, some of the old tricks companies use would stop working as well.
Right now, people who forget to cancel subscriptions end up paying extra, which helps keep prices lower for people who do remember. Agents would reduce that. Collison isn’t sure exactly who would win or lose overall, but he thinks the biggest change might be that companies would have to focus more on actually making better products instead of just advertising harder or getting placed higher in search results.
If an agent always spends the equivalent of many hours researching for you, simply being the most advertised option matters less, and being the best option matters more.
He also wonders whether agents will make everyone buy the same top product (because they’re all rationally choosing the “best” one) or whether they’ll help people find things that better match their own unique tastes.
A lot depends on whether these agents truly stay on your side instead of being influenced by companies. Overall, he hopes this shifts markets so that companies that make genuinely good products get rewarded more than they do today.

Assorted things I've been mulling over regarding agents in the economy:
• Companies are in some sense the original superintelligence. It's often the case that they can use their amortized cognitive surplus to advance their interests against those of certain consumers: relative to the optimization capacity of companies, consumers can be inattentive, underinformed, irrational, etc. (Think, say, of some of the classic insurance upsells at the end of a booking process, which is typically priced substantially above what a regular policy would cost.) Herbert Simon introduced the idea of bounded rationality, and firms often end up benefiting from it. Thanks to personal agents, we will probably get somewhat more rational in how we engage with companies.
• How exactly will outcomes change? Well, certain kinds of price discrimination will work less well (how do coupons work if every agent hunts fastidiously for them?), and certain kinds of customer cross-subsidy will change (today, people who forget to cancel subscriptions subsidize those who don't). Taken across the economy as a whole, I'm not sure what the incidence of all of this will be.
• In corporate strategy, people have long debated the relative importance of distribution and product quality. Perhaps you've made something better, but does anyone know about it? Won't people just continue to buy the ACME Corp Mousetraps? Personal agents will, I think, act as a kind of structural subsidy for product quality. How would markets look different if individuals always spent at least 10 hours researching their purchases? On the margin, focusing on making a product better is, I think, going to become a more effective strategy for companies. This is good!
• It true, a corollary is that information about product quality will become more important and impactful. Today, most people have very limited ability to aggregate and integrate such data, but agents will have insatiable thirst for such signals. (It's often said that data is becoming more valuable because it helps in the training of models. That's obviously true, but I think there's a secondary way in which it's more valuable simply as a complement to cheaper intelligence.)
• A big question is whether agents will increase superstar effects (rational agents all settle on the same product) or increase dispersion (because everyone has slightly different tastes and preferences, which agents are good at eliciting, finally overcoming the artificial clustering we've been subjected to).
• Many internet companies have monetized demand routing, which is in turn often predicated on short attention spans. "I'll click on the first thing I see." This has led to some amount of inefficiency, as companies try to propitiate capricious ranking algorithms and incur various placement fees. It's not all deadweight loss (willingness to pay is itself a kind of signal, which is valuable to buyers), but it's not great. How will the nature and value of this routing change in a world of personal agents? I don't know the answer, but I think that the effects might be pretty big.
• Much of what I'm writing hinges on the assumption that personal agents will be on the consumer's side. I suspect that that will be the winning strategy, but whether it's true, and what it means to be true, involves a lot of other questions.
Taken as a whole, the market is a massively parallelized, decentralized, and highly imperfect value attribution machine, and, taking stock of all of the effects, it seems to me that the quality point may well be the biggest: that agents will change the nature of the backpropagation such that the rewards for better products increase. Maybe this is too optimistic, but I suspect (and hope) that companies that make things that they're proud of will feel that the universe is a little more partisan in their favor.