
Stocks & Stories | Turning every page
Joined January 2025
- Tweets263
- Following355
- Followers1.1K
- Likes717



Pinned Tweet
$OMC reports Oct 22.
Pre acq, OMC was doing $1.5B FCF, IPG $1B. $2.5B combined. Subtract $120MM from divestitures = $2.38B run rate.
2026(e) cost synergies $900MM. Est. cost to get them $250MM. Assume 60% of $650MM savings drops to bottom line (FCF) = $390MM on top of $2,380.
Was revisiting my old $RIG thread.
Rates were close on the short end of the curve, but assumptions ended up being too optimistic, especially margins. OTOH, capex was a lot lower.

My first members-only special situation closed today. $PERF paid $2.00 cash. +3% in 9 days from publishing (SPY -1%). I expected it to close in early November, so I’ll take it.
The write-up is now free to read:
rockwoodnotes.com/members-on…


Posted 3 members-only special situations past week. One US-listed, two int’l, three industries.
If they close, $4k in each could cover cost of rockwoodnotes.com membership.
If they don’t close, well…you know.
Will make public after they play out.
Not investment advice
$OMC another quarter of organic top line growth, profits and margins going up, shares outstanding going down. Synergies on track. Boring. Predictable. Resilient. ~6x 2028e FCF.
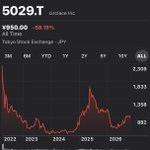
circlace (5029.T) being bought for ¥2,020 per share cash. Board recommending shareholders sell. Two major shareholders (63% of shares) have agreed. Last close before announcement was ¥950.
Big premium to a not cheap-looking stock.

Reminder, rockwoodresearch.com is a free website with event monitor, insider transactions, 13-f's etc. No paywall.
Putting out some updates to reduce errors / improve summaries.
If you have suggestions (looks, features, bugs etc), lmk. Or maybe we all just use Claude now.

Some things I’ve been looking at recently:
$AAME trades @ ~5x (2025) EPS. 0.25x TBV. Bad corp gov. Thought it might go dark but just filed 2025 10k/a. Own minuscule amount for fun < $1.20/sh.
I did post a few members-only special situations I thought were attractive. One is about finished now.
$OMC reports Oct 22.
Pre acq, OMC was doing $1.5B FCF, IPG $1B. $2.5B combined. Subtract $120MM from divestitures = $2.38B run rate.
2026(e) cost synergies $900MM. Est. cost to get them $250MM. Assume 60% of $650MM savings drops to bottom line (FCF) = $390MM on top of $2,380.
And, of course, my largest holding is $OMC, which I call my narcan that keeps me from buying worse ideas (like everything I just tweeted about).
Looking forward to results tomorrow and stock continuing to go +/- $10 around $80 for eternity.
$OMC reports Oct 22.
Pre acq, OMC was doing $1.5B FCF, IPG $1B. $2.5B combined. Subtract $120MM from divestitures = $2.38B run rate.
2026(e) cost synergies $900MM. Est. cost to get them $250MM. Assume 60% of $650MM savings drops to bottom line (FCF) = $390MM on top of $2,380.
OMC 2028(e) FCF likely $3-3.28B
@ 236.5MM s/o (assume another 10% buyback this year (stated/around current prices) + 4% in ‘27 and ‘28) = OMC trades at ~6x ‘28 FCF.
If no synergies are realized, it’s 10x FCF. Or synergies can absorb pricing pressures from AI/economic softness.
However I look at it, $OMC is cheap. It’s a predictable and resilient business model. Buying back stock. Trading bottom range of multiples any time of the past 4 decades. Dividend + buyback alone gets double digit returns. I expect multiple expansion at some point.
Not advice.