

- Momentum/Value stock picking strategy - Buy "out of favour", sell "animal-spirits" - Ex Management Consultant - $APPS expert
Aldebaran, Taurus
Joined March 2023
- Tweets2.7K
- Following172
- Followers213
- Likes666




$APPS "...provides us ample opportunities to reduce our cost of capital..."
Does the CEO mean they found a lender with rates <9.5% before 12/32? I think so

1
4
229
$APPS it looks like we're just caught in a market downtrend since beginning of October
3
183


$APPS Strategy: Sacrificing short-term gross margins on perform. ads to fuel volume + train ML models, then expand take rates. Classic ad-tech data flywheel (Meta playbook). More data > better predictions > higher advertiser ROI. Once models mature, massive operating leverage
3
164
$APPS must refinance ~$385M by 12/31/26 to avoid $5M fee + tighter liquidity covenant. Current ~11.6% rate (expensive). Realistic new deal: 8.5-9.5%. Saves $9.5-11.4M/yr interest → +$0.08-0.10 EPS. Big catalyst coming.
1
7
220
$APPS People are misunderstanding the Earnings Report. Core Business (Singletap+Brand ads) came in at $166m/$42.5m EBTDA. Ramping performance ads +$12m QoQ, at negative margins.
(1/2)

1
1
334
$APPS APPS has a healthy existing business and is adding a lower-margin but rapidly growing advertising business that can become more profitable with scale.
Performance ads doesn't need to achieve the same margin -> it just improve its incremental contribution as it scales

2
112
$APPS Margins didn't actually disappoint. Last Q EBITDA margin was exceptionally high. EBITDA Margins have been volatile around 20% since turnaround. At the beginning of FY26 they guided 21-23% EBITDA margin for the year. Nothing has changed. New CFO Lentz gonna work on margins

1
7
798
$APPS I can see $8.28+ as max downside. Don't count in today's rally, that would be -21% from yesterday.
Will break $15+ if it beats, and update guidance $20m+
3
3
1,299
$APPS 3 quick things they have to beat:
revenue >$174M
FCF > 0
Guidance at least the same
1
1
608
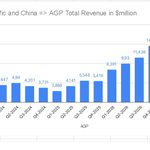
$APPS DT AGP has been growing at a rate of 26% quarter-over-quarter in APAC for the past 8 quarters. At this pace, that would amount to $200 million in 10 quarters. And you might think I’m crazy, but I consider that practically a done deal.

1
8
576
$APPS guess who's doing the monetization for them. Let U and APP focus on gaming. Microdramas growing at 67% this year, imo proxy for AGP.
global.chinadaily.com.cn/a/2…

4
557
$APPS just as reminder that EU DMA not only includes mobile apps, but also "virtual assistants" - so google can't just block out every competing ai agent from the phone. That's the loophole for DT in a post-apps world.

3
651
$APPS I remember June 2025, when CFO Steve Lasher started and pushed the earnings release back by two weeks to June 16th - in the grand scheme of things, did that lead to poor results or change anything about the company?
2
1
852

$APPS expanding into lock screens, e-commerce & more. DT’s edge in AGP: exclusive phone inventory you can’t bid on in the open market - fully protected from AppLovin & Meta. Lock screens = pure brand power. Coca-Cola when you’re thirsty or at the checkout . Underrated.

5
510