

Stocks, options, plus company/AI theme focused research | Sharing personal portfolio updates regularly | Not Financial Advice
Ontario, Canada
Joined May 2026
- Tweets270
- Following205
- Followers78
- Likes953



Pinned Tweet
Here are my updated portfolios positions. Will be updating them regularly as best as I can. Most put sales are cash secured.
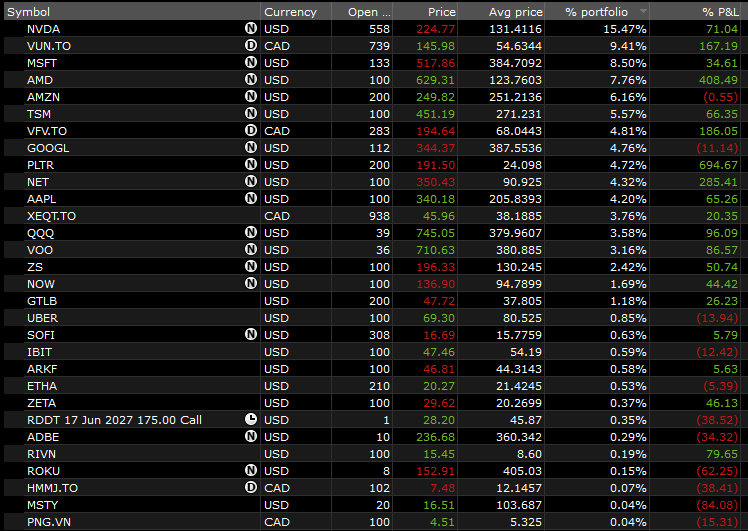
ALT Long Term

ALT Options
MS: Growth in global power demand is much broader than Al. Industry is the largest driver, while cooling alone adds more electricity demand than data center growth through 2030. As grid power gets more constrained, we estimate behind-the-meter power demand will grow to 8GW in Asia and 47GW in the US by 2030 as grid.


MS: Asia has one of the fastest AI adoption curves globally, making the case for more hyperscaler investment in Asia, while also helping resolve US power constraints

BofA $AMZN 3Q Preview: Reports 10/29; we estimate rev/EBIT at $202.0 bn/$26.4 bn vs Street at $202.2 bn/$26.1bn. We estimate AWS growth of 40% y/y above Street at 38%, and we expect upside to our estimates
(+$4bn q/q rev. growth) driven by new capacity, YTD price increases, ramp of Al Lab contracts, and growing enterprise inference demand. We expect stable AWS margins at 39% in 3Q as higher depr. is offset by strong utilization, growing Trainium workloads, Bedrock growth, and fee increases. The key risk is high expectations (possibly at 42%+), but results should suggest strong ROI on capacity capex.
SPCapital retweeted

Depreciation and amortization expenses for the five hyperscalers are set to reach $590 billion in 2029. This is likely to exceed their combined operating profits in 2026.

Two AI chipmakers make up 34% of America’s earnings boom. Ten companies—including Nvidia, Micron and other AI giants—account for roughly two-thirds of corporate profit growth - WSJ

SPCapital retweeted

🇨🇦 Housing Market | Sep 2026
🔹 Benchmark: $651,400 (-3.4% YoY, -0.9% MoM)
🔹 Avg: $666,538 (-1.6% YoY, -0.3% MoM)
🔹 Sales: 36,842 (-7.5% YoY, -2.3% MoM)
📉 Benchmark: B.C. -4.7% & Ontario -3.9% YoY
📈 Outside B.C. & Ontario, every province’s avg price rose annually
❄️ Alberta and Quebec are cooling off
👉 More: wowa.ca/reports/canada-housi…
YoY: Year-over-Year | MoM: Month-over-Month
------------------------
Provided by WOWA.ca
Simply Know Your Options🔍

Mizuho on $GOOGL: We are positive on GOOGL into 3Q results, with upside in Cloud segment from TPUs offsetting any risk around Search. For 3Q26, we model Cloud revenue of $33B vs Street of $29B, or growth of ~120% Y/Y, above consensus at ~90%, driven by TPU revenue. For search, we forecast revs of $64B vs Street of $65B, or growth of 13% vs Street of 15%. Our concern is not structural but analytical - consensus calling for very limited deceleration into tougher comps.


BofA on $SPCX: SPCX guided 4Q26 capex to $35-40 bn and expects compute to grow from 1.7GW 3Q26 to 2.5-3GW by YE26. Management is "highly confident" of adding 10GW in CY27, mostly Vera Rubin, would be surprised below 13GW, and sees "non-zero" chance of more than 20GW. That implies $400-800 bn+ of potentiall Vera Rubin spend vs. $72 bn of pre-call CY27 consensus capex, though customer-supplied XPUs mean not all of the GW is incremental $NVDA sales. SPCX's pricing is just above $50/W, payback is under a year, ~200-220K GB300s are activated per month, and demand could absorb compute "several times over."
Here is how large-cap Technology sector stocks have performed YTD. Image captured from @finviz_com free tool as shared by @MarketMike here - xitter.cf/MarketMike/status/2112…


Anthropic S-1 Shows Red-Hot Growth, Risks and Massive Computing Costs
wsj.com/tech/ai/anthropic-re…


Evercore: One of the most encouraging developments in companies this earnings season was the acceleration in incremental ARR revenues for the CSPs, as well and increasing incremental EBIT margins, suggesting that these companies are starting are starting to see real returns on their Al CapEx. $AMZN, $MSFT, $GOOGL
