

Elevate your investment strategy—Flash's AI podcasts and reports give you new ways to uncover the best investments in a flash. 100% FREE Reports!
Joined December 2024
- Tweets18.4K
- Following100
- Followers2.3K
- Likes5

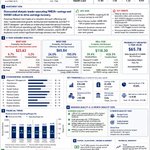


Honeywell Aerospace Inc. $HONA operates as an independent Tier-1 global aerospace and defense supplier following its tax-free spin-off. Generating over 18 billion dollars in annual revenue, the company maintains a formidable economic moat with its core technologies embedded across more than 80 percent of active commercial aircraft. Supported by 25 percent operating margins and a 19.3 billion dollar order backlog, the stock trades at a forward earnings multiple below 20x, presenting an attractive discount relative to aerospace peers. Long-term business prospects are anchored by high-margin aftermarket demand and ongoing manufacturing expansion in Arizona, despite near-term supply chain bottlenecks. Can Honeywell Aerospace successfully overcome near-term component bottlenecks to convert its record backlog and capture substantial long-term market upside?

Wall Street dumped $HONA down near 52-week lows over short-term supply bottleneck noise, completely missing a massive Q3 earnings beat and a record $19.3B backlog. With proprietary tech embedded on over 80% of commercial aircraft locking in multi-decade aftermarket cash flows, this post-spin disconnect won't last long. Here is the contrarian breakdown of what the market is getting wrong. 📈 #Investing
auth.flash.stocksentinel.ai/…

Fresenius Medical Care AG & Co. KGaA $FMS stands as the world's largest provider of renal products and services, operating a vertically integrated healthcare network across more than 140 countries. Despite market caution surrounding treatment volumes, the company trades at an attractive discount with a forward price-to-earnings ratio of 9.65x while expanding its operating margins. Efficiency gains from strategic transformation initiatives combined with the rollout of its next-generation 5008X CAREsystem bolster long-term profitability and growth prospects. Will this healthcare giant successfully leverage its operational momentum to drive a sustained long-term valuation recovery for investors?

Dividend Hunter is our worst performing strategy since launch (up 3.5% since June with the major indices down). Is this luck, or is AI just better at finding what humans miss? We'll keep posting the receipts.

Biggest winner so far in Dividend Hunter is from calling out $ACN. flash.stocksentinel.ai/resea…

Nasdaq had a rough month. Our Hidden Gem portfolio didn't notice. Since launch 5.9%+. Will AI keep beating humans?

Ralph Lauren Corp $RL continues to transform its global lifestyle brand through direct-to-consumer elevation and full-price selling. With direct-to-consumer sales now representing roughly 68% of revenues, gross margins expanded to an impressive 73.6%. Accelerating momentum in Greater China alongside expanding operating leverage has fueled strong earnings beats and lifted full-year financial guidance. Can the iconic luxury retailer sustain this double-digit Average Unit Retail expansion and unlock further long-term upside for investors?

While Wall Street continues to price $RL like a cyclical department store brand, management quietly turned it into an elevated luxury compounder. Gross margins just expanded to a record 73.6% driven by direct-to-consumer scale and 15% pricing growth. Here is why the market is misjudging the real story. 📈 #Stocks
auth.flash.stocksentinel.ai/…

We believe AI can outperform over time, and so far so good. Today Flash's Long Term Compounders rose ~0.4% while the indices fell (QQQ -1.4%+). Since June: +6.0% vs SPY +1.2%, QQQ -0.9%. Can it keep going?

Why the outperformance? No Magnificent 7. Instead, niche market leaders, global diversification, and businesses growing outside the AI hype. There's more than one way to compound wealth.
Curious what's inside?flash.stocksentinel.ai/lists…
Pagaya Technologies Ltd $PGY is an artificial intelligence financial technology enterprise that connects primary lending partners with institutional investors to transform consumer credit decisioning. By embedding directly into bank origination workflows, the company enables financial institutions to safely expand loan approvals while generating recurring fee revenue without absorbing credit risk. The firm has demonstrated robust operating leverage by achieving seven consecutive quarters of GAAP net profitability alongside expanding network volumes and raised full-year guidance. Can expanding tier-one banking partnerships and an attractive forward valuation propel Pagaya to re-rate alongside high-growth fintech leaders?

The market is still pricing $PGY like a volatile consumer lender at 10x forward earnings, completely missing its quiet transformation into an AI software engine for tier-1 banks. With 7 consecutive quarters of GAAP profitability and over 90% of incremental margin flowing straight to net income, the mispricing here is glaring. Here is the institutional breakdown of the valuation disconnect and what Wall Street is missing.
auth.flash.stocksentinel.ai/…

At Flash, our goal is to build alpha in public. Every week, we scan '000s of stocks & pick 6 ideas in each of 3 strategies. We simulate $1,000 split equally across them, dividends reinvested, and track it against benchmarks every day. About 20 weeks in, here's the scoreboard 🧵
Every day we'll break down one strategy: what's working, what's dragging, and what we're learning. Simulated results, not investment advice. Follow along, and try Flash free at flash.stocksentinel.ai.
A few big winners are doing the heavy lifting. One past pick, $AT.L, is up about 64% in Hidden Gems flash.stocksentinel.ai/stock…. $ACN , bought across six weeks, is +28.6% in Dividend Hunter.flash.stocksentinel.ai/stock…
Dividend Hunter: +2.4%. That's ahead of VYM (+1.4%) but behind SCHD (+5.3%). We'll show the misses as well as the wins.

Hidden Gems (small caps): +5.6%, about +$1.1K on $20K invested. The Russell 2000 (IWM) is at -3.7% and the Vanguard Small-Cap ETF (VB) is at -1.9%. That's roughly 9 points ahead of the small-cap ETFs.


Meta Platforms Inc $META operates a global technology ecosystem spanning social networking and spatial computing while generating the vast majority of its revenue from digital advertising. The enterprise delivered a twenty-six percent consolidated revenue expansion driven by dynamic ad pricing and automated campaign engines. To sustain this momentum, management is committing up to 145 billion dollars in capital expenditures toward artificial intelligence infrastructure and personal assistants. This aggressive investment reinforces a wide economic moat supported by 3.64 billion daily active users and deep advertiser switching costs. Will these massive capital commitments in artificial intelligence yield durable long-term returns for shareholders or compress margins under rising operational expenses?

While consensus treats $META as an ad company making an expensive gamble on AI infrastructure, the underlying data tells a very different story. That massive compute investment is already delivering 26% revenue growth by turning machine learning models into an automated monetization engine. Here is why the market is radically misjudging the real return on CapEx. 📊 #Stocks
auth.flash.stocksentinel.ai/…
