

SEBI RIA No INA000007881| MissioN SMILE | Stock SIP| Stock Advisory| Premium Offerings: https://teapaw.org/t.co/xhGNuQIbSV
Ahmedabad/ Bangalore/Mumbai
Joined May 2016
- Tweets27.4K
- Following710
- Followers48.3K
- Likes29.5K





Pinned Tweet
India’s next big power story isn’t solar
it’s NUCLEAR ⚛️
We’re entering a multi-decade capex cycle — and almost no one is talking about it yet.
🇮🇳 100 GW target by 2047 (vs ~8 GW today)
💰 ~₹19 lakh crore investment opportunity
⚡ AI + EVs = 24x7 baseload demand
Renewables are growing fast — but they’re intermittent.
Nuclear = low carbon + reliable + scalable
And now, the real inflection 👇
* SHANTI Act 2025 → private sector entry
* Liability reforms → supplier ecosystem unlock
* SMR push + ₹20,000 Cr allocation
* Execution pipeline finally building up
This is a high-entry-barrier sector
→ 7+ year approvals
→ Limited qualified vendors
→ Deep, durable moats
Which means:
The real winners may be a handful of suppliers most investors aren’t tracking.
From EPC to critical components —
this is a full ecosystem play.
We’ve decoded it all:
Value chain. Policy shift. Key beneficiaries. Risks.
👉 Full 38-page detailed report covering value chain, players & risks:
missionsmile.smartsyncservic…


🪔 DIWALI SPECIAL OFFER | SMART SYNC SERVICES 🪔
Dear Investor,
Greetings from Smart Sync Services!
This Diwali, take a step towards a more informed and research-driven investment journey with our Exclusive Diwali Offer on Investment Advisory Services.
At Smart Sync Services, our investment philosophy is centred around identifying and understanding businesses through in-depth fundamental research, financial analysis, industry evaluation, management interactions and continuous monitoring.
We aim to bring a disciplined and research-oriented approach to investment decision-making.
1. FLEXI-CAP ADVISORY SERVICE
A research-driven advisory service designed to identify investment opportunities across market capitalisations and diverse sectors.
Key Features:
✓ A diversified basket of approximately 20–25 stocks across different market capitalisations and sectors.
✓ Typically 3–5% allocation per stock, subject to portfolio considerations.
✓ Quarterly portfolio updates.
✓ Detailed conference call (con-call) analysis covering company performance, management commentary and business outlook.
✓ Fundamental research and financial analysis for stock selection.
✓ Continuous tracking of portfolio companies and relevant business developments.
✨ DIWALI SPECIAL PRICING
🔹 1-Year Subscription:
₹24,000 → ₹20,400 + GST (15% OFF)
🔗 Subscribe for 1 Year:
rzp.io/rzp/0TQe72On
🔹 6-Month Subscription:
₹12,000 → ₹10,800 + GST (10% OFF)
🔗 Subscribe for 6 Months:
rzp.io/rzp/6adBtdiE
💎 2. HNI ADVISORY SERVICE
An exclusive advisory offering for investors seeking a more focused and personalised approach to equity investing, with research coverage across select micro-cap and small-cap companies.
Key Features:
✓ Focused portfolio of selected investment opportunities.
✓ Research coverage across select micro-cap and small-cap companies.
✓ In-depth fundamental research and detailed financial analysis.
✓ Evaluation of business models, competitive positioning and industry dynamics.
✓ Management interactions and detailed con-call analysis.
✓ Personalised advisory support and periodic portfolio reviews.
✓ Investment recommendations aligned with the client's risk profile and investment objectives.
✓ Focus on disciplined, research-driven and long-term investment decision-making.
✨ DIWALI SPECIAL PRICING
🔹 1-Year Subscription:
₹48,000 → ₹40,800 + GST (15% OFF)
🔗 Subscribe for 1 Year:
rzp.io/rzp/XdtDxU5U
🔹 6-Month Subscription:
₹24,000 → ₹21,600 + GST (10% OFF)
🔗 Subscribe for 6 Months:
rzp.io/rzp/NiansAnN
🔍 A GLIMPSE INTO OUR FUNDAMENTAL RESEARCH COVERAGE
At Smart Sync Services, our research process involves understanding businesses beyond headline financial numbers.
Our analysis focuses on business fundamentals, competitive positioning, management quality, financial performance, industry dynamics, growth opportunities and potential business risks.
Some of the companies covered through our fundamental research include:
1. Steel Strips Wheels Ltd.
Automotive components | Wheels and steel wheel manufacturing
🔗 Read our Research update:
teapaw.org/SmartSyncServ/status/2…
2. Gabriel India Ltd.
Auto components | Suspension and ride-control systems
🔗 Read our research update:
teapaw.org/SmartSyncServ/status/1…
3. Uniparts India Ltd.
Engineering components | Off-highway equipment and precision engineering
🔗 Read our HNI portfolio update:
teapaw.org/i/status/2062101439129…
4. Fineotex Chemical Ltd.
Specialty chemicals | Textile auxiliaries and performance chemicals
🔗 Read our HNI portfolio update:
teapaw.org/i/status/2061710449889…
Our research approach incorporates:
✓ Detailed fundamental and financial analysis.
✓ Understanding business models and competitive advantages.
✓ Industry and sector-level research.
✓ Management commentary and conference call analysis.
✓ Continuous monitoring of business developments and financial performance.
Our objective is to develop a deeper understanding of businesses and identify investment opportunities through a structured and disciplined research process.
🪔 MAKE THIS DIWALI A STEP TOWARDS A MORE INFORMED INVESTMENT JOURNEY!
Whether you are looking for a diversified Flexi-Cap Advisory Service or a more focused HNI Advisory Service, Smart Sync Services aims to support your investment journey through independent, research-driven investment advice.
To understand the services, subscription details and suitability, connect with our team.
📞 CONNECT WITH US | CALL / WHATSAPP
+91 90999 56002
+91 70166 59985
Warm regards,
Himanshu Shah, CFA, CA
Partner & CIO
Akhilesh Pathak, NITD, IIMA
Co-founder & Managing Partner
SMART SYNC SERVICES
SEBI Registered Investment Adviser
Registration No.: INA000007881
DISCLAIMER:
Registration granted by SEBI, membership of BASL and certification from NISM in no way guarantee performance of the IA or provide any assurance of returns to investors.
Investment advice is provided after considering applicable client suitability requirements, risk profiling and investment objectives. Advisory services are subject to applicable SEBI regulations and terms of engagement.

When we recommended Fineotex to our HNI clients nearly a year ago (≈₹24), the company faced headwinds.
Trusting the wisdom of Stanley Druckenmiller & the conviction of our partner @akhileshnpathak, we held our stance.
Last quarter’s results validated that call, reaffirming our disciplined, research-driven approach.
( Druckenmiller, who compounded 30% CAGR over 30 years without a single losing year, has a thesis that you must never invest in the present. Strip away current financials and ask yourself, "Where will this business be, and what will its environment look like, 18 to 24 months from now?")
SEBI Disclosure: Our partners and advisory clients hold positions acquired at lower price levels. We also recommended the stock to new HNI clients during the March 2026 dip.


Shubh and Happy Deepawali to you and your family !
May the Divine Light ignite the light within and brighten our lives with joy, abundance and well being.
Warm festive wishes,
Team Smart Sync Services.

🪔 Happy Dhanteras! ✨
This Dhanteras, may prosperity grow, opportunities multiply, and every financial decision bring you closer to lasting wealth and success.
Wishing you and your family good health, happiness, and financial well-being.
Warm wishes from Smart Sync Services.
🤖 Made with AI

Brahmaputra Infrastructure: The next growth phase depends on execution, not just order wins.
Brahmaputra Infrastructure’s Q2 numbers look encouraging. Revenue grew 31% YoY to ₹118 crore and PAT rose 37% to ₹20 crore. Its order book has also reached nearly ₹2,000 crore, up from ₹1,600 crore in just six months.
The bigger opportunity lies ahead. Nearly 50% of the order book is still in the design phase and is expected to move into execution in H2. Management sees stronger Q3 and Q4, with ₹900 crore of projects executable over the next 18 months. It is targeting ₹1,200 crore in fresh orders this year and an order book of ₹2,500 crore by FY28.
The balance sheet is showing some improvement too. Finance costs fell 31% QoQ, term loans reduced to ₹12 crore, and arbitration recoveries are providing additional support.
The real test now is execution. Can Brahmaputra convert its growing order book into revenue while maintaining margins and controlling working capital? The next few quarters should offer a clearer picture.

GNG Electronics: The AI Boom Is Creating an Unexpected Opportunity in Refurbished Laptops.
AI is driving up memory and storage costs, making new laptops far more expensive. Management says models that once cost ₹35,000–40,000 now sell for around ₹65,000–72,000—making refurbished laptops more attractive.
That’s creating an opportunity for GNG Electronics. The company reported about 30% volume growth and an 11% improvement in H1 realisations. It has also raised its FY27 revenue growth guidance to 40% and its PAT margin expansion target to 150 bps over FY26.
The near-term boost may last through FY27–28, while memory supply remains tight. The bigger test is whether GNG can build a trusted refurbished-electronics business that keeps growing after prices settle.


Hariom Pipe Industries: The Plant Restart Was Just the Beginning.
Sometimes, the biggest growth trigger for a manufacturing company is getting its existing capacity back on track. That's exactly what happened with Hariom Pipe Industries after its Perundurai plant resumed operations on 13 July.
Q2 FY27 revenue jumped 65% YoY to ₹554 crore, while sales volume reached 83,170 tonnes, up 32% QoQ. But the more interesting part is profitability. Core EBITDA grew 58% to ₹68 crore, with margins improving to 12.21%. Better capacity utilisation, higher-value products and lower power consumption per tonne helped drive the improvement.
So, what's the next growth trigger?
Hariom is now looking beyond volume growth. Its backward integration plans, including an HR coil plant in Maharashtra, are aimed at improving cost efficiency and taking EBITDA margins towards 13–15% over time. The company is also expanding its solar business, targeting 52 MW of capacity across 11 locations by January 2027. Management expects this to become an additional revenue and earnings contributor as projects scale up.
Management expects 10–15% revenue growth in H2 FY27 and is targeting similar growth in FY28. However, the real test will be whether Hariom can sustain its improved margins while executing its expansion plans. The key monitorables are the HR coil project, backward integration timeline, volume growth, solar commissioning and power-cost trends.
🤖 Made with AI

India wants to become a global EV and battery manufacturing hub. But there's one big missing piece: Critical Mineral Processing.
India may secure access to lithium and nickel, but without domestic processing capabilities, a significant part of the value chain remains dependent on overseas suppliers.
The government is now trying to change that.
The Union Cabinet has approved a ₹2,814 crore capital support scheme to build domestic lithium and nickel processing capacity over the next five years (FY27–FY31).
What's actually changing?
The scheme will support four processing plants:
- 2 Lithium plants with minimum capacity of 30,000 tonnes each.
- 2 Nickel plants with minimum capacity of 50,000 tonnes each.
Eligible projects will receive a 30% capital subsidy, subject to maximum support of ₹500 crore per lithium beneficiary and ₹900 crore per nickel beneficiary.
Who stands to benefit?
The impact could extend across multiple industries:
- EV manufacturers: Better domestic access to processed battery materials.
- Battery manufacturers and BESS players: Potentially stronger domestic sourcing of critical inputs.
- Specialty steel and electronics: Improved access to strategically important materials.
- Domestic mineral processors: Financial support to build capital-intensive processing facilities.
There's another important angle: Cobalt is also expected to be recovered as a by-product of nickel processing, adding another strategic material to the domestic supply chain.
How soon will the opportunity materialise?
The scheme runs from FY27 to FY31. However, this is not an overnight capacity addition. Beneficiary selection, plant construction, technology availability and commercial commissioning will determine how quickly domestic production scales.
The bigger picture: India is trying to capture more value within its own borders - moving from dependence on imported refined materials towards domestic processing.
For investors, the opportunity is worth tracking across the critical minerals, battery materials and processing ecosystem.
The real question: Who will emerge as India's domestic lithium and nickel processing leaders?


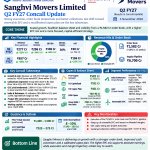
Sanghvi Movers Ltd. | Q2 FY27 Concall Takeaways
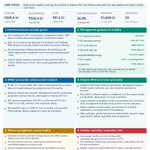
1. Strong Business Momentum: Revenue grew 32% YoY to ₹277 crore and EBITDA increased 20% to ₹106 crore. Order book surged 26% in just 13 weeks to ₹1,582 crore.
2. Changing Business Mix & Guidance: Management now expects FY27 revenue mix of 60% from crane rentals and 40% from renewable EPC. FY27 guidance remains unchanged at ₹1,400–1,500 crore income and ₹525–575 crore EBITDA.
3. Execution & Expansion Monitorables: ₹80–90 crore of Saudi Arabia capex has been deferred to FY28 due to shipping disruptions, while 8–10% of the order book may spill over. Key monitorables include EPC execution, crane utilisation, order book conversion and cash collections.

Parag Milk Foods | Q2 FY27: Mix, capacity expansion & milk cost dynamics
- Product Mix Driving Growth: Despite two rounds of price hikes and elevated milk costs, volumes grew 12%. New-age brands grew 71%, while value-added products now contribute ~75% of revenue, supporting margin resilience.
- Capacity Expansion – Next Growth Driver: Parag plans to expand paneer capacity 4x to 80 MT/day by June 2027 and double cheese capacity to 120 MT/day by Q2 FY28, strengthening its presence in higher-value dairy products.
- Milk Costs – Key Monitorable: Milk procurement costs remain elevated, with no meaningful near-term relief expected. Sustaining margins will depend on pricing discipline, premium product mix and the ability to pass on input cost inflation.
Swipe for the detailed analysis.


Deep Industries Ltd. | Key Takeaways from Q2 FY27 Concall
- Structural Industry Opportunity: Rising demand for artificial gas-lift solutions, ageing oil & gas infrastructure and India's focus on domestic energy security are creating long-term opportunities for outsourced gas compression and oilfield services.
- ONGC PEC & Growth Visibility: The ONGC production enhancement contract is expected to drive incremental production-linked revenues from Q3, with workover activities resuming and production ramp-up targeted by Q4 FY27.
- Expansion & Offshore Opportunities: Management plans significant capex towards PEC execution, while Dolphin Offshore's operational readiness provides additional growth optionality. However, further offshore investments remain conditional on securing firm contracts.

IOL Chemicals & Pharmaceuticals | Key Takeaways from Q2 FY27 Concall
- Business Diversification: Non-ibuprofen APIs are gaining traction, while backward integration in ibuprofen and expansion into formulations are expected to strengthen the company's API business and improve value addition.
₹500 Cr Capex Programme: Major investments in ibuprofen capacity, formulation CDMO and specialty chemicals are aimed at expanding manufacturing capabilities and driving export-led growth over the coming years.
Growth Outlook & Monitorables: Management expects H2 performance to remain broadly similar to H1. Key monitorables include capex execution, CDMO customer approvals, utilisation ramp-up and working capital discipline.

Paradeep Phosphates Ltd. | Q2 FY27 Concall Takeaways
- Revenue grew 7.2% YoY to ₹7,364 crore, but EBITDA fell 38% to ₹431 crore and PAT declined 64% to ₹122 crore. H1 revenue rose 18.6% to ₹13,488 crore, while EBITDA fell 10.7% to ₹1,173 crore and PAT declined 22% to ₹514 crore.
- Policy-driven demand shifted toward DAP, priced at ₹1,350 versus ₹2,000+ for NPK grades. Management described this as tactical, with its long-term focus remaining on balanced nutrition. H1 sales volume was about 2.0 million tons, down 12.9%; Q2 EBITDA per ton was ₹4,250, with H2 guidance of ₹4,500–₹5,000.
Key monitorables are NBS and sulphur subsidy timing, elevated subsidy receivables and borrowings, inventory liquidation through the Rabi season, product-mix and margin recovery, and execution of the phosphoric-acid integration and capacity expansion projects.
🤖 Made with AI

EFC Ltd. | Q2 FY27 Concall Takeaways
- Revenue grew 30% YoY to ₹332 crore, led by strong performance across leasing (+30%), Design & Build (+16%) and furniture (+149%). Occupancy remained above 90%, while the Design & Build order book exceeded ₹300 crore, providing visibility for H2 FY27.
- Management expects Design & Build revenue to grow 50–60% in FY27, with leasing occupancy maintained above 90%. The company is also expanding its furniture manufacturing and external B2B business, moving towards an integrated workspace solutions platform.
The key monitorables are Design & Build order execution, segment-level margin sustainability, working capital cycle, cash conversion and integration of the Ultrafresh acquisition.
🤖 Made with AI
