

Dev Ashish, Founder https://xitter.cf/t.co/UjEvJiQg2Q | SEBI RIA No. INA100005241 | Fee-Only Investment Advisory & Financial Planning | Services - https://xitter.cf/t.co/RlTHDRWbl8
India
Joined October 2012
- Tweets25.8K
- Following218
- Followers66.7K
- Likes8.7K



Pinned Tweet
I am a SEBI Registered Fee-Only Investment Advisor (RIA). Details of the advisory services below:
Financial Planning:
bit.ly/StableFinancialPlanni…
HNI Portfolio Advisory:
bit.ly/StableHNIAdvisory
Use the forms in these pages to contact for advisory/planning services


Stable Investor retweeted
LTCG Taxation is in the news again. And the reason is that our finance minister has said the government is open to feedback on capital gains taxation.
I am no one, but I have feedback on it too. 😊
While personally, I would love to see pre-2018 taxation where LTCG was taxed at 0%, I am still fine if Long-Term Capital Gains tax on Equities is removed (or at least reduced*) and the holding period for LTCG qualification is increased to 3 years. It kind of aligns with what equities as an asset class demands - staying invested for the long term for best results.
My point is simple. If the aim is to promote long-term behaviour, give incentives like bringing LTCG down to 0% and redefining long-term for equities as 3 years.
*Scrapping the long-term capital gains tax on equities may be difficult for the govt. as LTCG tax on equities brings in decent revenues and, in all fairness, no government would want to give that up easily. So rather than full elimination, reducing it to a small percentage of say 1-5% (from the current 12.5%) may also send the right message.
Another option might be to make a tiered approach where LTCG tax from 1-3 years is 10%, and for holding periods above 3 years, it is removed completely (0%). But this will again make things complex, though desirable and better than what we have today.
Demands to remove LTCG come up every now and then. But the direction so far has been one way only: 0% before 2018, 10% from 2018 to 2024, 12.5% since. Let’s see what comes out of this episode of Bring-LTCG-Down-To-Zero.
But I really hope our govt. does something so that we can forget those infamous lines - Capital gains don't accrue from any effort (iykyk), and someone finally thinks about rewarding long-term investors by rationalizing/reducing LTCG taxes, if not eliminating them fully.

Stable Investor retweeted
A lot of people are highlighting how equity markets have done poorly compared to even Fixed Deposits giving 6-8% annual returns. And while they are right when it comes to the data, it is also not the best way to look at things when you have come to equity markets for the long term.
It is true that Indian equity markets have done poorly for the last couple of years. The mood is no doubt terrible, more so for new investors who are going through this pain for the first time.
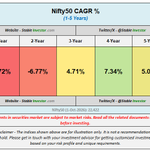
Look at the table which shows how the last 1/2/3 years' Nifty50 returns are -9.7%, -6.8% and 4.7%, respectively. And boring Fixed deposits, on the other hand, have quietly done much better. Put the two side by side today, and the FD looks like the smarter choice. But this is just a present day snapshot. And it is taken at the most uncomfortable point.
Measured from a market peak, and especially mid-drawdown, an FD will often look better than equities. Sometimes for longer than feels reasonable (like today when 1/2/3 year returns of equity vs FD strangely show FD winning vs equities). Investors who made this comparison during past falls reached the same conclusion. The FD was ‘winning’ back then also. But run it after the recovery that followed, and the conclusion flipped. Which one is right depends on the return you actually realise over a full horizon, not on how the market has behaved in the last two years.
You can’t benefit from long-term investing if you can’t accept that long term is made up of ‘good’ short terms as well as ‘bad’ short terms. History and maths support this, even if it may not seem obvious right now. But keeping the faith during the dark moments of equity markets is what benefits you the most when the tide turns. It is not easy I know. But it is simple and what works. History shows recoveries have followed past drawdowns. It does not tell you when this one ends.
The costly mistake is treating a mid-drawdown scoreboard as a reason to act. Stopping the SIP, or exiting because the FD currently looks ahead, converts a paper loss into a permanent one. In most such episodes, that is what separated investors who eventually came out ahead from those who locked in the worst of the fall.
This is not an argument that the ongoing brutal phase of the markets is over or that equities would bounce next week or next month or next quarter. They may. They may not. The useful question here is - Are you judging a long-term allocation on a comparison that looks decisive only because you stopped the clock at the painful moment? If yes, the FD is not winning. You are just looking too early.
Now to be fair, adding money when markets are falling feels deeply uncomfortable, and almost irrational, if not scary. You will always wonder what if markets fall a little more? And if they fall another 5-10% after you have invested, that pain aggravates enormously. Remember, markets don’t do what you want them to do on your demand. But from whatever experience I have in markets, it pays to stay calm and remain objective. It helps to believe that Remember God in Good Times & Equities in Bad Times, and that Cash + Courage + Crisis makes real Wealth. Easier said than done, but that is how it is.
Equity investing should be done for the long term only. And in the long term, there will always be short phases when the markets will be volatile and give negative returns. This is completely normal, and you should accept it.
So if your goals are long-term and still several years away, then ideally you should be investing more as markets fall. Or you can stagger your surplus over a few months for better peace of mind. You can even rebalance your existing portfolio if you don’t have fresh surplus to invest. Instead of fearing a falling market, view it as an opportunity to invest at lower levels so that your future profits increase. A consolidating or falling market is not a disappointment. Rather, it is a market that is quietly doing the most important work for investors: rebalancing the risk-reward equation back in favour of them. So it is precisely the setup that resilient long-term investors should welcome!

Stable Investor retweeted

Human being is a depreciating assets- after u cross 40 yrs of age.
In your balance sheet, you may increase the value of cash and stocks.
But, the most important asset- your body- itself is depreciating every year.
The total value is going down every year- no matter- what you do!
Stable Investor retweeted
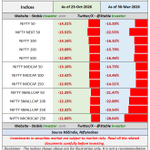
How Much Have Markets Fallen from All-Time-Highs?
23-Oct-2026 (Now) vs 30-March-2026
The table compares the fall % from respective All-Time-Highs (intraday) for major indices on the above-mentioned two dates. The latter date being approx when Indian markets made the most recent bottom.
Note - Investments in the securities market are subject to market risks. Read all the related documents carefully before investing.
Disclaimer - The indices shown are for illustration only. It is not a recommendation to buy/sell/hold. Please get in touch with your investment advisor to get customised investment advice based on your risk profile and unique requirements.

There have been way too many stock market related podcasts and episodes in recent months. Some are good but a vast majority aren’t. I am sure soon podcasters will start running out of guests to bring to their podcasts.
PS - I rarely listen to podcasts but this is the trend I see these days.
How Much Have Markets Fallen from All-Time-Highs?
23-Oct-2026 (Now) vs 30-March-2026
The table compares the fall % from respective All-Time-Highs (intraday) for major indices on the above-mentioned two dates. The latter date being approx when Indian markets made the most recent bottom.
Note - Investments in the securities market are subject to market risks. Read all the related documents carefully before investing.
Disclaimer - The indices shown are for illustration only. It is not a recommendation to buy/sell/hold. Please get in touch with your investment advisor to get customised investment advice based on your risk profile and unique requirements.
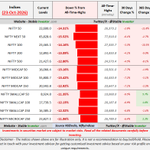
Current State of Indian Markets (23-Oct-2026)
The table shows the % Fall of Indices (closing values) from their respective All-Time-Highs (intraday).
Note - Investments in the securities market are subject to market risks. Read all the related documents carefully before investing.
Disclaimer - The indices shown are for illustration only. It is not a recommendation to buy/sell/hold. Please get in touch with your investment advisor to get customised investment advice based on your risk profile and unique requirements.

Stable Investor retweeted
Current State of Indian Markets (21-Oct-2026)
The table shows the % Fall of Indices (closing values) from their respective All-Time-Highs (intraday).
Note - Investments in the securities market are subject to market risks. Read all the related documents carefully before investing.
Disclaimer - The indices shown are for illustration only. It is not a recommendation to buy/sell/hold. Please get in touch with your investment advisor to get customised investment advice based on your risk profile and unique requirements.

Pain leaves once it’s done teaching you. Or maybe it just doesn’t get easier. You just get stronger.
Current State of Indian Markets (21-Oct-2026)
The table shows the % Fall of Indices (closing values) from their respective All-Time-Highs (intraday).
Note - Investments in the securities market are subject to market risks. Read all the related documents carefully before investing.
Disclaimer - The indices shown are for illustration only. It is not a recommendation to buy/sell/hold. Please get in touch with your investment advisor to get customised investment advice based on your risk profile and unique requirements.
Stable Investor retweeted
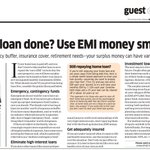
If your home loan is complete and you don’t want to take another loan again and repeat the Earn-EMI cycle (to purchase the next property), then what should you do next? You now have surplus money left over each month, as there is no home loan to service EMIs.
So how best to use that extra/surplus money now?
I wrote about this in my latest column in Economic Times Wealth @ET_Wealth - 19Oct2026 edition.

Nifty50 is down -13.4% for the year 2026 (YTD). Still about 10 weeks for the index to try to recover and extend the 10-year streak of positive returns.
Note - The investments in the securities market are subject to market risks. Read all the related documents carefully before investing.
Disclaimer - The indices shown above are for illustration only. It is not a recommendation to buy/sell/hold. Please get in touch with your investment advisor for customised investment advice based on your risk profile and unique requirements.

LTCG Taxation is in the news again. And the reason is that our finance minister has said the government is open to feedback on capital gains taxation.
I am no one, but I have feedback on it too. 😊
While personally, I would love to see pre-2018 taxation where LTCG was taxed at 0%, I am still fine if Long-Term Capital Gains tax on Equities is removed (or at least reduced*) and the holding period for LTCG qualification is increased to 3 years. It kind of aligns with what equities as an asset class demands - staying invested for the long term for best results.
My point is simple. If the aim is to promote long-term behaviour, give incentives like bringing LTCG down to 0% and redefining long-term for equities as 3 years.
*Scrapping the long-term capital gains tax on equities may be difficult for the govt. as LTCG tax on equities brings in decent revenues and, in all fairness, no government would want to give that up easily. So rather than full elimination, reducing it to a small percentage of say 1-5% (from the current 12.5%) may also send the right message.
Another option might be to make a tiered approach where LTCG tax from 1-3 years is 10%, and for holding periods above 3 years, it is removed completely (0%). But this will again make things complex, though desirable and better than what we have today.
Demands to remove LTCG come up every now and then. But the direction so far has been one way only: 0% before 2018, 10% from 2018 to 2024, 12.5% since. Let’s see what comes out of this episode of Bring-LTCG-Down-To-Zero.
But I really hope our govt. does something so that we can forget those infamous lines - Capital gains don't accrue from any effort (iykyk), and someone finally thinks about rewarding long-term investors by rationalizing/reducing LTCG taxes, if not eliminating them fully.


Stable Investor retweeted
Current State of Indian Markets (8-Oct-2026)
The table shows the % Fall of Indices (closing values) from their respective All-Time-Highs (intraday).
Note - Investments in the securities market are subject to market risks. Read all the related documents carefully before investing.
Disclaimer - The indices shown are for illustration only. It is not a recommendation to buy/sell/hold. Please get in touch with your investment advisor to get customised investment advice based on your risk profile and unique requirements.
