

CEO Dirac Advisor Tema ETFs $LAZR -optical ETF Former CEO Sivers Semiconductors. https://xitter.cf/t.co/MvTEwioiQc https://xitter.cf/t.co/3A3qoO1EmB
Stockholm
Joined October 2010
- Tweets6.3K
- Following934
- Followers14.5K
- Likes10.6K





Anders Storm retweeted

Yes, I like $SIVE. It's a fun company to cover, since there's a lot of supply chain alpha here.
But the company completely Tall Poppy Syndromed itself last earnings.
And it's clearly shown in the drawdown.
Bit of a longer consolidated thought and some scattered bits of supply chain info:
- Sivers has 100M CW DFB laser capacity coming online Q4 2027 during an industry shortage.
And very large allocations from foundries online (they were doing these quals with Win Semi + 2 others back in 2023/2024), so they can actively monetize the bottleneck today.
The other interesting reason why bottlenecks are important (aside from ASP hikes), is because qualifications convert much faster + more likely given incentives around supply scarcity.
-> As one example, module makers have expanded the amount of suppliers, eg. (lightcounting cited companies expanding to 5-7+ suppliers from 2-3).
Innolight, for example last month responded to a question addressing tight 1.6T DFB laser supply in 2026–2027:
- Innolight was actively introducing new suppliers last month and are planning to sign 2-3 year-long contracts to lock upstream capacity
-> This is while your biggest merchant laser companies making up the world's 600m+ EML/CW laser capacity like $COHR have redirected lasers to their own programs. $LITE sold out into 2029, Landmark also locked a lot of their capacity into 2027-2029. $AAOI was an expected player, but ended up redirecting lasers into their own transceiver programs too.
And this coincides with times $SIVE has tremendous capacity available now + actively engaged with Chinese pluggables players (not saying it's Innolight, but just shows Chinese makers like Cambridge/Eoptolink are actively trying to secure laser capacity).
- Fun to note, before $JBL was announced, Sivers had and has ongoing direct engagements with hyperscalers as well.
We saw that hyperscalers approached $MTSI and $AAOI for laser capacity from their earnings transcripts (and hilariously got turned away from AAOI due to shortages).
So the odds pluggable makers or hyperscalers end up converting to capacity agreements with $SIVE seems a materially higher.
Just a little rant: for all the sellside/retail trying to model revenue, you can't just slap on a stupid 25-35% CAGR on NRE revenue since it's close to 0 revenue now.
Especially when they scale up to maybe 300M laser capacity (extrapolated from 2:1 external/internal capacity).
It's also not the same as $POET having OE packaging capacity at scale, since lasers are in a genuine shortage. So capacity is more likely to convert like how $AAOI is sold out, $LITE is sold out into 2029
We've already seen what revenue that laser capacity brings in since $LITE cited $5B in laser capacity from just one 2028 fab alone in Greensboro (on higher end ranges).
And whatever lasers Sivers sell, they're targeting ~50-60+ blended gross margins long term on maybe $3-6 for lower range lasers to $6-$12 for high end custom deployments. But no disclosures around capacity -> revenue conversion yet from Sivers.
Now here's the thing people don't really understand, "why no revenue?" for current opportunities?
$SIVE pre 2024 focused on custom development for future architectural shifts like CPO.
For custom deployments:
- We finally got conversion from 1 of their 4 or so lidar customers this week with ~ $AEVA.
- ~ $APPL was confirmed ongoing earlier this year with an explanation that "It takes tremendous amount of trials and algorithms way beyond just what we supply to them".
- All their customers from 2023-2024 like Ayar and 3 others, probably achieve volume in 2028 as CPO takes off.
Custom high end lasers programs are extremely sticky but take many years and are mainly NRE. And as seen with CPO scale up, faced delays with commercialization over the years.
So $SIVE from the CEO shift in 2024 realized "okay" let's ramp revenue with mass commercialization products today like 70mW/100mW/200mW lasers for 800g/1.6T pluggables.
And that's where they found $JBL and all your other large pluggable players today during the shortage.
Now... the work Sivers did in 2023-2024 earlier: Such as $AAPL, Ayar, $AEVA, other lidar/CPO players.
And their new mass commercialization opportunities like $JBL, $GFS, and many pluggables/NPO suppliers in engagement now.
Have all their inflection points converges 2027 onward, which is why I find the company compelling.
Where I think management went completely wrong was messaging and near-term execution:
- Deciding to focus on current tiny contracts like Seminex, AllSpace, Tachyon orders felt like the entire focus recently in earnings, shareholder letters, and media commentary
-> Brutal honesty to $SIVE management, majority of Western audiences literally don't care and it's immaterial to the valuation.
$SIVE moved 0% on all of the Seminex/AllSpace/Tachyon order announcements, and even dropped in price. But rallied like 50% on $GFS and something similar on $JBL announcement.
The reason why most took long positions in the first place was CPO.
So if $SIVE wants to go answer questions to Swedish media about "Why are you bleeding out" and defending that with cellular orders explaining pipeline conversion.
That's not going to help people stay long during drawdowns.
-> Second part was not committing to NASDAQ listing in a certain timeframe and actually executing.
- If there's delays, sure, just say it, but non-committal lawyer-like language is infuriating to hear, especially from the CFO.
I think they'll have that opportunity next month earnings to correct everything.
So wrapping up:
- There's nothing I see remotely close to $SIVE, in terms of % of global CW laser capacity they're coming online with relative to MC.
- They have a ton commercialization paths, from O-Net, $POET, $JBL, Ayar, $GFS, $AAPL, $AEVA, and many potential hyperscaler/pluggable engagements.
Even if one or two fall through, the breadth of ongoing quals is so deep + current laser bottleneck is severe, that it's more likely than not many will convert to production.
It's clear $SIVE wants to focus on dominating the laser chokepoint first, and ended up using their 700m SEK fundraise for capacity expansion.
But they should focus on communicating the billions in potential economic scale from that laser capacity conversion.
And execute on it.


Anders Storm retweeted

Today everyone is wondering whether to implement CPO or not.
And @JensenHuang talks about how they started preparing a new process with TSMC already 5 years ago.
Lower signal loss, significantly higher data rates, lower bit error rates, higher quality, and much lower energy consumption.
5 years ago was a year before the launch of ChatGPT.
There are no coincidences here, just pure execution and roadmap delivery.
Where we are today was planned in advance.
Listen carefully to what He says so you won't be surprised by what happens in a few years.
Follow the leader.
H/T @benitoz

"We need about 10,000 times more AI than we have today." Pat Gelsinger, this week.
Yet the deceleration crowd is reading quarter-on-quarter revenue and calling a top. But QoQ only looks like a peak if you think we're late in the cycle.
Price it against a 10,000x demand ceiling and the same numbers tell the opposite story: we're still early. ~$7.6tn of AI capex is planned for 2026–31, and US data center demand is heading toward ~194 GW by 2035. That doesn't get us close to 10,000x. IMO the supercycle hasn't slowed, however the market is now pricing it like we passed the peak.

- Co-packaged optics technology transitioning from R&D phase to manufacturing readiness
- Ayar Labs advancing toward production-scale deployment of integrated photonic solutions
> Ayar Labs is moving co-packaged optics technology beyond prototype validation toward actual production planning, indicating the technology is approaching commercial viability.
> This represents a critical inflection point where technical feasibility translates into manufacturing scalability and market readiness.
eetimes.com/co-packaged-opti…


The Light Is On: Wiwynn, Ayar Labs and GUC Bring real “endgame” Optical I/O to a Running System
The three questions this post answers:
What is actually new? The same partners showed a rack at Computex. Why the OCP demo is a different order of event, and the missing piece it fills in Goldman Sachs’ optical roadmap.
Is CW-WDM MSA dead? The common view is that OCI MSA replaced it. Why that is a category error, and what the public record says about the light source inside this demo.
Who is behind it, and whose lasers are used? Which hyperscaler an ODM like Wiwynn is really building for, and whether Sivers is still the laser inside SuperNova, or ....
andersstorm.substack.com/p/t…

Anders Storm retweeted

$MU still has to be one of the more mispriced stocks in the market especially after Davidson just raised their PT to $3,000.
Here's some key points on $MU:
1. Keep saying it's cyclical all you want. It's still not.
-> 87% gross margins are not a sign of a "cyclical" stock.
-> $33B worth of FCF (61% margins) + cash position covering a further buildout is not a sign either.
2. If EPS doesn't grow from Q1 forecast...we're looking at $153 in EPS in FY27 which means the stock trades at 7x EPS.
-> For reference the $SPY now trades ~21x EPS.
3. 87% gross margins, 61% FCF margins, $68B of cash vs $5B of debt is all sign of a quality company.
-> That quality matters less if the spike is short-term but there is no argument to make right now that demand for memory doesn't grow in both training and inference.

Marvell $MRVL, shared some outstanding Capital Markets day numbers $70-90B by FY31. That is a CAGR of 55-50%.
This underpins the whole long-term case as well as that the AI supercycle has a long runway.


As we talked about in the last X Space with @YuriKhodjam CIO @TemaETFs photonics is on the move again. Listen into the link below. Up 7.69% this week.


Anders Storm retweeted

$MU CEO says the company “delivered an exceptional quarter” as revenue keeps rising even while pricing gains start to moderate.
That means more growth is now coming from bits and mix as AI demand broadens across HBM, server DRAM and enterprise SSDs instead of depending on another huge move in spot pricing.

My initial read on why $MU isn't more green is that Q4 was still heavily price driven with DRAM revenue up 27% while bits only grew mid single digits and NAND up 42% with ~30% pricing so the market is still treating these earnings like a peak that fades once supply catches up.
What changed this quarter is management gave us a lot more visibility into why that may not happen anytime soon with 75%+ of next year’s output already committed, SCAs stretching into 2031, margins rising after Q1 and meaningful new cleanroom capacity still not arriving until late 2028.
If Micron can sustain something around $200 of forward EPS and market eventually decide that setup deserves even 10x instead of 6x then you're suddenly looking at $2,000 stock without needing an aggressive multiple.

Anders Storm retweeted
$LITE CEO: "Next year with the advent of CPO and NPO in 2027, our estimates are that we'll be undershipping demand...
By 70%. Literally 70%. So we can only supply 30%.
And this has caught us by supply. By 2029-2030, we get to some level of balance."
Source: Global Photonics Economic Forum Day 1 (7:57:15 - 7:58:00)
Any other players with laser capacity coming online are probably going to get more market attention soon.


Big movements today in some $LAZR stocks. $LITE $COHR $AXTI..Seem like optical stocks are moving again.


Ahead of a much-anticipated IPO, $LAZR now offers more exposure to Anthropic by portfolio weight than any other U.S.-listed ETF (per Bloomberg). Explore $LAZR: tema.us/4j0igZq
Anthropic is a private security accessed through an SPV and is 11.44% of LAZR holdings as of Sep 30, 2026. Private investments held through SPVs carry additional risks. Consider fund risk and objectives before investing. Consult the fund FAQs and disclosures for more information at the link above. Vigilant Distributors, LLC.
Fantastic report and outlook by $MU! Share still yet negative after-hours.

Micron Technologies - 10th largest company by market cap - reported earnings that beat expectations.
- Adj EPS: $33.42 vs $31.82 expected
- Revenue: $54.23 Bln vs $50.95 Bln expected
Revenue forward guidance of $61.5 Bln vs $57.0-57.6 Bln expected.
$MU still down afterhours

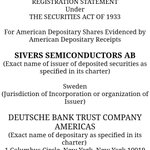
Deutsche Bank has filed an F-6EF for $SIVE ADRs (1 ADS = 3 shares, 25M registered, effective immediately). It looks unsponsored: DB is the only signatory, with no agreement with Sivers. So it's probably not the US listing, just a potential OTC access route once a ticker goes live. DB recently filed the same for Silex Microsystems. But let’s see what happens.
sec.gov/Archives/edgar/data/…


Interesting data point this is why $AXTI is in the $LAZR
portfolio. More on the company here:
andersstorm.substack.com/p/a…


ECOC 2026 just wrapped in Málaga. The takeaway: optics is no longer a module business, it's a packaging and light-source business.
Joining @YuriKhodjam, CIO of @TemaETFs , to unpack what it means for $LAZR and the photonics trade.
🎙️Join us on X Space: Monday 28th 6 pm CET xitter.cf/i/spaces/1aKbdEVqZBkJX
Physical AI is now starting to appear more and more. I think we are just in the absolute beginning of this AI super cycle.

Today, Smart Eye unveils a world-first multimodal in-cabin AI agent.
It goes beyond voice and vehicle data to understand the driver, their gaze and state, others inside, and what’s happening outside.
See it at #InCabinEurope, booth #305.
Read more: hubs.ly/Q04y5V4z0
Anders Storm retweeted
Elon Musk: "AI will beat [humans] in all fields by the end of next year or maybe 2028, at the latest."
Kind of maps to Anthropic's economic implications paper where 2026-2028 was the buildout.
Then 2028-2030 was unprecedented economic growth.
So we're still early H2 2026.

Anders Storm retweeted

Investors seeking pre-IPO exposure to Anthropic can now gain access at a valuation of $1.39 trillion through $LAZR.
Learn how: tema.us/4ybm8LM
Anthropic is a private security accessed through an SPV and is 12.29% of LAZR holdings as of Sep 18, 2026. Private investments held through SPVs carry additional risks. Consider fund risk and objectives before investing. Consult the fund FAQs and disclosures for more information at the link above.
