

Dallas, TX
Joined October 2022
- Tweets1.3K
- Following252
- Followers438
- Likes9.8K






✨Mortgage Prepaids👇
🔸Prepaid Homeowners Insurance - Lenders typically require you to pay the first 6 to 12 months (or up to a full year) of your homeowners insurance premium upfront at closing to ensure the property is protected from day one.
🔸Prepaid Mortgage Interest - This covers the daily interest that accrues on your loan from the exact day you close until the end of that current month, bridging the gap before your first regular monthly mortgage payment begins.
🔸Prepaid Property Taxes - You will generally pay a prorated amount of local property taxes covering the period from your closing date through the end of the current tax cycle or year to ensure enough funds are available when the next tax bill is due.
🔸Initial Escrow Deposit - Lenders often collect an extra 2 to 3 months of property taxes and insurance payments at closing to seed or cushion your escrow account, making sure future bills are always paid on time.
🔸HOA Dues - If the property belongs to a Homeowners Association, any required advance or prorated dues are collected at this time
🤖 Made with AI

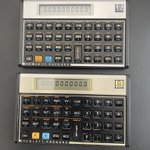
✨My 2 HP calculators I’ve used in my 2 different careers. HP-15C when I worked as an electrical engineer for 17 years. HP-12C for my current job in finance…

✨The Breakdown👇
1️⃣ Approved (Clear-to-Close)
🔸All paperwork is complete, risk is acceptable, and your loan meets all guidelines.
🔸You are cleared to move forward to the Closing Stage
2️⃣Approved with Conditions (Conditional Approval)
🔸Your loan is generally approved, but the underwriter needs specific extra items before issuing a final sign-off (such as updated pay stubs, proof of homeowners insurance, or an explanation of a bank deposit). This is the most common outcome.
🔸Submit the requested documents quickly to clear the conditions and reach a clear-to-close status.
3️⃣Suspended
🔸The underwriter cannot finish reviewing your file because critical documentation is missing, unverified, or incomplete. A suspension is not a denial; the file is paused in limbo until you provide the missing pieces.
🔸Contact your loan officer immediately, supply the missing records, and ask to reactivate the review.
4️⃣Denied
🔸Your application does not meet the lender’s risk or program guidelines (common reasons include a high debt-to-income ratio, a low appraisal, or unverified income).
🔸The lender must send you a formal Letter of Adverse Action detailing the exact reason for the rejection. You can talk to your lender about fixing the issue, writing an explanation letter, or applying with a different loan program.

✨Why CLTV Matters to Lenders👇
🔸Lenders use CLTV to evaluate the risk of default and how much equity remains in the property. If a foreclosure happens, the primary mortgage holder gets paid first, leaving secondary lienholders at higher risk
🔸A high CLTV ratio can lead to higher interest rates, stricter underwriting requirements, or loan denial.
🔸When calculating CLTV with a HELOC, lenders often use the full credit line limit rather than just the drawn balance, depending on the program
🤖 Made with AI


🌼For years I could not get anything to grow on this side of my home and even started experiencing soil erosion until I threw 2 packages of Texas wildflower seed over this area 2 years ago. It’s a jungle now…

✨Borrowers can log into the Internal Revenue Service (IRS) "Get Transcript Online portal" and view or download their tax return transcripts for free, but most lenders will require a formal requests through IRS-approved channels like Form 4506-C via the Income Verification Express Service (IVES)
🤖 Made with AI

✨How It Works👇
🔸Automated Valuation -The lender uses data algorithms instead of a physical inspection.
🔸Data Sources - Systems check recent comparable sales and public tax records.
🔸Official Names - Also called "value acceptance" or automated collateral evaluation.
🔸Lender Control -The automated underwriting system decides if you qualify.

✨These will be the most common solutions if not able to make an in person closing. Check first with your lender and title company if using one of these options...
🤖 Made with AI

✨The benefits of owning a home in Texas include👇
1. Significant Property Tax Deductions
🔸Filing a homestead exemption removes a portion of your home’s value from taxation, dropping your annual tax liability.
2. The 10% Annual Assessment Cap
🔸Even if local real estate values spike dramatically, the homestead exemption prevents your home's taxable appraised value from increasing by more than 10% in a single year.
3. World-Class Creditor Protection
🔸Texas features some of the strongest asset protection laws in the nation. Under the Texas Property Code, a homestead is broadly protected from forced sale by most creditors to satisfy personal debts, credit card balances, or medical bills.


✅ When a New Survey Can Be Skipped👇
🔸Existing survey available: An older survey works if the title company and your lender accept it.
🔸No property changes - The seller must sign a T-47 affidavit or T-47.1 unsworn declaration stating no structural changes, fences, or additions were made.
💰Cost savings - Reusing an old survey saves a few hundred dollars in closing costs

✨Types of Title Insurance Policies👇
🔸Owner's Policy - Protects your financial investment and ownership rights against pre-existing, hidden defects (like forged deeds or missing heirs). This policy is optional for the buyer under Texas law.
🔹Lender's (Loan) Policy - Protects the mortgage company's financial interest up to the loan amount. Institutional lenders mandate this policy as a condition of financing


