

Tech investor for ~25 years. Ran large hedge fund for 10 of those. Here to help. Not investment advice. I never reach out to sell ANYTHING.
NYC
Joined July 2018
- Tweets2K
- Following352
- Followers19.5K
- Likes2.5K
$MSFT reported an all good in the hood quarter.
Office365 accelerated to 18% yy cc driven by people adoption copilot. They now have a cross-surface solution across all the apps and say 90% of queries use the default model. So the bull case is they do to ANT / OAI what they do to all competitors. Had a buddy who worked there and said MSFT is the only company that successful comes from behind once someone else demonstrates a big market exists (see Teams vs Slack / Zoom, Azure vs AWS, etc.). Seats are growing 5% and pricing uplift is now 13% yy cc!
Azure accelerated to 48% yy cc and they guided to 49-50% yy cc. No slowdown in the hyperscaler buildout / monetization.
OAI was 10b of rev in the qtr or 11% of rev. This is direct Azure contribution but also rev-share. Compares to OA being 24b last FY or 7% of rev. MSFT owns 24% of OAI.
O365 and Azure are now 55% of the business and I don’t care about the rest unless it slides into the ocean.
OM of 49.8% was up nicely from 48.9% last Q1. They guided to margins being down slightly including all the “Pls don’t show up tomorrow” memos they sent to 60k people. Seems conservative. I’m a bit ahead on revenue so I get margins up slightly.
Business is good at $MSFT. Revenue should accelerate this year and next FY w/ margins expanding despite the mix shift to Azure. They are the most responsible of the hyperscalers and staying FCF positive for now.
Stock trades at 22x CY27 EPS and 18x CY28. 27x presents 21% upside over the next few months and 51% upside over the next year.
Maybe downside of 13% to 22x street CY27 EPS.

$GOOGL reported a mixed quarter.
Search is 39b of segment profit in the qtr out of overall profit of 41b so understandably everyone freaks out when search is squishy.
Stock trades at 18x my GAAP 2027 EPS which is a bit above street for >30% operating profit growth.
Kind of a tough one: Search - who the hell knows, Cloud - doing great, YouTube - doing fine.
Search
Rev of 63.3b slowed to 12% yy and will likely slow to 10% yy in Q4. Tough comps along w/ China advertisers slowing since the EU stopped tax-exemption for small order e-comm. It was the worst qq Q3 since the 2022 slowdown.
Query growth remains healthy and they stated AI queries are mostly additive to traditional. Testing for ads for AI has gone fine and they will turn on monetization internationally soon.
Very hard to parse – obviously bears think search is moving to ChatGPT / Muse / etc. while bulls think search pie is just growing, GOOGL users are loyal, and GOOGL will enjoy last-click attribution (last place you search before you buy) (offset by maybe Muse becomes the last place you buy bc you tell it to find you the best deal).
Obviously tons of background questions come to the foreground with a miss, but these things don’t die overnight so my bias is probably more towards the upside bc turning on AI mode monetization can move the needle.
Margins of 41% were up from 39% last Q3.
Cloud
Rev of 29.7b (excluding maybe 1b in TPU?) accelerated to 96% yy w/ 5.0b net add vs 1.5b last Q3. They have big deals ramping through this year including the 16b ANT ARR. All good in this business line as the AI buildout continues.
TPU sales also are ramping and going well. ANT disclosed their 125-150b contract but that starts in 2028.
Margins of 37.4% up from 23.7% last Q3. There will be some pressure going forward as they use expensive SPCX capacity to fill supply-constrained gaps.
CAPEX productivity seems to be holding at around $1 of capex producing 70c of incremental forward revenue. I still have that dropping to 0.5x for 2027 rev and 0.4x for 2028 rev which means my cloud estimates might have upside.
YouTube
Rev of 11.2b grew 9% yy against a tough comp also w/ weak 152m net add vs 465m last Q3. Whatever, this business doesn’t move the needle.


Ok, it might be over folks.
Anthropic revenue disclosure maps to ~5.8b in September revenue or 70b ARR which means August / September only increased by 2-3b ARR in each month.
[There is no way that ARR is calculated using last day of the month as that would be more aggressive than anything I've ever seen out of companies this size (exception: Musk).]
Worst monthly numbers by far this year. (Maybe some self-infliction from cleaning up distillation?).
My rough math indicates OAI / ANT ARR monthly add softened from 16b in July to 10b in Aug to 9b in Sept. That is no bueno...
Supportive of the view that either CAPEX is getting cut or pricing is going to weaken substantially.

OpenAI at 70b net never really made any sense intuitively.
Still seems like net ARR added in September was 17b similar to 17b in August. 17b is still pretty ridiculous and suggests we finish the year ~200b gross across ANT / OAI.

@a16z put out a solid deck today on State of AI.
Does a good job of just putting it all together - AI capabilities rapidly expanding, AI model revenue ramp unprecedented, semi spend underneath unprecedented and driving earnings growth of the entire stock market, and multiples reasonable due to cyclical concerns.
To me, the "elephant in the room" question is simply will AI monetization accelerate over the next couple years from what likely will be ~200b run-rate at the end of this year.
Very rough math, but we added ~170b of model revenue in 2026 against 1.4t of capex over the past 3 years and 780b in 2026.
Expectations per chart below are for 1.1t of capex in 2027 which then flattens. Maybe that implies the model companies in aggregate need to add ~200b of ARR each year to justify that spend?
Is that possible? Sure but also tough to assign probability bc there are a million unanswerable questions underneath (product development, pricing power, etc.).
That's also the bear case for semis for a future date: even if model companies plus others can add ~200b / year of incremental revenue, that implies semi spend stagnates after 2027 -> second derivative turns negative and multiples stay low until the inevitable downturn.
I personally think 2028 is probably a 20-30% growth year in capex so the whole trade is more likely to up than down from here at these valuations, but just pointing out the risk that the market is pricing in here (and that has to dissipate via continued ARR growth / hyperscaler capex growth commentary to see the trade run).
[Btw, I also think it's so fascinating that leading investment firms are also publishing leading news / research. This free newsletter from A16Z smokes independent publications (WSJ, Gartner, etc.), and the sell-side (less conflicted in some ways and more informed)]


Should have added that OAI simply saved down that I have $FDS and will just use it when it needs to going forward....!
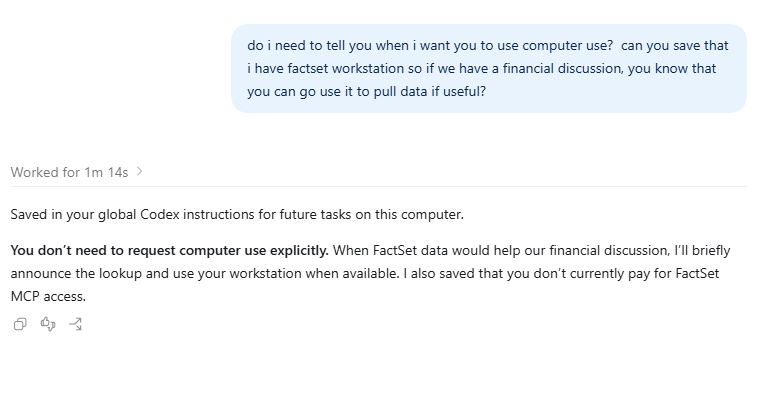
Another day, another bit of AI functionality, and another question as far as incumbents...
So I previously tested $FDS MCP which was a huge advance for AI financial functionality, and a growth driver for $FDS subscriptions (call it 20% uplift to enable).
And then today I tested just using OAI's computer use on the regular desktop session, and it worked pretty well albeit a lot slower.
Kind of funny how quickly some of the SaaS bear points from earlier this year are materializing...
In this case, it's that usage of the SaaS app becomes more automated from outside and becomes unmonetizable...
(Separately, being bullish on $CRM Claudeforce is really puzzling to me - that felt more like a defensive point for the SaaS won't go away tomorrow than an offensive point for SaaS will participate in AI).
