

Mapping the 2025-2035 AI Build Out. Focus: AI x Macro x Energy Infrastructure. Institutional-grade Intel for Investors. https://teapaw.org/t.co/Mro3MmPr0u
Vancouver, Canada
Joined February 2011
- Tweets54.6K
- Following691
- Followers6.1K
- Likes71.5K




Confirms my thoughts on adoption as I wouldn't trust an agent with financial decisions yet, maybe one day but I don't feel comfortable yet. How many years away until the broad comfort level is there for mass adoption to occur?

Interesting bits from Brian’s Airbnb earnings call about AI agents and consumer behavior:
— Airbnb gets ~500k bookings a day
— ”very non-material” traffic from Muse/Instinct
— says people *want* to browse: average user looks at dozens of listings and 25+ photos
— 90% of users message the host
— most traffic comes between 9 to 5 when people are at work (using Airbnb as escapism)
— 80% of travels say they like doing their own travel research
The cope is palpable, I held my shorts over the weekend and expect to get a good flush down Monday/Tuesday into an overdue rebound of sorts.

Beat @citrini to it by many months. I still don't think he's bearish enough.

Jukan is 100% right here and I'm happy for him that he's becoming a serious analyst by going against the Eco chamber on this app. Of course he's getting grilled for it by swathes of morons that have no clue that LTA's aren't bullet proof and won't magically prevent their stocks from crashing.
Jukan's detractors are about to get rinsed again in 2027 and next time there will be crickets from these accounts. Keep up the good work @jukan05 and pay no mind to these amateurs.

I'd like to believe LTAs are durable too. But take one example.
Analog chipmaker onsemi said this in 2023.
On January 5, 2023, at JPMorgan's CES forum, CEO Hassane El-Khoury was asked how much LTSAs would still hold once the shortage eased. His answer: “They are a legally binding agreement ’cause they’re a liability for the customer because they’re take or pay.” He also said he would not accept a customer reopening price talks just because it could get the same parts 10% cheaper elsewhere.
On October 30, 2023, on the Q3 earnings call, onsemi cut its SiC shipment forecast for the year from $1 billion to more than $800 million after one automotive OEM reduced demand. An analyst asked how this could happen when the company had been saying its LTSAs were legally binding. The same CEO reaffirmed that they were binding, but said he did not want to enforce the contracts just to push inventory onto a customer whose demand had dropped. If it worked for both sides, terms could be adjusted customer by customer, whether by a quarter, a year, or longer.
In its 10-K filings, onsemi also states that it amended LTSAs with some strategic customers by mutual agreement in 2024, and changed delivery schedules and committed volumes on some LTSAs in 2025 as demand shifted.
Microchip is another case. Customers in its Preferred Supply Program (PSP) originally had to place 12 months of orders and could not cancel or reschedule them unless Microchip raised prices. On its November 2025 earnings call, however, the CEO said the company had accepted some cancellations and pushouts so customers could adjust their backlog. On the same call, the CFO separately addressed the multiyear LTSAs the company had signed. Some of those contracts were still in effect, he said, but customers had been allowed to defer taking delivery of committed volumes by one to two years if they needed to.
Every time I see cases like these, I doubt how much memory makers' LTAs will protect earnings in a downcycle. Right now the most reliable thing is the prepayments and deposits themselves. That cash can go into capacity expansion today.
I can picture hyperscalers with no DRAM inventory continuing to buy at current prices. But once inventory has piled up, will they keep taking every committed unit at the same price? I have a hard time picturing memory makers holding customers to the high contract price all the way through.
The LTA itself may never be broken and may stay in place. But if both sides agree to push this year's volumes into next year or two years out, this year's earnings estimates come down. If price gets renegotiated too, margin estimates have to come down as well.
Again, I agree LTAs are sturdier than they used to be. What I question is whether, after demand turns, memory makers can still earn 80% margins on contracts signed during the upturn and keep collecting hundreds of billions of dollars in profit because of those LTAs.
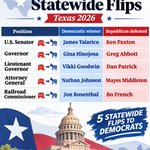
Every day people are struggling and surviving increasingly on credit. Inflation and increased cost of living was in my opinion the main reason the house and senate flipped so dramatically in the blue wave. This isn't a reassuring look as we head into 2027, on the cusp of a bear market.

A government AI backstop will be the only solution. It's easy to see where this is going despite how unpopular it will be.

hearing some chatter that anthropic is now lowering down to $1tn to get this IPO done. let me explain why this doesnt matter and its actually all over-
the entire existence of this company is based on a funding model that inherently has extreme asset liability mismatch. what that means is that just like the hyperscalers are diluting their equity fund capex, there is an expectation that anthropic will also have to do the same. ie it needs strong equity to perpetuate the scheme
but if you IPO at the wrong price (and dont get a pop which increasingly appears they wont be; spacex already below) then youre now in the death spiral that crypto investors should be very familiar with: its called the reflexivity trap of the confidence game. its the "ill bid FTT at $22 all day" or the "steady lads UST is $1" game, with all its lucid horrors. and here is the key insight- the confidence game exists at the service of the creditors. if there is no credit, there is simply no equity. and there is no credit, if there is no collateral
if the credit rating agencies are not going to give IG at $2tn, they are certaintly not going a better HY rating at $1tn. and there is no world in which anthropic can exist without credit because ~$1tn of commit, much of which is noncancellable, is a straight up negative equity pledge
yet there were two scenarios in which i was willing to concede anthropic could IPO: first 1) the improbable but possible was if the hyperscalers/chips oligopoly came to rescue and plug the hole, given their incestuous nature of revenue bookings and paper gains/losses at scale. but it is clear now that the market has spoken this will lead to a mutual death, and should not be attempted. or perversely even better, they are actually better off letting anthropic go to zero so they can acquire the pieces on the cheap which is the best nash equilibrium outcome, not just for the dominant player but for society at large. second 2) the us government can nationalize the company and collude with other sovereigns (like UAE, Saudi, Japan who are basically already the checks) to force its funding as a collective bargain. this gives you trillions, which is actually the most effective backstop to restore market confidence. the first edge case does require an IPO, but the second edge case here for which i believe there is still a good chance that this is the ultimate end game- will require a failed IPO to recapitalize at a normalized price for the consortium (and dont forget that openai front ran this investor group in anticipation of this dynamic to play out as a private co last month)
i believe the market is crapping out today because the market is recognizing it will not IPO. and actually, as ive said before, this is a very good thing. i might even imagine that the market could quickly rebound on the news of its IPO being delayed because it allows #2) to play out, as not only a national, but an international bailout. the US is more likely to tolerate, even relish, the taxes of foreginers to fund our domestic companies. that is the only end game that really matters, and the end game i am going to be excited to see
we'll see if this newly revamped washington can figure it out
While we know most Economist covers are a warning that the exact opposite of what they say is about to happen. Surprisingly one cover 'The Year Ahead' has been exceptionally accurate. Take last year's issue for example, several of their predictions came true this year. The 2027 year ahead issue will be released Nov 26, looking forward to it but there better be a mention of the 2027 bear market or it's getting thrown in the bin.
🤖 Made with AI


🎶I know this look, I've seen the movie. Ive read the book. Those Blood red candles, I know it's coming it's no surprise. Out into the bear but couldn't the bull market stay awhile? You never last for long. Back into the bear and why not stay alive?
For Fin x Furu's it was never about self respect, if you can fool yourself, why not fool the rest?
Back into the bear and why not stay alive? Its never been your way, back into the bear.🎶
If you listen to Dan Ives your going to blow up your portfolio even worse this year. The bear market is just gearing up.

DAN IVES SAYS THE TECH SELLOFF AFTER THE MIDTERMS IS "WAY OVERDONE"
He compares it to the March 2020 COVID selloff and the April 2025 "Liberation Day" selloff, which he calls buying opportunities for tech's winners.
- About 40 GW of US data center capacity should be online by the end of this year, with another 40 to 45 GW going live in 2027
- Data centers already permitted or under construction aren't being stopped, he says, including in Texas
- Even if 30% of planned data centers were canceled, he still sees $3T to $4T of Big Tech capex over the next few years
His view: the election slows the AI buildout but doesn't end it.

Sell the rallies, Nasdaq futs recovered 1000 points that's good enough excuse for me to short again.


The hilarious thing was when I was long AI January through to July I even mentioned that I know I'm pushing my luck here staying long into the summer because it could end at any moment. I was already planning my exit back in March. That's where having a good bear thesis comes handy. And now I know for certain that it is next year.