

Mining Research Investment Community. If a gold mine is a hole in the ground with a liar at the top, we are going to help you to find the Truth Below Ground.
Everywhere
Joined July 2025
- Tweets1.1K
- Following227
- Followers941
- Likes761




Pinned Tweet
🔎 Is the precious #metals bull thesis broken?
#Gold, #copper, #lithium, #uranium and mining companies face rising real rates, $100+ oil and growing stress in global bond markets.
We connect the dots in our latest newsletter 👇
truthbelowground.com/en/towa…
#Mining #Commodities

Truth Below Ground retweeted

Commodities are getting hit pretty hard alongside the broader equity market as the surging U.S. dollar sucks liquidity out of the global financial system. For those that follow me, I've been saying this from some time that there was risks if the dollar strengthens too quickly.
The issue is that dollar-denominated debt becomes more expensive to service, financial conditions tighten, and investors are forced to raise cash, reduce leverage and sell assets. It becomes less about fundamentals and more about liquidity.
One thing I've learned over the years is that market leverage doesn't necessarily tell you when a correction will happen, but it tells you a great deal about how painful that correction could become. For some perspective, U.S. margin debt has surged to approximately $1.45 trillion, equivalent to roughly 58% of U.S. currency in circulation and 6.2% of M2 money supply. That's an extraordinary amount of leverage in the system, and when markets start moving against investors, it can accelerate the selling pressure.
Unfortunately, even gold isn't immune. During a liquidity-driven selloff, investors often sell what they can, not necessarily what they want to. Gold can become a source of cash to cover margin calls and offset losses elsewhere.
The irony is that the very forces driving the dollar higher could eventually create the conditions for its reversal. The U.S. government and broader financial system have become increasingly reliant on negative real interest rates to help manage an enormous debt burden. A prolonged dollar-driven liquidity squeeze makes that increasingly difficult, raising the risk that something eventually breaks and forces central banks to step in with lower rates and additional liquidity.
That's when things can get interesting for gold. It may get sold during the initial panic, but if policymakers respond by driving real interest rates back into negative territory, the combination of easier money and renewed currency debasement concerns could send gold sharply higher.
In other words, the same liquidity squeeze hurting gold today could ultimately create the conditions for its next rally.
We're watching all of this closely and remaining deliberate about managing exposure through what continues to be a challenging market environment through to the end of the year.
Truth Below Ground retweeted

“Mining equities don’t price in high spot because the market expects that spot will come down”
“Ah got it, so then when spot falls the miners should be unaffected?”
“No, actually, the miners will still go down more than the physical”
Thank you markets, very cool

Five #mining companies. 35 questions.
Our new members-only Q&A covers @HotChiliLimited, @Rio2Limited,
@ngex_minerals, @SigmaLithium and @SavannahRes, and more.
Geology, management, valuation, ESG and engineering.

Some questions we answer:
· Can La Verde join Costa Fuego's reserves?
· Is Barroso fully funded after a US$40M raise?
· Is Rio2's team ready to run two mines?
· Why can a bigger fleet worsen dilution at Sigma?
Learn more 👉 truthbelowground.com/en/#mem…

El #cobre cae hoy fuerte y encadena 5 sesiones a la baja. Pesan la fortaleza del dólar y las dudas sobre la inversión en centros de datos de IA. Pero en China la prima por importarlo marca récord. ¿Algo no cuadra?
Recibe gratis nuestra newsletter: eepurl.com/jkOc3Q


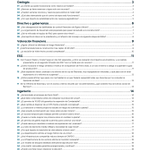
Por ejemplo:
· Por qué no conviene sumar sin más recursos y reservas
· Qué gana Barroso (Savannah) al pasar del estudio conceptual al DFS
· Por qué en la mina de Sigma una flota mayor puede empeorar la dilución
1
63
Son las cuestiones técnicas que separan leer un titular de entender de verdad un proyecto minero.
👉 Hazte miembro y accede al documento completo (adjunto índice):
truthbelowground.com/tienda/
¿Te interesa, de momento, acceder solo al documento? Contáctanos.

Truth Below Ground retweeted
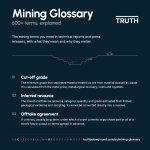
Hemos abierto el Glosario minero de Truth Below Ground: +600 términos en español e inglés, con qué significan y por qué importan al inversor.
Ley de corte, recurso inferido, offtake… lo que lees en cada press release.
👉 truthbelowground.com/glosari…

Truth Below Ground retweeted

Good one! 🇺🇸🫤
U.S. Mining sector: "“Right now there are more PowerPoint decks than permits, so the question is how many of these projects exist only in PDF form and how many are shovel-ready,” Kapadia said..." ⛏️

Metals War
Trump’s minerals push has yet to loosen China’s grip ahead of Xi talks 🇨🇳🇺🇸
mining.com/web/trumps-minera…

Truth Below Ground retweeted
5 metros de nieve y 8.500 onzas de oro en el 3T. Pese a todo, Rio2 ( $RIO.to ) mantiene el objetivo de producción comercial en Fenix Gold en el 4T 2026; el AISC fue de 2.615 $/oz y la caja cerró en 26,8 M$. Hito a vigilar: que el ramp-up llegue en plazo.
rio2.com/post/rio2-reports-q…

Truth Below Ground retweeted

Capital allocation indeed is an art form, and a share price is one of the most powerful tools the CEO and the management in general can have.
When returning capital to shareholders, buyback/dividend-ratio should always reflect market conditions. In a depressed market, buy more shares, and at higher multiples, feel free to increase the dividends. Going 100% dividends, which is the most common one when returning capital, is rarely the most efficient move, although I’m fully aware that large shareholders usually lobby for dividends, and that cutting the dividend yield can make the stock more unattractive to some. However, in my opinion it should always be a mix, unless the valuation is clearly way too high, or low.
What works in returning capital, works similarly when acquiring something, whether that be working capital or assets. Your share price can get you cheaper capital than any presentation or loan ever will, but only if you can time the share issuances correctly. In a extremely volatile sector like junior mining, almost all companies have at some point a great chance to raise capital at decent, sometimes even ridiculously high valuations.
The companies need to take advantage of these spikes, because the base case, especially for developers and explorers is that they will spend most of the time by trading woefully, and that is when capital gets pretty expensive.
In example, if you are a critical mineral/rare earth explorer/developer, and didn’t raise money during H2/2025, what are you doing? You will likely never be able to get capital that cheaply again. Raising when everyone is having a time of their lives also requires a management team competent enough to honestly assess the company value compared to the market value, and recognize the opportunity to do a favour to the shareholders. The goal is not to raise or acquire assets at the exact top, but to avoid the need to raise money at the bottom.

Truth Below Ground retweeted

El metal no elige la minera por ti. En junio, @duediligenceguy y @fruf82 debatieron el ciclo del uranio en Charlando de minas. Una tesis para el sector no sustituye el análisis de cada empresa. Recuperamos la conversación: youtube.com/watch?v=ddyD44NG…

Capital allocation is very important for mining businesses. This 👇 illustrates the downside of share buybacks.
Capital allocation is an art, not a science.
Every capital allocation tool has its role to play, but which one is better depends on the specific context.

Almonty $ALM used almost US$50M of its cash (debt) to purchase back roughly 3 million shares at a weighted average price of US$16.58. The share price today is US$7.63.
Wonderful use of capital (debt) 🙌🏻

Truth Below Ground retweeted
La nieve también entra en las cuentas de una mina. Rio2 produjo 8.500 onzas en Fenix Gold en el 3T, afectado por tormentas. Mantiene su objetivo de producción comercial para el 4T: un hito que seguimos en @TruthBelowG, no un resultado garantizado.
5 metros de nieve y 8.500 onzas de oro en el 3T. Pese a todo, Rio2 ( $RIO.to ) mantiene el objetivo de producción comercial en Fenix Gold en el 4T 2026; el AISC fue de 2.615 $/oz y la caja cerró en 26,8 M$. Hito a vigilar: que el ramp-up llegue en plazo.
rio2.com/post/rio2-reports-q…
Fuente: resultados de @Rio2Limited del 3T 2026 (10/11/2026)
Rio2 es una de las compañías que analizamos en TBG. Lee el análisis completo: hazte miembro → truthbelowground.com/#member…
1
124