

Writing investment blog value2wealth since 2010. By luck got first 100 bagger in 9 years (TechNVision Ltd) . Trying to find market misunderstood bets.
India
Joined October 2015
- Tweets2.5K
- Following593
- Followers8.2K
- Likes5.2K




Pinned Tweet
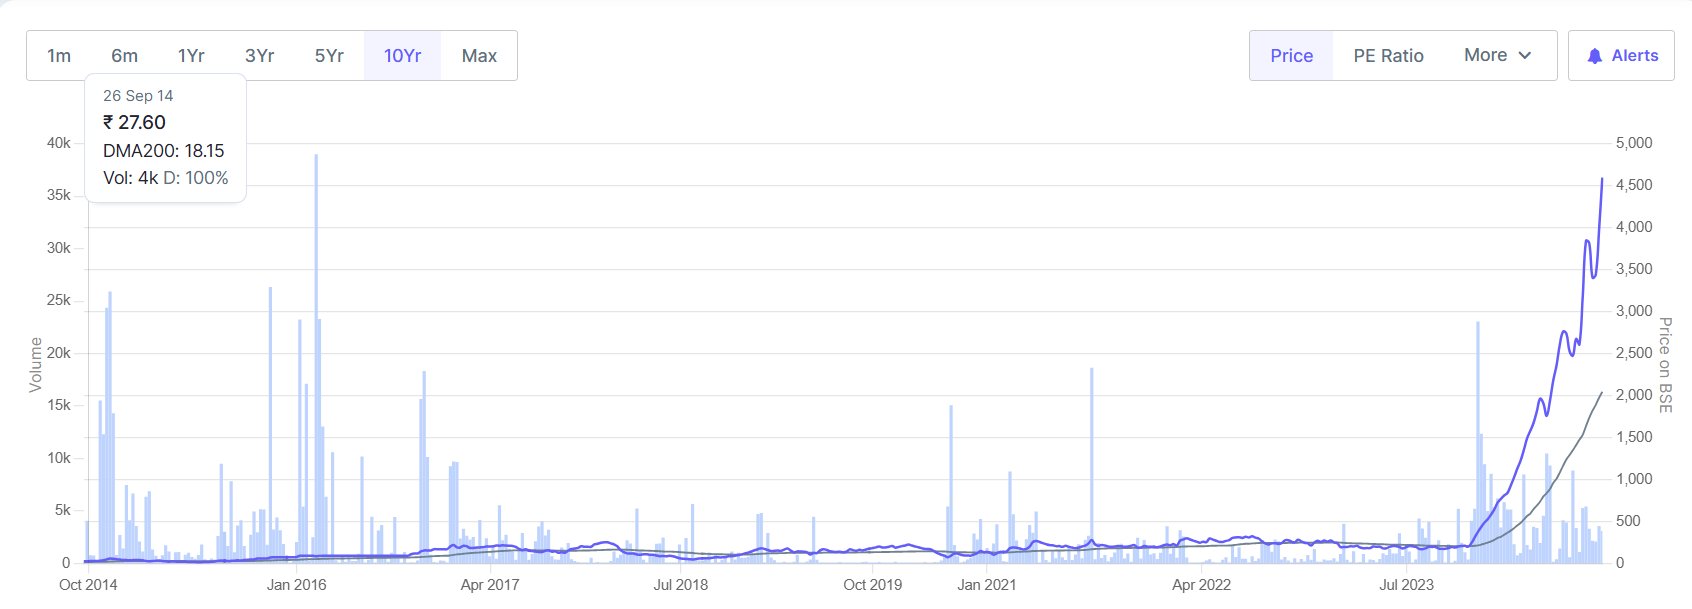
By God’s grace, the day has finally arrived when TechNVision has turned into a 100-bagger for my Value2Wealth blog followers friends as well. I first wrote about TechNVision in October 2005 when it was priced at just ₹45. Today, it has reached ₹4597—a remarkable increase of about 102 times in less than 9 years, with a CAGR of 68%.
Old Post Link : value2wealth.blogspot.com/20…
To be honest, I feel fortunate, as replicating this success would be slim.
I made 100-bagger but in that process I lost lot of quality followers friends on twitter because I use to bombard with every NEWS or other details on TechNVision very frequently .
I was very confident in the business's prospects. While it once seemed untouchable, it is now part of MEGATrends like Data for Generative AI/ Enterprise AI, data purging and archiving for data centers, and data compliance
I had mentioned this stock as bamboo value stock pick in 2015 , I was expecting to become bamboo in 3-4 years but it took almost 9 years.
Holding for 9 year was very difficult part because lot of time I flustered with result , some time with ASM , GSM .
Value2Wealth Investor retweeted

Having global megacaps on a single vendor slide is extraordinarily rare for a company of TechNVision/Solix's revenue scale (270 Cr ).
This roster directly validates the core thesis: Solix is not an aspiring micro-cap trying to break into the enterprise market; it is an established, infrastructure-embedded provider across the Fortune 500.
When a $30M USD software firm manages historical data layers for $100B+ conglomerates, it proves that the software possesses high intellectual property value and switching costs.
Replacing an active database archiving engine that holds 10 to 20 years of historical corporate records requires massive data migration budgets and risks regulatory non-compliance. This creates high net retention rates (NRR)
And that NRR of 130 itself can grow its sales to very meaningful scale in next 5-7 years..


Please watch Solix empower if you are interested in AI.
Somehow, transcript is not enabled on solix youtube channel. Otherwise, AI tool can give summary or details.
YouTube link of Solix empower happening today at 8.30pm IST.
youtube.com/live/M7frN6tz0FE…
Interestingly a post today from Sai gundavelli in LinkedIn mentioned it will be live in solix website too which is actually good to get people see their entire portfolio of products.

Value2Wealth Investor retweeted

YouTube link of Solix empower happening today at 8.30pm IST.
youtube.com/live/M7frN6tz0FE…
Interestingly a post today from Sai gundavelli in LinkedIn mentioned it will be live in solix website too which is actually good to get people see their entire portfolio of products.
Completely Agree .

Esconet — Q2 follow-up on my “Operating Leverage + Optionality” thesis.
I ended my earlier note saying Q2/Q3 need to prove that the earnings inflection can sustain.
Q2 provides stronger evidence.
Standalone — Hexadata + System Integration:
• Revenue ₹165.24 Cr, +171% QoQ
• Operating EBITDA ~₹18.08 Cr, +132% QoQ, excluding other income
• PAT ₹14.21 Cr, +108% QoQ
Employee + other expenses increased only 17.5%. The same cost base is supporting a much larger revenue pool — exactly the operating leverage discussed earlier.
Operating EBITDA margin was ~10.9%, broadly around the ~10% core-business assumption in my thesis, though below Q1’s 12.8%.
Standalone matters more here. Singapore adds substantial consolidated revenue at thin margins.
The interesting part: this profit growth has come while ZeaCloud and Fluidech remain loss-making at PBT level.
So the core earnings engine is delivering; the cloud + cybersecurity optionality has yet to contribute meaningfully.
MeitY empanelment remains the next catalyst to watch. Approval, utilisation and recurring revenue must follow.
Q2 strengthens Part 1 of the thesis. Part 2 still needs execution.
The business seems to have reached at inflection point.
Solid execution by the company.
Huge tailwinds, jus the beginning.
DYODD.


Excellent Result from Esconet . This market is sell on result announcement but hope it rewards it .
Thanks @malani4u for sharing this idea with me during bharat connect pune meet.
nsearchives.nseindia.com/cor…


Excellent result from Esconet Technologies.
This idea come on my radar after discussion with @malani4u . I have not publicly disclosed but shared with few. I was waiting for result .
Esconet Technologies this quarter profit is equivalent to last year . Do more study and keep eye on it for next few years.
Value2Wealth Investor retweeted
CFO also starts with PBT and adjusts for non-cash items:
PBT -10
Add: Depreciation 2
Working Capital Changes 0
-------------------------------
CFO -8
If a product company expenses almost all product development costs through the P&L instead of capitalizing them:
Reported profit can be very low or even negative.
Tax liability can be reduced or eliminated because taxable income is lower.
Cash flow from operations may also appear lower than companies that capitalize development costs since it starts with PBT.
However, the business may actually be generating substantial cash and choosing to aggressively reinvest it into product development.
Example company A
Revenue 100 Cr
Other operating costs 20 Cr
Product development 90 Cr
-----------------------------------------
PBT -10 Cr
The company A reports a loss and pays little or no income tax.
But the key question is:
Is the ₹90 Cr really a maintenance expense or a growth investment?
For a product company, much of that spend may be creating future products, IP, patents, AI models, platforms, etc. Economically, it behaves more like an investment than a normal operating cost.
Many sophisticated investors create an "economic earnings" view:
Reported Profit -10 Cr
Add back:
Growth Product Development 70 Cr
Less:
Maintenance Product Development 20 Cr
--------------------------------------------
Economic Profit 40 Cr ( -10 +70 -20 )
What to check
If a company reports losses for years but:
Revenue keeps growing
Gross margins are high
Customer retention is strong
Cash balance keeps increasing
Little debt is required
then the losses may simply reflect aggressive reinvestment in product development.
This type of companies can deliberately keep accounting profits near zero for many years while building valuable intellectual property and avoiding taxes through legitimate R&D spending. In fact, some of the most successful software companies historically looked barely profitable during their heavy product-building phase because they chose to expense development costs rather than maximize reported earnings. The key is determining whether the R&D spend is creating future value or simply covering ongoing operating losses.
Value2Wealth Investor retweeted
Emagia knocking on to making it into the leaders category in IDC AI enabled AR for enterprises. As noted even in AGM based on thier market positioning, they seem to be on the right path to get big enterprise wins, hopefully helping scale up revenues sooner.

This TechNvision agm is with video . Better than just voice .

I had the opportunity to attend the TechNVision Ventures 2026 AGM. It was a short AGM, but the questions were quite insightful and relevant.
Sharing the recording for anyone interested in going through the discussion and whatever I was able to capture. youtube.com/watch?v=Ei_rfFWc…

Value2Wealth Investor retweeted

There is unnecessary heart burn about our markets under performance and that
- Govt didn’t listen and cut tax
- FIIs are upset
- Media was too bullish - where will FIIs go
- Patriotism in claiming retail is more powerful than fii
Etc etc
Here, we are relying on others to do what we want them to do
Investing needs loners mindset
When stocks hit 25-50x : generally returns are poor in future
At a price - all this will stop mattering
At that price - there will be no interest to invest
Cycle wil repeat
That’s the first principle we all need to learn
Course correct in self - don’t seek correction In others
Uploaded TechNVision Ventures AGM 2026 video on Youtube . If you were not able to attend AGM then go through it .
Video : youtu.be/0OtXsWPB6wc
Substack Post : value2wealth.substack.com/p/…
TechNVision Ventures AGM 2026
Key Highlights
Substack Post Link : value2wealth.substack.com/p/…

Equisense team has come up with live Bharat Connect conference call , You can listen it or use live highlights for better breakdown of the call. equisense.ai/concalls/bharat…
