

I’m mostly known for calling out the dips of great companies | DYODD | 15% OFF on FiscalAI (Code: "VALUEINVESTOR" at checkout)👇
London
Joined June 2025
- Tweets3.1K
- Following374
- Followers1.5K
- Likes1.2K




Pinned Tweet
I'm thinking of buying $NBIS for one simple reason.
Today, Nebius is running roughly 20k GPUs.
The plan is ~60k end of FY and ~240k by 2027+
That's a 5x fold increase.
And the CEO has hinted at something even more aggressive: up to 1 GW in 2026
That’s the opportunity.

BREAKING
DONALD TRUMP ENDORSERS TIM COOK TO BECOME CEO OF $NVDA
WALL STREET IS THE MOST DRAMATIC MOVIE ON EARTH

NOW THAT Nvidia CEO JENSEN HUANG, who has done a fantastic job, has resigned, there is only one man to take his place - TIM COOK of Apple. A Legend replaces a Legend! President DONALD J. TRUMP
( TS: Nov 12 2026, 10:29 AM ET )
3
101
I think people underestimate how important Jensen has been for $NVDA
If Lisa Su resigned tomorrow from $AMD, I would sell my shares
Jensen Huang has been able to do 10x more than Lisa Su has. He has led a company from a dining table to the AI powerhouse it is today
However, we can't simply ignore the fact that the leadership transition here has been abrupt. And usually this doesn't end well.
1
140
The numbers are absolutely INSANE
$NBIS CEO “We expect prepayments and financing against existing contracts with investment-grade customers to cover 75%-85% of our 2027 capex, and have a wide range of other funding options available.”


4
654

$MSFT is down because Anthropic launched spreadsheet, whiteboard and data tools.
The bear case is fair. Microsoft 365 cloud revenue was $27.8B last quarter, about 30% of the company, and a well-funded rival selling Sheets, meetings and dashboards into that surface area is a real threat.
But the number that would prove it isn't there yet. Microsoft 365 Commercial Cloud revenue grew 17% while paid seats grew 5%, and the growth came mainly from more revenue per user: Copilot upgrades and higher-priced tiers. That's pricing power, and a franchise losing seats doesn't have it. Several of the new tools are also reportedly still in beta, and Anthropic's head of product said Sheets doesn't yet target complex work like financial modeling.
So what for investors: If paid seats keep growing and revenue per user keeps rising, this was a scare priced in one session. If seat growth stalls as companies move spreadsheets and meetings to Claude, the pricing-power story reverses.

1
2
391
$ONON beat EPS by 16 cents ($0.54 vs $0.38), raised its gross margin guide, grew direct-to-consumer sales 25%, and the stock closed down yesterday about 7.5%.
Here's what the market is reacting to. Management said DTC came in "slightly below" its own bar: online traffic was softer in a promotional market and two stores (Munich, Miami) slipped into Q4. Constant-currency growth was 17.8% in Q3 against 21.8% for nine months, revenue of CHF 931.4M was only in line, and the 72.6% gross margin includes CHF 52.6M of tariff refunds (66.9% without).
But net income rose 37% to CHF 162.8M, cash is CHF 1.34B, wholesale grew 13% in constant currency, and the full-year growth guide stayed at low-20s. Management says it held full price through the promotions.
I do think $ONON is a great brand ran by great people


I don’t know how anyone can be bullish in this market, and yet the S&P is firing away
Payrolls came in at +165K against roughly 65K expected, unemployment is 4.1%, and euro-area inflation hit 4.0%. Markets price about an 84% chance of a December Fed hike. Rates going up while inflation sticks around is not usually when people pay up for stocks.
So what’s carrying it?
AI.
Semiconductors were down 25.6% since end-September, then $SOXX jumped 7.5% in a single session. CoreWeave upbeat revenue forecast, sending Nasdaq futures higher meanwhile Alphabet’s long-term debt is now $125.1B versus $21.6B a year ago, and Google burned about $9B of free cash flow in the quarter.
I'm quite hesitant in deploying my cash unless I see real undervaluation, and that primarily is not in AI related stocks. Else I'm holding a big cash position. I'm currently losing because of that, but I see more short-term opps at the market right now instead of long-term opportunities
2
202
Bruh UTD is the worst run club in the world.
Pochettino is the one they chose? The guy barely has any trophies
UTD is becoming the new spurs, and these greedy owners have destroyed the club
Management just like in any company is the A to Z

🚨 Mauricio Pochettino, ready to become the new Man United head coach with talks progressing. #mufc
1
158
$ADBE is now INTEGRATED into Claude
AI is a catalyst for SaaS, boosting productivity
The SaaS stack is needed more than ever, and is as important as ever

$RKLB 's backlog jumped 52% in one quarter to $3.57B, and the stock was down about 6.7% after hours.
The bear case is specific. Neutron's first launch has slipped to 2027 after gaps were found in part of the carbon composite fuel tank dome. The adjusted loss was $0.12 a share against a $0.07 loss expected, GAAP opex came in at $169.3M versus a $143-149M guide, and the CFO said free cash flow stays negative at elevated levels.
But look at what customers did. Launch backlog nearly doubled to $1.85B from $940M, over $515M of Neutron deals were signed in the quarter, and the base price on several missions went up to $70M from $55M. Nobody raises price on a product people are walking away from. Revenue beat, adjusted gross margin came in at 38.4% against a 35-37% guide, and Q4 revenue is guided to $270-290M versus about $265.5M expected.
So what for investors: If the tank tests pass and a real Neutron date appears, the backlog starts converting and this was a delay with a price tag. If the tests slip again, $3.57B of backlog is waiting on a rocket that hasn't flown and the cash burn gets harder to defend.

1
3
371
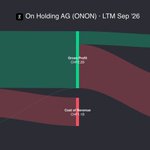
$ONON and $DECK are still EARLY in their growth in the running / athletic space
Picture taken from @AurelionRsch

DOUBLE BEAT
RAISED GUIDANCE
DISGUSTING GROSS MARGIN: 72.6%
INSIDERS BUYING
$ONON DELIVERED

ON $ONON Q3’26 EARNINGS HIGHLIGHTS
🔹 Revenue: CHF 931.4M (Est. CHF 929M) 🟢; +17.2% YoY
🔹 Adj. EPS: CHF 0.54 (Est. CHF 0.40) 🟢; +26% YoY
🔹 Gross Margin: 72.6%; +690 bps YoY
🔹 Adj. EBITDA Margin: 27.6%; +500 bps YoY
Raises FY26 Guide:
🔹 Gross Margin: ~66%; from at least 65%
🔹 Net Sales Growth: Low-20% range FXN; unchanged
🔹 Adj. EBITDA Margin: 19.5%-20.0%; unchanged
Segment Net Revenue:
🔹 Shoes: CHF 843.7M; +15.4% YoY
🔹 Apparel: CHF 69.5M; +38.7% YoY
🔹 Accessories: CHF 18.1M; +39.2% YoY
Key Updates:
🔹 U.S. Tariff Refunds: CHF 52.6M received in Q3
🔹 FY26 margin guide shown ex-tariff refunds
🔹 DTC: CHF 393.3M; +25.0% YoY
🔹 APAC: CHF 189.9M; +31.1% YoY
🔹 EMEA: Surpassed CHF 250M for the first time
Comments:
🔸 “In a promotional market, we stayed true to who we are and held full price, delivering record sales and record underlying margins.”
🔸 “That margin gives us the strength to invest in the innovation, technology, stores and new sports behind our next phase of growth, and every part of that investment maps back to our three-year plan.”

1
19
1,556


Few hours left and this beast is reporting
I'm excited
$ONON please prove us all right, and the haters wrong !

1
6
814
I'm an investor and have made more than 100% on my Google and Amazon positions BUT...
More than half of $GOOGL ’s earnings last quarter came from revaluing its stakes in Anthropic and SpaceX, not from its actual business. At $AMZN it was 46% of profit.
The bull argument is that 25x isn’t high next to 34x at the dotcom peak. I get it. But those gains are paper, they’re one-offs, and a stake can’t be revalued up by a factor of two every year. Strip them out and the P/E looks closer to 30. The only times it has been above 30 were right before or right after the three big crashes.
I’m not saying either company’s business is broken. $GOOGL and $AMZN both have real, growing operations. The point is narrower: the headline multiple is being flattered by profits that depend on private AI valuations continuing to rise.
I’d rather judge these two on cloud and ad revenue than on a number their own investments created.
So what for investors: If the AI stakes keep getting marked up, reported earnings stay inflated and the headline P/E keeps looking calm. If funding for AI companies dries up and those marks stall or fall, the paper gains vanish and the real multiple shows.

2
5
515
People underestimate how undervalued $META is
Over the last 2 years, the stock has done NOTHING
One day it will rip so hard to >$1000, and it will happen so quick, people will regret not buying earlier

4
468
I was super close to buying $APP last week and I didn't
BIG congrats to those who did because the stock has gained almost 75% since last week. Literally insane but also well deserved because the company delivered
This is just a lesson for how quickly things can turn in the market. When you find a good opportunity you need to jump right at it imo, before its too late

I'm always quite skeptical, especially when there are bounces like this in the market.
My folio is up +3% today, but still I feel uncomfortable with the fact that there is a wide range of risks both macro and political that could affect the market overall
I still think the market is not considering at all, that financing is very much circular for the AI buildout, and the biggest funder ($NVDA ) could undergo an investigation because of what happened with Jensen & China
3
680
$ONON is scheduled to announce
Q3 earnings results on Tuesday, before market open.
The consensus EPS Estimate is $0.49 (+14.0% Y/Y) and the consensus
Revenue Estimate is
$1.14B (+43.5% Y/Y).
Over the last 2 years, ON has beaten EPS estimates 75% of the time and has beaten revenue estimates 100% of the time.
Let’s get it