

A family office focused on micro/small cap equities. Not investment advice.
Joined July 2020
- Tweets414
- Following194
- Followers963
- Likes51.8K




Pinned Tweet
$SBC looks compelling here. SBC is a leading aesthetics and medical services franchisor/MSO in Japan, trading at roughly a 20% forward FCF yield on enterprise value and ~3x forward EV/EBITDA on my estimates.
The stock has struggled over the last two years due to its de-SPAC history, low liquidity, franchise fee restructuring, and a more competitive operating environment. Those headwinds now appear to be easing. Revenue grew sequentially in both Q1 and Q2, and Q2 revenue increased 13% Y/Y while adjusted EBITDA increased 32% Y/Y. Management has also indicated that the competitive environment has improved.
While the stock has started to react to these developments, I still believe the valuation remains very depressed relative to the underlying earnings and cash flow profile.
A large portion of SBC’s revenue is recurring, contractual, or tied to ongoing clinic activity. Gross margins are high, operating expenses have been relatively stable excluding acquired businesses and one-time items, and capex is low due to the asset-light model. Q2 gross margin was ~73%, consistent with FY2025, and the company ended Q2 with approximately $136M of net cash.
The company’s recent service fee increases should also benefit margins, as management has indicated that the associated incremental costs are limited.
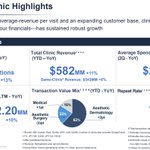
Clinic operating metrics are also improving. As of 2Q26, locations were up 13% Y/Y, same-clinic revenue was up 6%, average spend per visit was up 9%, visits were up 10%, and the customer repeat rate reached 73%.
If the current operating momentum persists, the combination of earnings growth and even modest multiple normalization could create meaningful upside
The key debate from here is whether the earnings reacceleration is sustainable and whether management can allocate its growing cash generation prudently.
This is not investment advice. Please do your own due diligence.


$URLOF $URL.CN Nice to see Paul (CEO) continuing to buy shares in the open market, adding to an already sizeable 8m+ share holding.


$URL.CN $URLOF solana:2QE381QgxWF76zPGTdokzPjkcQ5FaFuW1gXfTK7Spump @NameSilo is worth a look. The opportunity presents an existing high-growth recurring revenue business at an attractive valuation, with significant upside if they execute on their recently acquired robotics businesses.
The primary existing business today is a domain registrar growing revenue ~10%-15% per year, with predominantly recurring revenue, strong operating leverage, very low capital intensity, with net cash. Gross margins have expanded roughly 300-400bps annually over the last couple of years and were up another ~300bps Y/Y in 2Q26 to 28.5%. On a standalone basis, I estimate the stock currently imputes a valuation of ~10x NTM EV/EBITDA for this business, which I believe is attractive given these characteristics.
However, I think the real upside comes from its recently acquired robotics businesses, SewerVUE and Reach Systems. While they have temporarily diluted profitability through additional overhead and upfront investment, which I think helps explain some of the stock weakness over the last six months, they also provide new growth engines with potentially very attractive economics.
SewerVUE, which provides advanced pipe-inspection technology, is particularly interesting. Management is targeting roughly C$100K-C$120K of capex per unit while generating approximately C$50K-C$60K of recurring monthly data-processing revenue per unit, with the data-processing component potentially reaching 90%+ gross margins. That implies unit-level payback measured in only a few months. If those economics prove repeatable at scale, it would be an enviable business model: high growth, recurring revenue, very high margins, strong operating leverage, and exceptional returns on incremental capital.
If SewerVUE executes, I think $URL.CN has the potential to become a similar type of story to early $PNG.V: Differentiated robotics technology + strong unit economics + a potentially significant re-rate as scale is proven.
$XX.V posted strong March-quarter and FY26 results last week. Q4 rev +12% Y-Y, led by +35% in recurring rev. Gross margin +950 bps Y-Y to 45.2%, while adj EBITDA +77% Y-Y despite elevated year-end expenses and investment in growth initiatives.
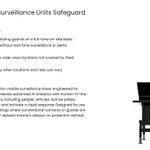
Mgmt remains highly bullish on MAST. Avante now has 29 units deployed, with 18 additional on order for delivery within four weeks. Recent traction includes Target Park, law enforcement, events and paid international pilots, with opportunities developing across Europe and Africa.
Mgmt expects its traditional security operations to grow 10–15% annually, supplemented by rapid growth from NSSG and MAST. It also expects gross margin and adj EBITDA margin to improve as higher-margin products scale and operating efficiencies increase.
Even after the recent stock appreciation, $XX.V trades at roughly 1.0x consensus NTM revenue and 13.5x NTM adjusted EBITDA. I think this remains an attractive valuation considering strong recurring revenue growth, margin expansion and meaningful upside if MAST converts its pipeline into recurring deployments.
youtube.com/watch?v=jkpKDbJe…


Good $RW.V interview from @MicroCapClub with CEO Doug Vickerson.
Key takeaway: RW is not trying to beat generic AI as a consumer design toy. RW sells to enterprise manufacturers, distributors, retailers, and contractors that need their own brand-controlled, product-accurate AI offering.
Generic AI can create attractive home-remodeling images. But enterprise customers need real products, correct colors/profiles/textures, SKU/configuration accuracy, regional availability, measurements, pricing, LeadPOD, contractor routing, and workflow integration.
That is where RW’s 20+ years of manufacturer relationships, product data, rendering experience, integrations, and enterprise trust matter.
Doug sees AI as a TAM expander and is targeting 30%+ ARR growth (+36% Y-Y in 1Q26) as RW continues to shift toward higher recurring licensing revenue.
Worth a listen.
youtube.com/watch?v=Fw-gR9hE…

$XX.V Avante announces its first major commercial agreement for MAST, with Target Park Group, which has 700+ parking locations across Canada and the U.S.
MAST will serve as the primary security layer across select above-ground lots, with potential future modules including vehicle ID, real-time lot monitoring and customer access.
Even at 100 locations, assuming only $2,500/month per unit before any technology add-ons, that would equal $3M of annual recurring revenue. More importantly, this gives real commercial validation to management’s bullish outlook for MAST.
avantecorp.ca/avante-announc…

The right take on $RW.V by SmallCap Discoveries - some of the smartest guys in the microcap space.


The table below compares $RW.V valuation vs LTM ARR growth, at each year-end and today, capturing both peaks and troughs. The stock is trading at a trough valuation despite accelerating ARR growth. On 1Q26 ARR the stock is trading at under 2x EV/ARR. On my 2026 estimate at 1.7x ARR, and on my 2027 estimate at 1.3x ARR.

Sharing my recent post on $RW.V at @MicroCapClub. The stock is currently trading <2x EV/ARR (1Q26) vs BVP's cloud index at 7.8x as of this post (cloudindex.bvp.com/). This is with 1Q26 licensing/hosting revenue (ARR) +36% y/y, 80% gross margin, net cash, internally funding growth, and several new AI/data/LeadPOD offerings being rolled out. This is not investment advice, please DYOR.

$RW.V 1Q26 financials showed a large increase in ARR, +21% Q-Q and +36% Y-Y. The stock is now trading at 1.8x EV/ARR 1Q26 run-rate, growing ARR >30% with an 80% gross margin, no debt, internally funding growth, and AI a potential tailwind.

$RW.V worth a look. High-growth vertical SaaS: +33% ARR in ’25, NRR +119%, FY25 profitable, net cash, 43% insider ownership. Trades at ~1.6x my est. ’26 ARR. Non-ARR service rev decline masks ARR growth. Priced for AI disruption; I think AI enhances/expands the offering. Illiquid


$WEB.V continuing to grow its disclosed pipeline (6 projects totaling 1.3GW). The project is well advanced, in stage 2 of the AESO interconnection process, reflecting the company's discipline in moving projects from it's overall pipeline, to its high-confidence disclosed pipeline

Westbridge Announces the Origination of 300 MWp Eastervale Solar PV plus 200MW/400 MWh Battery Energy Storage System in Alberta.
For more information, read the release: westbridge.energy/westbridge…
$WEB $WEGYF #SolarEnergy #CleanEnergy #Renewables #StocksToWatch #Solar #GreenEnergy

Within solar, the IRA was arguably most beneficial to community solar. $UGEIF $UGE.V @UGE_Intl CEO on the 2Q call talked about being able to capture an ITC as high as 60% on certain projects. A helpful article on what the IRA means for community solar.
solarpowerworldonline.com/20…

$UGEIF $UGE.V hitting an inflection. 7mw starting construction soon and 13mw in the coming months. Projects fully funded with debt/tax equity. Recent $15M credit line + green bond issuances secure funding at corporate level. Backlog at 229mw and total active dev pipeline at 416mw

Q3 brought meaningful growth across our backlog and operating portfolio. All the details here: ugei.com/uge-announces-q3-20… #solar #communitysolar